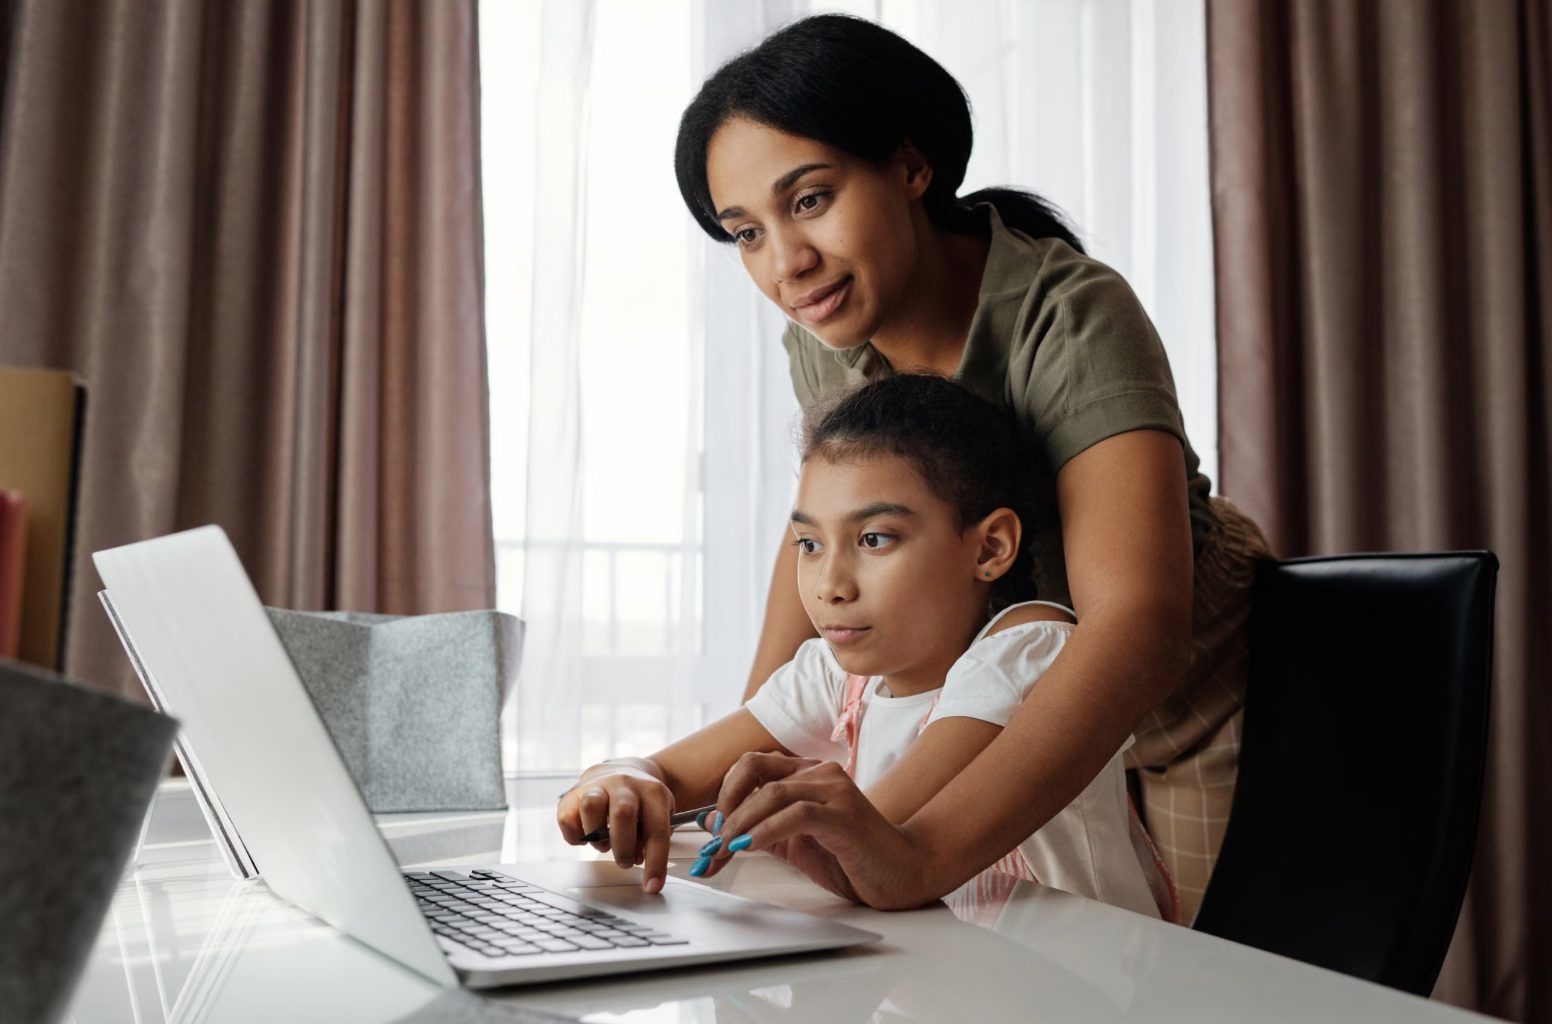
Kids often notice family financial struggles long before parents officially explain them. They hear conversations about bills, notice when restaurant dinners disappear, or wonder why a planned vacation suddenly gets canceled. The challenge for parents is deciding how much honesty is appropriate without making children feel responsible for fixing an adult problem. There is no universal “right age,” but child-development experts suggest gradually increasing financial transparency as children become capable of understanding budgets, tradeoffs, and consequences.
Start With Simple Money Lessons In Elementary School
Children do not need a detailed explanation of credit-card balances or overdue bills to understand that money has limits. The Child Mind Institute says most children have enough math skills by second or third grade to begin learning about money, budgeting, saving, and spending decisions. For a 7-year-old, explaining family financial struggles might mean saying, “We’re spending less right now, so we’re cooking at home instead of ordering pizza.” That provides an honest explanation without making the child wonder whether the family will lose its home. Parents can also involve younger children in low-stakes decisions, such as comparing grocery prices or choosing between two affordable activities.
Give Tweens More Context Without Giving Them Your Anxiety
By roughly ages 10 to 12, many children can understand that household income must cover housing, food, transportation, utilities, and other necessities before extras. This is a reasonable stage to explain that family financial struggles sometimes require temporary changes, such as postponing a vacation or buying fewer new clothes. The American Academy of Pediatrics’ HealthyChildren.org recommends teaching children to divide money among saving, spending, and sharing, helping them understand that financial choices involve priorities. Parents should still avoid unloading fears such as, “I don’t know how we’ll survive if I lose my job.” A better message is specific but reassuring: “Money is tighter this year, so we have a plan to spend less.”
Teenagers Can Handle More Of The Real Numbers
Teenagers generally need more financial information because family finances increasingly affect decisions they participate in, from driving and extracurricular activities to college planning. Consider a household that previously spent $300 monthly on entertainment but must cut that amount to $100 after a parent’s hours are reduced; showing a teenager that $200 tradeoff can make the situation concrete without handing them the entire household ledger. Financial pressure is hardly unusual: an April 2026 LendingTree survey found 82% of parents said raising children had become more expensive over the previous year, while 64% said they had gone into debt to cover child-related costs. Discussing family financial struggles honestly can therefore teach teenagers that changing spending habits is a practical response rather than something shameful. Older teens can even help identify discretionary expenses, provided parents make clear that paying household bills remains the adults’ responsibility.
The Hidden Risk Is Making Kids Feel Responsible
The biggest issue may not be whether children know money is tight, but whether they start believing they must rescue the family. Research published in the Maternal and Child Health Journal in 2025 found that 55% of low-income families with young children in its study showed profiles involving medium-to-high levels of family stressors, highlighting how economic pressure can extend beyond the bank account. That is why statements such as “We can’t afford anything because you kids cost so much” can be especially damaging and should be avoided. Instead, parents can frame family financial struggles around choices and plans: “We’re cutting expenses while we rebuild our savings.” Children should understand the reality affecting their lives without becoming emotional partners in managing debt, job insecurity, or marital disagreements about money.
Financial Pressure Is More Common Than Children May Realize
Parents may also worry that acknowledging money problems will make their family seem unusually unsuccessful, but recent numbers provide important perspective. Bankrate’s 2026 Emergency Savings Report found 29% of U.S. adults had more credit-card debt than emergency savings, while 58% said their emergency savings were the same as or lower than a year earlier. Meanwhile, 85% said they would need at least three months of expenses saved to feel comfortable, yet only 46% actually had that much. Those numbers can help older teens understand why an unexpected $1,500 car repair can force an otherwise responsible family to change its budget quickly. The lesson is not that financial hardship is inevitable, but that emergency savings, controlled spending, and honest planning matter.
Kids Need Honesty Without Carrying The Burden
Children should gradually learn about money from elementary school onward, while detailed conversations about genuine financial hardship should expand as they mature. Parents do not need to reveal every debt balance, collection notice, or fear simply to be truthful. Instead, explain what is changing, why reasonable spending limits exist, and what the adults are doing about the situation. That approach gives children useful financial knowledge while preserving the sense of security they still need from their parents.
At what age did you first realize your family was struggling financially, and do you think your parents handled that conversation well? Share your experience in the comments.
What to Read Next
Why Children With Autism Often Struggle With Summer Transitions
The Truth About Teen Finances: 10 Money Habits Parents Are Teaching Kids That Keep Them Poor
How to Raise a Resilient Kid—Even If You’re Struggling Yourself

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Read More
Meltdowns are part of toddler life, but some of our well-meaning reactions can make them…
Black Friday can make even the sanest shopper pull out her hair. It’s uncommon to…
Back-to-school season can bring a surprisingly complicated stack of expenses for families raising children with…
Image Source: Unsplash We’re seeing a critical conversation unfold in many families today—one where parents,…

Many parents grapple with the decision of whether to allow their children to watch R-rated…
For years, autism research and diagnosis patterns centered largely on boys, leaving many families unaware…


Leave a Reply