• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

Dollar General Adds 170+ Holiday Toys — About Half Cost $10 or Less

October 9, 2026 | Leave a Comment

Dollar General
Dollar General’s 2026 holiday collection features more than 170 seasonal toys, with approximately half priced at $10 or less. Families can also find $1 stocking stuffers and save 25% on qualifying toy purchases of $75 or more through December 24. (Wikimedia Commons).

Holiday shopping can quickly become expensive, especially when parents and grandparents have several children on their Christmas lists. This year, Dollar General is giving families more ways to stretch their holiday budgets without sacrificing the excitement of gift-giving. The retailer has introduced more than 170 seasonal toys for 2026, with approximately half priced at $10 or less. However, some of the biggest savings opportunities come with spending requirements and restrictions shoppers should understand before heading to checkout.

More Than 170 Holiday Toys Offer Budget-Friendly Choices

According to Dollar General’s September 24 announcement, approximately 95% of its seasonal toy assortment costs $20 or less. The retailer is also introducing a dedicated shelf featuring toys priced at $5 and under. These affordable Dollar General holiday toys could help families purchase multiple gifts without spending hundreds of dollars. For example, a grandparent shopping for four grandchildren could purchase two $10 toys per child for $80 before taxes. However, shoppers should remember that the advertised price ranges describe the overall assortment, not necessarily what every store has available.

Popular Toy Brands Are Part Of The Holiday Selection

The 2026 Dollar General holiday toys include recognizable brands that children may already have on their Christmas wish lists. Shoppers can find products featuring Pokémon, Bluey, Spider-Man, Disney’s Stitch, and Formula 1 racing. The assortment also includes more than 20 new LEGO sets priced between $5 and $30. Play-Doh products range from $2.50 to $15, providing additional options for younger children. Families should compare individual products carefully because a smaller, inexpensive version of a popular toy may differ considerably from the larger version a child requested.

Stocking Stuffers Start At Just $1

Parents looking for inexpensive stocking stuffers may find some of the best Dollar General holiday toys among the smallest items. The company is offering more than 40 giftable products priced at $1, including coloring books, stickers, novelty pens, and activity books. Shoppers can also find $2 Hasbro Classic Mini Games featuring Connect Four, Yahtzee, Operation, and Hungry Hippos. According to ConsumerAffairs’ September 25 report, the expanded assortment includes collectibles and games designed for budget-conscious holiday shoppers. A family purchasing ten $1 stocking stuffers would spend just $10 before taxes, although checking age recommendations and avoiding duplicate gifts remains important.

A Holiday Discount Could Save Families Even More

One of the biggest opportunities to save on Dollar General holiday toys is the retailer’s seasonal discount. From October 1 through December 24, 2026, qualifying toy purchases totaling at least $75 in a single transaction receive 25% off. That means an eligible $80 toy purchase would cost $60 before taxes, saving the shopper $20. The promotion also includes qualifying clearance toys, although certain exclusions apply. Families should verify eligible merchandise before checkout because purchasing additional toys simply to reach the $75 threshold could erase the benefit of the discount.

The $75 Spending Requirement Has A Hidden Tradeoff

Although the 25% discount sounds attractive, families should calculate whether meeting the minimum purchase requirement actually makes financial sense. Someone planning to spend $50 would need to add another $25 in qualifying toys to reach the promotion’s threshold. A $75 eligible purchase would then cost $56.25 before taxes, which is $6.25 more than the shopper originally intended to spend. That additional expense might be worthwhile if the extra toys are already on someone’s Christmas list. Otherwise, sticking with the original budget could be the smarter financial decision.

Craft Supplies Offer Another Affordable Gift Option

Dollar General’s holiday savings extend beyond traditional toys into arts and crafts. The retailer reports carrying more than 300 crafting products, with 85% priced below $5 and over 50 items costing just $1. Available supplies include paint, stickers, ribbons, air-dry clay, and materials for decorating wooden or canvas surfaces. The Toy Association’s 2026 trends report also identifies growing interest in hands-on, screen-free play experiences. Families could combine several inexpensive supplies into personalized craft bundles, although adults should check age labels and consider whether additional materials are required.

Shopping Online May Add Unexpected Expenses

Convenience matters during the holidays, particularly for parents balancing work, school activities, and shopping. Dollar General offers shopping through its myDG platform, with delivery available from participating stores. However, shoppers should compare delivery charges, potential service fees, and item prices before assuming an online order is cheaper. The retailer’s official terms and conditions explain rules and conditions that can affect online purchases and offers. Checking the final total before submitting an order can prevent unexpected costs from reducing holiday savings.

The Best Holiday Bargain Is Staying Within Your Budget

Dollar General’s expanded 2026 toy assortment gives families more affordable options during an expensive shopping season. With more than 170 seasonal toys, $1 stocking stuffers, and a qualifying 25% discount, shoppers have several ways to reduce gift expenses. Still, the smartest purchases are those that match children’s interests without exceeding the family’s spending limit. Comparing prices, checking promotional restrictions, and planning purchases ahead of time can make a meaningful difference.

Would you rather purchase several inexpensive gifts or spend more on one special present, and why? Share your thoughts in the comments.

What to Read Next

Would You Let Your Child Add Whatever They Want to Your Online Shopping Cart?

7 Parenting Expenses That Quietly Drain Budgets After the Holidays

Bought Kids’ Toys From SHEIN or Amazon? Check These New Recalls Before Playtime

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Shopping Tagged With: Affordable Toys, budget shopping, Christmas 2026, Christmas gifts, Dollar General, Dollar General Holiday Toys, Family Budgeting, Holiday Savings, holiday shopping, stocking stuffers, toy deals

Waiting for Childcare Assistance in Florida? Here’s What Parents Can Do While Their Application Is Pending

October 8, 2026 | Leave a Comment

Child Care
Florida parents waiting for childcare assistance can explore free referral services, Head Start programs, and affordable daycare alternatives while keeping their applications active. Missing important waiting-list deadlines could delay much-needed financial relief. (Pexels).

For Florida parents struggling to afford daycare, waiting for childcare assistance can feel like another full-time job. You submit your application, gather the paperwork, and hope financial relief arrives before another expensive childcare bill comes due. Unfortunately, qualifying for help doesn’t necessarily mean funding will become available immediately. If you’re waiting for Florida childcare assistance, understanding your options could help protect your budget, maintain your employment, and prevent costly application mistakes.

Understand Why Your Application May Still Be Pending

Florida’s School Readiness program helps eligible families pay for childcare while parents work, attend school, or participate in approved training. However, Florida childcare assistance depends on available funding, meaning eligible families may be placed on waiting lists. According to the Early Learning Coalition of Florida’s Heartland, limited budgets prevent every qualifying family from receiving immediate assistance. Families should contact their local Early Learning Coalition to determine whether their application is awaiting review, missing documentation, or waiting for funding. Understanding that distinction helps parents decide what to do next instead of assuming their application has been forgotten.

Keep Your Application Active To Avoid Losing Your Place

One overlooked requirement could cause families to lose their waiting-list status without realizing it. The Heartland coalition explains that its Family Portal sends an update request after 150 days, giving families 30 days to respond before their application becomes inactive. Parents waiting for Florida childcare assistance should regularly check their portal accounts, emails, and spam folders for important notices. Keep recent pay stubs, employment verification, identification, and household information organized so requested documents can be submitted promptly. Missing a deadline could mean starting the waiting-list process again, potentially extending an already stressful financial situation.

Ask About Free Childcare Referrals Before Paying Full Price

Many parents assume their only options are expensive daycare centers or asking relatives for help. However, Florida’s Child Care Resource and Referral network provides free assistance locating childcare programs, including family childcare homes and providers offering different schedules. The Early Learning Coalition of St. Lucie County explains that families can request information about affordable childcare, special-needs services, and summer programs. Parents should ask which providers accept School Readiness assistance, offer part-time enrollment, or have openings that match their working hours. Remember that referrals aren’t endorsements, so independently check licensing, inspection histories, and safety practices before enrolling your child.

Explore Head Start And Early Head Start Programs

Families waiting for Florida childcare assistance may qualify for another program without waiting for School Readiness funding. The Florida Head Start Association helps families locate Head Start and Early Head Start programs serving eligible children from birth through age five. These federally supported programs provide early education and family services, with eligibility generally determined by income or qualifying circumstances. Children experiencing homelessness, children in foster care, and families receiving certain public benefits may qualify under additional eligibility provisions. Availability varies by location, so parents should contact nearby programs directly and ask about enrollment openings, schedules, transportation, and waiting lists.

Check Whether Your Four-Year-Old Qualifies For Free VPK

Florida’s Voluntary Prekindergarten program offers another opportunity to reduce childcare expenses for families with eligible four-year-olds. According to the Early Learning Coalition of St. Lucie County’s VPK guidance, the school-year program provides 540 instructional hours, while the summer option provides 300 hours. Unlike income-based childcare assistance, VPK eligibility generally does not depend on household income. However, parents needing full-day supervision should understand that free instructional hours don’t automatically cover before-school or after-school childcare. Ask participating providers about additional hourly charges, registration fees, and whether combining VPK with another assistance program could reduce your expenses.

Ask Your Employer About Flexible Scheduling And Childcare Benefits

While waiting for Florida childcare assistance, parents should consider whether temporary workplace adjustments could reduce childcare expenses. Some employers offer dependent-care flexible spending accounts, childcare discounts, backup-care benefits, or alternative schedules, although these benefits aren’t universally available. For example, changing from five childcare days to three could lower expenses if the provider offers genuine part-time pricing. Parents should also ask whether a spouse or trusted family member can cover certain hours without jeopardizing employment or creating unsafe supervision arrangements. Before using a dependent-care account, confirm eligible expenses and reimbursement requirements because pending childcare assistance doesn’t guarantee every payment will qualify.

The Waiting Period Doesn’t Have To Drain Your Family’s Savings

Waiting for Florida childcare assistance creates genuine financial pressure, especially when parents must maintain employment while covering daycare expenses. However, checking application deadlines, exploring alternative programs, and comparing temporary childcare arrangements can make the waiting period more manageable. The most important step is staying connected with your local Early Learning Coalition while investigating other legitimate assistance opportunities. Families should never assume their waiting-list position guarantees an approval date or that every childcare expense will eventually be reimbursed.

Have you experienced a lengthy childcare assistance wait in Florida, and what unexpected expense or solution made the biggest difference for your family? Share your experience in the comments to help other parents navigate the process.

What to Read Next

Florida Special Ed Funding Changes: What Families Should Expect

Florida Families Report Longer Delays for School-Based Autism Services

Florida Families Say Social Security Delays Are Disrupting Autism Therapy Access

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Affordable Childcare, childcare costs, childcare subsidies, childcare waiting list, daycare assistance, family finances, Florida childcare assistance, Florida family resources, Florida parents, Florida VPK, Head Start Florida, Parenting, School Readiness Florida

What Does a Teenager Actually Add to the Grocery Bill?

October 7, 2026 | Leave a Comment

Teen Eating Breakfast
Feeding a teenager can cost roughly $270 to $474 per month for food at home under current food-plan estimates. Smart meal planning and reducing food waste can help families control the teenager grocery bill without sacrificing nutrition. (Pexels).

If your teenager can empty a refrigerator faster than you can restock it, you are not imagining the financial impact. A teenager grocery bill can rival what many households spend feeding an adult, especially when sports, growth spurts, snacks, and convenience foods enter the picture. Current food-plan estimates suggest feeding one teen at home can easily cost several hundred dollars each month. Understanding where that money goes can help parents budget realistically without turning every trip to the kitchen into a family argument.

The Monthly Number May Surprise You

The latest August 2026 food-plan figures put the teenager grocery bill into perspective. For ages 14 to 19, the low-cost plan runs about $271 per month for females and $322 for males, while the moderate-cost plan reaches roughly $323 and $403, respectively, according to a current breakdown of USDA food-plan data. At the liberal level, monthly costs reach about $399 for females and $474 for males. That translates to roughly $3,250 to $5,700 per year for one teenager, depending on sex, food choices, and spending level. Importantly, these plans assume meals and snacks are prepared at home, meaning restaurant meals, delivery, and other food purchases can raise the real total.

Growth And Activity Change The Equation

Teenagers are not simply eating more because they enjoy raiding the pantry; adolescence creates legitimate nutritional demands. HealthyChildren.org, from the American Academy of Pediatrics, says boys require an average of about 2,800 calories per day and girls about 2,200, although individual needs vary. The Academy of Nutrition and Dietetics reports that active teenage boys may need roughly 2,600 to 3,200 calories daily, while active teenage girls may need 2,200 to 2,400. A teen running cross-country or practicing football after school can therefore have substantially different food needs from a less-active teen. Parents trying to lower a grocery bill should focus on getting more nutrition for each dollar rather than simply cutting portions.

Today’s Grocery Prices Magnify The Cost

Families are also feeding teenagers after an unusually steep run-up in grocery prices. An Associated Press analysis published in 2026 reported that food-at-home prices in U.S. cities had climbed 33% since the beginning of 2019. Consider a household spending $350 a month on food for one teen: that works out to $4,200 annually before takeout, school purchases, or after-practice stops. Add two $10 convenience meals each week, and another $1,040 disappears over a year. The hidden lesson is that controlling the teenager grocery bill depends not only on how much a teenager eats but also on where, when, and what they eat.

Snacks And Waste Can Quietly Inflate Costs

The biggest budget problem may not be the extra chicken breast served at dinner but everything eaten between meals. Individual protein shakes, snack bars, sports drinks, frozen meals, and grab-and-go packages can make it harder to control spending than basic foods purchased in larger quantities. Families can compare unit prices and keep filling foods such as oatmeal, bananas, eggs, yogurt, peanut butter, beans, rice, and popcorn available for hungry teens. Buying in bulk is not automatically cheaper, however, because savings disappear when oversized packages go uneaten. That matters because ReFED’s 2026 U.S. Food Waste Report estimates that 70 million tons of surplus food were generated in 2024, representing about 29% of the U.S. food supply.

The Refrigerator Raid Has A Real Price Tag

A realistic teenager grocery bill can land around $270 to $474 per month under current food-plan estimates, with sex, activity, location, and shopping habits influencing what an individual family actually spends. These numbers are planning benchmarks, not rules for how much a particular teenager should eat or cost to feed. The best savings often come from planning meals, comparing unit prices, buying versatile staples, limiting pricey single-serving products, and making sure purchased food gets eaten. Tracking the teenager grocery bill separately for just one month may reveal that convenience purchases and waste are costing more than larger dinner portions.

How much has feeding a teenager changed your grocery budget, and what strategies have actually worked in your household? Share your experience in the comments.

What to Read Next

8 Money Lessons Kids Can Learn From One Trip to the Grocery Store

Summer EBT Facts That Could Put $120 on Your Grocery Card

SUN Bucks 2026: How Families of Special Needs Students Can Claim Summer EBT Grocery Benefits

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Money and Finances Tagged With: Family Budget, food costs, grocery budget, grocery prices, Grocery Shopping, household expenses, Parenting, Saving Money, teenagers

Have an Elmo Teether in the Freezer? Check It Before Giving It Back to Baby

October 6, 2026 | Leave a Comment

Elmo Teether
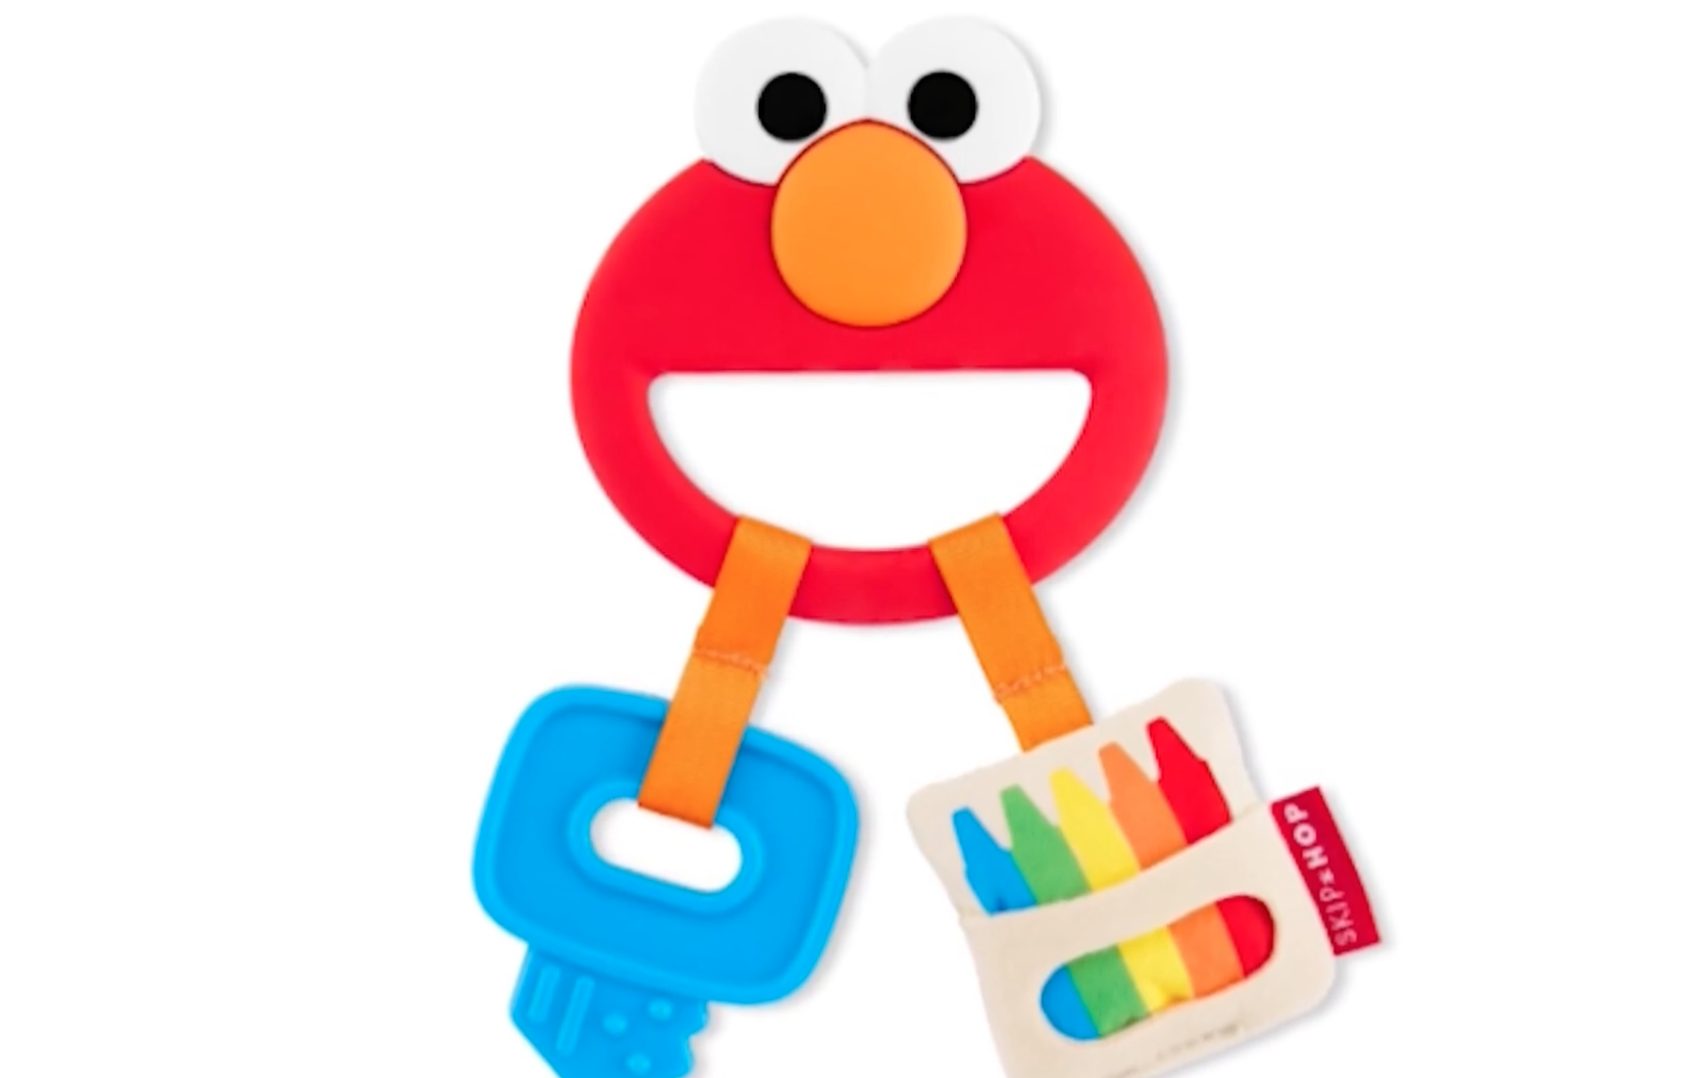
Skip Hop’s Baby “Sesame Street” Elmo Silicone Teether, model 9R263210, has been recalled because its black eye pieces can detach if frozen and create a choking hazard. Parents with the affected model should stop using it and follow Skip Hop’s recall instructions. (KVUE/YouTube).

That familiar red Elmo face sitting in your freezer may deserve a closer look before it goes back into your baby’s hands. A Skip Hop Baby “Sesame Street” Elmo Silicone Teether has been recalled because its black eye pieces can detach if the product is frozen, creating a choking hazard. The Elmo teether recall affects about 22,660 units sold in the United States, so this is more than an isolated product complaint. Parents and caregivers should identify the model, stop using it if it matches the recall, and follow the manufacturer’s instructions rather than assuming the toy is safe because nothing appears loose.

Why The Elmo Teether Recall Matters

The Elmo teether recall involves Skip Hop model 9R263210, a red, orange and white Elmo-face teether that includes a blue textured key and multicolored fabric crayon box. According to Good Housekeeping, the black pupils can detach when the recalled teether is frozen, potentially leaving a small piece that a baby could choke on. About 22,660 units were recalled in the United States after four reports of the eyes detaching, although no injuries had been reported when the recall was announced. The teethers were sold at Carter’s stores nationwide and online from January 2025 through March 2026 for approximately $12. For families, the absence of reported injuries should not be interpreted as proof that continued use is safe because the recall specifically identifies a potential choking hazard.

Check The Model Instead Of Guessing

Parents should look for model number 9R263210 on the red Skip Hop tag attached to the fabric crayon box rather than relying solely on the toy’s appearance. Parents reports that the affected product features Elmo’s face, the blue textured key and the fabric crayon box, giving caregivers several details to compare. If the model number matches, the Elmo teether recall instructions say to stop using the product immediately and keep it away from children. That means a parent should not keep using the affected teether simply because its eyes still feel secure or because it was never placed in a freezer. Checking the tag also matters at grandparents’ homes, day care bags and other places where baby gear can remain long after its original packaging disappears.

Do Not Throw It Away Just Yet

The company’s official Skip Hop recall program requires consumers to document destruction of the recalled product before receiving the remedy, so immediately tossing it in the trash could create an unnecessary problem. If the teether is frozen, Skip Hop instructs consumers to remove it and let it thaw before writing “Recall” and the destruction date across Elmo’s nose in permanent ink. Consumers are then instructed to cut through the black pupils with household scissors, photograph the destroyed teether and submit the requested information through the recall website. After review, Skip Hop says U.S. consumers will receive a $12 gift card within two to three weeks that can be used at William Carter Company brands including Carter’s, Skip Hop, OshKosh B’gosh and Little Planet. For a family that paid roughly $12 for the product, the gift card essentially matches its original selling price, but an important limitation is that the recalled teether cannot simply be returned to a retail location.

The Freezer Detail Offers A Bigger Safety Lesson

The Elmo teether recall centers specifically on what can happen when this particular product is frozen, but it also gives parents a reason to review how they chill other teethers. The Children’s Hospital of Philadelphia recommends cold teething toys for discomfort but advises against freezing teething toys or rings because very hard frozen items can hurt a baby’s gums. The American Academy of Pediatrics’ HealthyChildren.org offers more nuanced advice, recommending solid rather than liquid-filled teething rings and warning parents to remove chilled or frozen rings before they become rock hard. That distinction matters when a tired parent is looking for quick relief for a fussy baby: colder and harder do not automatically mean better. Parents should follow the instructions for each individual teether and inspect it regularly for cracks, tears, loose pieces or other changes before handing it to a child.

One Small Tag Can Answer The Big Question

The most important takeaway from the Elmo teether recall is that parents do not have to guess whether their child’s toy is affected. Model 9R263210 is the number to look for, and owners of the recalled product should stop using it and complete Skip Hop’s destruction-and-photo process to receive the $12 gift card. The recall also highlights a broader habit worth adopting: read manufacturer instructions and routinely inspect anything babies repeatedly put into their mouths. A teether can look perfectly ordinary while a small component or product-specific use condition creates a risk that is not obvious at first glance.

Have you checked your baby’s teethers and other frequently used products lately, and do you think manufacturers make recall information easy enough for busy parents to find? Share your experience and thoughts in the comments.

What to Read Next

Bought Kids’ Toys From SHEIN or Amazon? Check These New Recalls Before Playtime

Choking Incident Prompts Recall of 49,000 Target Gigglescape “Under the Sea” Popping Toys

CVS Medicated Wipes Recalled Over Child-Poisoning Risk

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: baby product recall, baby safety, choking hazard, Elmo teether recall, Parenting, Sesame Street, Skip Hop recall, teething safety

10 Baby Names That Sound Rare — But Are Becoming More Popular Than You Think

October 6, 2026 | Leave a Comment

Young Baby
Names such as Atlas, Iris, Eloise and Callum may sound unusual, but 2025 birth data shows their popularity is rising. Checking long-term trends and alternate spellings can reveal how rare a favorite name really is. (Pexels).

Choosing a baby name can feel like a balancing act: distinctive enough to stand out, but familiar enough that people can pronounce it. The latest 2025 U.S. naming data shows that several supposedly unusual choices are quietly becoming popular baby names. Some have climbed hundreds of positions in a decade, while others are vintage names finding a new generation of fans. Before assuming your favorite is rare, these 10 names are worth a closer look.

1. Ailany Is Suddenly Near The Top

Ailany might sound uncommon, but its rise has been remarkable. According to Nameberry, it jumped from No. 101 in 2024 to No. 14 in 2025. The number of girls receiving the name surged from 2,596 to 7,136 in just one year. Variations including Ailani and Aylani also appear in birth records, making the overall sound more familiar than one ranking suggests. Parents seeking rare popular baby names should always investigate alternate spellings.

2. Eloise Has Quietly Reached The Top 50

Eloise still has the charm of a vintage name pulled from a family tree. Yet it reached No. 49 in 2025, with 4,251 girls receiving the name, according to Nameberry’s Eloise data. That is a striking change from 2014, when Eloise ranked No. 302 with 1,081 births. Familiar nicknames such as Ellie, Lola and Lolo may add to its appeal. Parents wanting something truly uncommon may be surprised by how mainstream Eloise has become.

3. Iris Is Blooming Again

Short, botanical and rooted in Greek mythology, Iris can still feel refreshingly different. The name climbed to No. 61 in 2025 after ranking No. 71 in 2024. Current Iris popularity data shows 3,729 girls received the name in 2025, compared with 1,330 in 2014. That means its annual usage has nearly tripled in 11 years. For families considering nature-inspired popular baby names, Iris is no longer an obscure floral choice.

4. Clara Is Becoming A Modern Classic

Clara has the advantage of sounding recognizable without immediately seeming trendy. Nevertheless, it climbed from No. 78 in 2024 to No. 63 in 2025. About 3,601 girls received the name in 2025, up from 3,060 the previous year. Its short spelling, straightforward pronunciation and vintage character may help explain its staying power. Clara demonstrates how an old-fashioned choice can quietly become one of today’s popular baby names.

5. Millie Is No Longer Just A Nickname

Millie once sounded like an affectionate nickname belonging to another generation. Today, it stands comfortably on its own and ranked No. 73 among girls in 2025. Its usage increased from just 618 births in 2014 to 3,353 in 2025. That pushed Millie from No. 507 to the Top 100 in only 11 years. Parents attracted to its vintage sweetness should expect to encounter other young Millies.

6. Atlas Has Made A Dramatic Climb

Atlas sounds bold enough that parents might assume very few children actually carry it. In reality, Nameberry’s Atlas figures show it reached No. 75 among boys in 2025, with 4,413 births. Back in 2014, Atlas ranked No. 639 and was given to only 411 boys. That means annual usage increased more than tenfold over 11 years. Atlas is a clear example of how quickly rare-sounding popular baby names can move toward the mainstream.

7. August Has Returned To The Top 100

August combines an old-fashioned style with the instant familiarity of a calendar month. It ranked No. 81 among boys in 2025, improving from No. 88 in 2024. The name was given to 3,958 boys in 2025, compared with 1,545 in 2014. Approachable nicknames such as Auggie and Gus also give parents options as a child grows. Its numbers show August has moved well beyond being an eccentric vintage choice.

8. Callum Is Closing In On The Top 100

Scottish name Callum can still sound relatively uncommon to many American parents. However, it jumped from No. 159 in 2024 to No. 118 in 2025. Births climbed from only 327 in 2014 to 2,995 in 2025, a dramatic increase in little more than a decade. Its easy nickname Cal gives families a familiar option while preserving the distinctive full name. Anyone searching for uncommon popular baby names should watch Callum particularly closely.

9. Soren Is Gaining Fresh Momentum

Soren remains considerably less common than household names such as Liam or Noah. Still, it jumped from No. 571 in 2024 to No. 464 in 2025. The number of boys named Soren rose from 502 to 665 in that single year. Its Scandinavian roots help it retain a distinctive identity even as more American parents discover it. The trend also illustrates why today’s rare name may feel considerably less rare by the time a child reaches school.

10. Caius Is Quietly Moving Up

Caius remains genuinely unusual, making its recent movement particularly interesting. The Latin-rooted name climbed from No. 1,061 in 2024 to No. 927 in 2025. Births increased from 205 to 254 during the same period. That is nowhere near Top 100 territory, but crossing into the Top 1,000 makes Caius a name worth watching. Parents wanting a truly uncommon choice may find it offers a better rarity-to-recognition balance than several faster-growing alternatives.

A Rare Name Can Become Familiar Faster Than Expected

Popularity rankings are useful, but parents should look beyond one number before making a final decision. A hidden limitation is that official statistics count spellings separately, so names that sound alike can collectively be more common than their individual rankings imply. Nameberry’s 2025 Playground Analysis illustrates this by grouping similar-sounding spellings and showing how dramatically perceived popularity can change. Before choosing a name, check its decade-long trend, alternate spellings and similar-sounding versions rather than relying solely on today’s rank.

Which supposedly rare baby name have you suddenly started hearing everywhere, and would growing popularity make you reconsider using it? Share your thoughts in the comments.

What to Read Next

12 “Grandma” Baby Names That Are Suddenly Cool Again

What Does a Baby Actually Cost in the First 12 Months?

10 Baby Names Everyone Thought Were Gone for Good — But Parents Are Bringing Them Back

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: baby name trends, baby names, boy names, girl names, Parenting, popular baby names, Pregnancy, rare baby names, unique baby names

A Teen Gets Their First Job — Who Pays for Gas, Clothes and Going Out Now?

October 5, 2026 | Leave a Comment

Working Teen
A teenager’s first paycheck can bring new freedom and new questions about who pays for gas, clothes and entertainment. Gradually sharing expenses can teach budgeting while leaving room to save. (Pexels).

A teen’s first job can feel like a financial turning point for the entire family: suddenly, your child has a paycheck, a debit card and opinions about how that money should be spent. For parents, the tricky question comes next—does earning money mean the teen should start paying for gas, clothes, meals with friends and other expenses Mom or Dad previously covered? There is no universal formula, but immediately handing over every expense can leave a new worker with little opportunity to save or learn from the money they earn. A better approach is deciding which expenses represent growing independence and which remain part of raising a teenager. That conversation matters even more when everyday costs are high.

A Paycheck Does Not Automatically Mean Financial Independence

Working teenagers are hardly unusual, but a paycheck does not necessarily provide enough money to cover everything associated with teenage life. A 2026 Pew Research Center analysis found that 35.5% of Americans ages 16 to 19 were employed during summer 2026, with an average 6.2 million teens working during June and July. Food service accounted for 32% of employed teens and retail another 21%, meaning many young workers are starting in industries where schedules and hours may fluctuate. That makes it risky for parents to assign large fixed expenses based simply on the arrival of a first paycheck. Treating a teen’s first job as instant financial independence can confuse earning experience with adult-level earning power.

Start With Wants Before Shifting Essential Expenses

One practical approach is having teenagers take responsibility for discretionary purchases first, including restaurant meals with friends, entertainment, gaming purchases or nonessential clothing. That gives a first job a clear purpose without making employment necessary simply to get to school or meet basic needs. Families can then gradually introduce predictable expenses, perhaps asking a driving teen to pay part of the gasoline rather than immediately covering insurance, maintenance and every fill-up. The distinction matters because AAA reported the national average for regular gasoline at about $4.41 per gallon on Oct. 1, 2026, after a record-setting September at the pump. Before transferring an expense, parents should ask a straightforward question: Is this teaching responsibility, or are we giving our teenager a bill they realistically cannot control?

Put Real Numbers Behind The New Rules

Suppose a 17-year-old earns $15 an hour and works 12 hours each week, producing about $780 in gross monthly earnings before deductions in an average month. If the teen puts $150 toward gas, spends $100 going out, buys $75 worth of clothes and automatically saves $200, roughly $255 remains before taxes and other purchases. That teen’s first job is now teaching budgeting because the teenager must make tradeoffs, but it still leaves room to build savings instead of watching every paycheck disappear into expenses. The challenge of balancing social life and savings continues into young adulthood: Bank of America’s 2026 Better Money Habits study found that 75% of Gen Z adults look for ways to save when going out, while 40% had cut back on dining out. Parents can revisit their teen’s numbers every few months as wages, hours, school commitments and driving needs change rather than making one permanent rule after the first paycheck arrives.

Do Not Forget The Cost Of Going To Work

A hidden complication is that employment itself can cost money, particularly when a teenager needs transportation, uniforms, nonslip shoes, work-appropriate clothing or meals during a shift. If parents require teenagers to cover all those expenses immediately, they could spend a significant portion of their wages simply for the privilege of working. Consider separating “costs required to earn the paycheck” from discretionary spending, with parents helping more with the former while teens increasingly handle the latter. There is also evidence that young people value earning their own money: Greenlight’s 2025 Family Trends Report found that 90% of surveyed kids wanted to earn money rather than simply receive it. The goal of a teen’s first job should be to connect work with choices and consequences, not to make teenagers regret earning money because every dollar immediately becomes another obligation.

The Best Transition Is Gradual, Clear And Fair

A first paycheck should trigger a family conversation, not an overnight transfer of every expense from parent to teenager. Decide beforehand which necessities parents will continue covering, which optional expenses belong to the teen and whether larger costs such as gasoline or car insurance will be shared. Write the agreement down if necessary, especially when a teenager’s work hours vary during school, sports seasons or exam periods. The most useful outcome is not simply reducing the parents’ expenses; it is giving a young worker enough responsibility to practice budgeting while still having a realistic opportunity to save.

What would you expect your teenager to start paying for after getting their first paycheck—and which expenses would you continue covering? Share your approach in the comments.

What to Read Next

Should a Teen Pay Rent After Turning 18 if They Still Live at Home?

Your Teen’s First Job Could Change More Than Their Spending Money

Your Teen Works 15 Hours a Week: What Expenses Should Become Their Responsibility?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: family finances, financial literacy, first paycheck, parenting advice, parenting teenagers, Saving Money, teen budgeting, teen employment, teen finances, teen first job

Grandma Gave One Kid $1,000 and the Other $100: Should Parents Step In?

October 5, 2026 | Leave a Comment

Grandma And Granddaughter
A $1,000 gift for one grandchild and $100 for another can raise questions that go far beyond money. Understanding the reason for unequal gifts can help parents decide when to step in. (Pexels).

Grandma hands one grandchild an envelope containing $1,000 and the other gets $100, and suddenly what should have been a happy family moment feels painfully awkward. Unequal gifts to grandchildren can raise questions about favoritism, fairness, and whether parents should intervene in a grandparent’s financial choices. The answer is not automatically to demand equal checks, because there may be legitimate reasons behind the difference. But when money starts sending the message that one child matters more than another, parents have good reason to address what is happening.

Unequal Gifts Can Carry More Weight Than The Dollar Amount

Grandparents play a surprisingly large financial role in American families, making unequal gifts to grandchildren more consequential than an occasional birthday surprise. AARP’s 2026 grandparenting research found that 90% of grandparents provide financial support to grandchildren, collectively contributing more than $172 billion annually. Grandparents reported spending an average of $2,654 per year on all their grandchildren combined, while 69% also provide care. Those numbers show that grandparents often function as part of a family’s financial safety net, not simply as occasional gift-givers. When siblings can easily compare $100 with $1,000, however, parents should pay attention to both the money and the message children may take from it.

Fair Does Not Always Have To Mean Equal

Before confronting Grandma, parents should find out why the gifts differ because equal and fair are not always the same thing. Imagine a 17-year-old receives $1,000 specifically for a laptop needed for college while her 10-year-old brother receives $100 for his birthday; the $900 difference has a practical explanation rather than necessarily reflecting favoritism. A grandparent might similarly help one grandchild with tuition, medical expenses, transportation, or another major need while giving smaller discretionary gifts to siblings. AARP reports that 41% of grandparents provide financial assistance for grandchildren’s basic necessities, while 8% help with medical, dental, or mental health expenses. Parents should therefore ask what the gift is for before assuming unequal gifts to grandchildren automatically mean one child is being favored.

When Parents Should Speak Up

Parents have stronger grounds to intervene when unequal gifts to grandchildren repeatedly occur without a reasonable explanation or are openly tied to comparisons between siblings. Saying, “You get $1,000 because you’re the smart one,” for example, creates a problem far beyond the family budget because the gift effectively assigns value to the children themselves. A 2026 study indexed by PubMed examined 221 adult grandchildren from 81 families and found that perceptions of grandmothers’ differential treatment were common. Among granddaughters, perceiving themselves as the grandchild to whom Grandma was most emotionally close was associated with higher depressive symptoms, with qualitative findings pointing to emotional caregiving responsibilities as a possible explanation. The research does not prove that an unequal cash gift causes psychological harm, but it does provide a good reason not to dismiss family favoritism as harmless.

Parents Do Not Have To Match The Difference

One tempting response is for parents to give the child who received $100 another $900, but that can accidentally teach children that every financial difference must immediately be corrected. Instead, acknowledge the child’s feelings, explain any legitimate reason for the difference, and establish clearer expectations with Grandma before the next birthday or holiday. There is also a tax detail families may misunderstand: Fidelity reports that the annual federal gift-tax exclusion remains $19,000 per donor, per recipient in 2026, so neither a $1,000 nor a $100 gift approaches that amount. A married couple electing to split gifts could generally give $38,000 to one recipient in 2026 before beginning to use their lifetime federal gift and estate tax exclusion. That does not make a lopsided gift emotionally wise, but it shows why parents should separate questions about family fairness from questions about gift-tax rules.

Set Family Ground Rules Before The Next Envelope Appears

Parents cannot dictate how another adult spends every dollar, but they can set reasonable boundaries around how their children are treated. If unequal gifts to grandchildren are likely to continue, parents might ask that substantial gifts be discussed beforehand or given privately when they address genuinely different needs. Families can also distinguish “celebration money,” where roughly comparable gifts may prevent unnecessary hurt, from “need-based help,” where different amounts are easier to explain. Avoid making the child who received more surrender part of the gift, because that places responsibility for an adult decision on the siblings. The goal should be transparency and respect rather than maintaining a lifetime spreadsheet in which every grandchild must receive precisely the same dollar amount.

Protect The Relationship, Not Just The Balance Sheet

A $900 difference is worth discussing, but the bigger question is what that difference communicates inside the family. Unequal gifts to grandchildren can be reasonable when they reflect different ages, expenses, milestones, or genuine needs, yet repeated unexplained favoritism deserves parental attention. Talk privately with Grandma, establish expectations before future gifts, and give children an age-appropriate explanation rather than allowing resentment to supply its own story. Parents should protect sibling relationships without turning every financial decision into a mathematical equality test.

If one grandchild in your family received $1,000 while another received $100, would you let Grandma decide how to spend her money or ask her to treat the children more equally? Share your thoughts in the comments.

What to Read Next

10 Baby Names Parents Love but Grandparents May Need Time to Get Used To

Should Grandparents Be Expected to Help Pay for Kids’ Activities?

8 Things Grandparents Buy Kids That Parents Secretly Wish They Wouldn’t

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: family finances, family relationships, favoritism, financial planning, grandchildren, grandparents, money gifts, Parenting

A Child With Disabilities Turns 18 — These Financial Decisions Can Change Overnight

October 4, 2026 | Leave a Comment

Young Man With Down Syndrome
Turning 18 can change benefit eligibility, financial decision-making authority and the way savings affect a young adult with disabilities. Families can prepare by reviewing SSI, ABLE accounts, trusts and legal documents before the birthday arrives. (Pexels).

A child’s 18th birthday is usually celebrated as a milestone toward independence, but for families raising a child with disabilities, it can also trigger major financial and legal changes. Benefits that once depended partly on the parents’ finances may suddenly be evaluated differently, while parents can lose their automatic authority to handle important matters. Savings, inheritances and even well-intentioned gifts can also create unexpected complications. That is why disability financial planning deserves attention before the candles are blown out.

SSI Eligibility Can Change At Age 18

One of the biggest changes involves Supplemental Security Income, commonly known as SSI, because parental income and resources generally stop being considered once a child reaches adulthood. The Special Needs Alliance explains that an adult who was previously ineligible because of parental finances may qualify after turning 18. The maximum federal SSI benefit is $994 per month in 2026, although income and other circumstances can reduce the actual payment. Someone who received SSI as a child also faces an age-18 disability redetermination under the adult disability standard, so families should not assume benefits will automatically continue. Disability financial planning around this birthday should therefore include a fresh look at eligibility, resources and household financial support.

Parents May Lose Automatic Decision-Making Authority

Turning 18 also changes who has legal authority over many personal and financial decisions because an adult is generally presumed capable of making their own choices. Parents who previously scheduled appointments, dealt with institutions or managed financial matters may discover that being a caregiver does not automatically give them continuing legal authority. Depending on the person’s needs and applicable state law, families may consider tools such as powers of attorney, health care proxies, supported decision-making or guardianship. The Special Needs Alliance provides resources addressing what happens at 18 and alternatives families can explore. Because guardianship can substantially restrict an adult’s rights, families should investigate whether a less restrictive arrangement can provide adequate support.

A $10,000 Gift Could Create A Serious Problem

Money given directly to a young adult receiving means-tested benefits can have consequences relatives never intended. Nolo explains that directly leaving property to someone receiving SSI and Medicaid can jeopardize eligibility, while appropriately structured special needs trusts can help protect those benefits. Consider grandparents who leave their grandchild $10,000 in a will, believing they are providing a helpful emergency fund when the SSI countable-resource limit for an individual is generally just $2,000. Effective disability financial planning therefore includes reviewing wills, life insurance beneficiaries and other accounts instead of focusing only on the parents’ estate plan. Before relatives make large gifts, families should understand whether an ABLE account or properly designed special needs trust is more appropriate.

ABLE Accounts Expanded In 2026

ABLE accounts can allow eligible people with disabilities to save money for qualified disability expenses without every dollar being treated like money in an ordinary savings account. Beginning in 2026, eligibility expanded so the disability must have begun before age 46, compared with the previous requirement that onset occur before age 26, according to the ABLE National Resource Center. The standard 2026 ABLE contribution limit is $20,000, giving families significantly more room to save while preserving important protections. An eligible account owner who works and does not participate in an employer-sponsored retirement plan can potentially contribute an additional $15,650 in the continental United States, or employment earnings if lower. These updated limits make ABLE accounts increasingly useful in disability financial planning, but families should still compare program fees, investment choices and state-specific benefits.

The $100,000 Rule Has An Important Catch

One detail families may overlook is that ABLE accounts interact differently with SSI once balances become substantial. Fidelity explains that an ABLE balance above $100,000 can cause SSI cash benefits to be suspended until the relevant balance falls back within the permitted level. That does not mean an ABLE account should simply replace a special needs trust, particularly when parents or grandparents expect to leave a large inheritance. Another significant tradeoff is that a state may seek Medicaid reimbursement from remaining ABLE assets after the beneficiary dies under applicable rules. Families expecting to transfer substantial assets should discuss the differences between ABLE accounts and first- and third-party special needs trusts with professionals experienced in special needs planning.

Make The 18th Birthday A Financial Checkpoint

The most useful approach is to treat turning 18 as a financial checkpoint rather than waiting until a benefit, inheritance or medical decision creates a crisis. Review SSI and Medicaid eligibility, bank balances, ABLE accounts, estate documents, beneficiary designations and who has legal authority to provide necessary assistance. Ask what would happen if the young adult inherited $25,000 tomorrow, started earning wages or needed someone else to communicate with financial or medical institutions. Strong disability financial planning can protect valuable benefits while still respecting the young adult’s independence and individual abilities.

Which financial change at age 18 do you think families are least prepared for? Share your thoughts or experience in the comments.

What to Read Next

What Changes for Your Child’s IEP When They Turn 18

Should You Tell Siblings They May Have a Role in Their Disabled Brother or Sister’s Future?

6 Free Reading Resources for Children With Print Disabilities

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: ABLE accounts, disability benefits, disability financial planning, family finances, financial planning, Medicaid, special needs planning, special needs trust, SSI benefits, turning 18

What Does a 5-Year-Old Cost a Family Each Month?

October 4, 2026 | Leave a Comment

Young Girl
Even after a child starts kindergarten, food, after-school care, health expenses, clothing, and school costs can keep monthly spending surprisingly high. Child care arrangements can make one of the biggest differences in what families actually pay. (Pexels).

By age 5, parents may expect the financial pressure of the toddler years to ease, especially when kindergarten replaces full-time day care. Yet the monthly cost of a 5-year-old can still surprise families once food, health insurance, clothes, transportation, school expenses, and child care are counted. The total also varies enormously depending on where a family lives and whether parents need care outside school hours. Instead of searching for one magic number, parents should identify which expenses actually change because their 5-year-old is in the household.

The National Numbers Need Some Context

A 2026 LendingTree analysis estimated the annual cost during a child’s first five years at $29,325, or roughly $2,444 per month, based primarily on 2024 data. That calculation includes housing, food, day care, clothing, transportation, and insurance, minus applicable tax benefits, so it should not be interpreted as what every parent will spend on a 5-year-old. Full-time child care alone makes the early-years figure considerably higher than what some kindergarten families experience. The same analysis estimated $4,208 annually for food and $4,422 for transportation attributable to a young child. Consequently, a practical monthly cost of a 5-year-old could be far below $2,444 for a family using public kindergarten and little paid child care.

Child Care Can Still Dominate The Budget

Kindergarten may eliminate a day-care bill, but it does not necessarily cover a parent’s entire workday, school holidays, or summer vacation. Child Care Aware of America reported that the national average annual price of child care reached $13,184 in 2025, while center-based care for a 4-year-old averaged roughly $12,000 to $12,500 under two of its calculation methods. For school-age families, before-school programs, after-school programs, and summer camps can replace part of that expense rather than eliminating it. Care.com’s 2026 Cost of Care Report found an average posted rate of $328 per week for an after-school sitter covering 15 hours. Parents comparing programs should ask whether quoted prices include registration fees, school-closure days, meals, transportation, and summer coverage.

Food, Clothes And School Costs Add Up

Food is one of the more predictable pieces of the monthly cost of a 5-year-old, although school meals can change the calculation. The American Academy of Pediatrics notes through HealthyChildren.org that children consume a significant share of their daily calories during school hours, making school meal options worth investigating. Beyond groceries, families may need shoes, rapidly replaced clothing, backpacks, classroom supplies, birthday gifts, field-trip money, and activity fees. These expenses rarely arrive in identical amounts every month, which makes them easy to underestimate. Setting aside a fixed monthly amount for irregular child expenses can prevent new shoes, a school fundraiser, and soccer registration from unexpectedly hitting the same paycheck.

Health Care Is The Expense Parents Shouldn’t Overlook

Health insurance is another reason the monthly cost of a 5-year-old cannot be reduced to groceries and school supplies. According to KFF’s 2025 Employer Health Benefits Survey, workers with employer-sponsored family coverage contributed an average of $6,850 annually, or about $571 per month, toward family premiums. That $571 should not simply be assigned to one child because it covers the family, but parents can compare their employee-only premium with their actual family premium to better understand the additional household cost. Deductibles, copays, prescriptions, dental visits, and glasses can create additional out-of-pocket spending that premiums do not capture. Reviewing several months of medical spending gives families a more realistic figure than simply dividing the entire family insurance bill by the number of household members.

What A Realistic Monthly Budget Might Look Like

Consider a family whose 5-year-old attends public kindergarten and does not require paid after-school care. They might budget $350 for additional groceries and school meals, $40 for clothing, $150 for transportation, $75 for activities, $50 for school and miscellaneous expenses, and $150 for the child’s incremental health-related costs. That produces an illustrative monthly cost of a 5-year-old of about $815, before any additional housing cost or paid child care. Add several hundred dollars for an after-school program—or substantially more for regular sitter care—and the monthly total can quickly climb past $1,000. The lesson is that child care, housing, and insurance arrangements often move the budget more than toys or occasional treats do.

Build Your Number Instead Of Trusting An Average

The most useful way to calculate the monthly cost of a 5-year-old is to review actual household spending and separate truly additional costs from bills the family would pay anyway. Start with child care, food, insurance, transportation, clothing, and school expenses, then add one-twelfth of annual costs such as camps, sports registrations, birthdays, and back-to-school purchases. Families can save by comparing after-school programs before hiring individual care, using school meal options when appropriate, buying children’s clothing secondhand, and creating a sinking fund for summer care. Most importantly, do not assume kindergarten automatically makes age 5 inexpensive, because shorter school days and long summer breaks can create a hidden child-care gap.

What expense has surprised you most about raising a 5-year-old, and how are you keeping it under control? Share your experience in the comments.

What to Read Next

Free Library Benefits That Replace Costly Children’s Activities

8 Hidden Costs Parents of Children With Autism Say Nobody Warned Them About

Unplanned Children: Here’s What That Unexpected Child Is Going To Cost You

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: 5-year-old expenses, child care costs, cost of raising a child, Family Budget, family finances, grocery costs, Kindergarten, Parenting, parenting costs, Saving Money

12 “Grandma” Baby Names That Are Suddenly Cool Again

October 3, 2026 | Leave a Comment

Baby Girl
Names once associated with grandmothers are finding new life in nurseries, with Evelyn and Eleanor now among America’s most popular choices. Less common throwbacks such as Mabel, Vera and Edith offer parents a more distinctive route. (Pexels).

Baby names have a funny way of coming full circle, and choices once associated with grandmothers are appearing on birth announcements again. Parents are rediscovering vintage baby names that feel familiar, substantial and refreshingly different from newly invented choices. The trend is visible in current data, with names including Evelyn and Eleanor sitting surprisingly high on national popularity lists. At the same time, less common throwbacks give families a way to embrace nostalgia without choosing another Top 10 name. Here are 12 old-school choices proving that yesterday’s “grandma name” can sound remarkably fresh today.

1. Evelyn Is No Longer Just Vintage

Evelyn has moved well beyond the antique-name category and into the mainstream. In 2025, it ranked No. 8 nationally, with 9,123 girls receiving the name, according to NameAlmanac. That puts Evelyn alongside some of the most familiar names parents are choosing today. Nicknames such as Evie and Eve also let families give the traditional name a lighter everyday sound. Parents who want something unusual, however, should realize Evelyn is now far from rare.

2. Eleanor Keeps Moving Up

Eleanor offers history along with several modern-sounding nicknames, including Ellie, Ella and Nora. The name climbed from No. 14 in 2024 to No. 12 in 2025. Babylist also identified Eleanor among the girls’ names showing upward momentum in its 2025 baby-name analysis. That makes Eleanor a good example of how vintage baby names can return without losing their traditional character. Families should remember that its growing popularity could mean meeting another Eleanor at daycare or school.

3. Hazel Has Completed A Remarkable Comeback

Hazel once sounded unmistakably like a name from another generation. Today, its short sound and nature connection fit easily beside choices such as Ivy, Willow and Violet. Hazel ranked No. 21 among U.S. girls’ names in 2025. A century earlier, it was also familiar, ranking No. 34 in 1920. That kind of staying power shows why certain vintage baby names can successfully cross generations.

4. Josephine Gives Parents Options

Josephine works especially well for parents who love formal names but want nickname flexibility. Josie feels playful, while Jo or Joey gives the same name an entirely different personality. Josephine ranked No. 53 in 2025, placing it comfortably inside the Top 100. The full version still has the elegance people associate with an earlier era. Before choosing it, parents should consider whether they would be equally happy if relatives naturally shortened the name.

5. Clara Feels Surprisingly Modern

Clara demonstrates how simplicity can help an old name feel new again. It ranked No. 44 back in 1920 but stood at No. 63 in 2025. Nameberry’s updated collection of old-lady names specifically discusses whether stylish choices such as Clara even qualify as “old lady” names anymore. Its two syllables also make Clara straightforward to say and spell. That practicality matters when a child will repeat and write the name thousands of times throughout life.

6. Ruby Has Its Sparkle Back

Ruby combines an unmistakably vintage sound with the familiarity of a gemstone name. It ranked No. 26 in 1920 and remained popular enough to reach No. 64 in 2025. Unlike some elaborate Victorian choices, Ruby is short and requires no obvious nickname. It also fits naturally alongside contemporary nature and jewel-inspired names. Parents considering vintage baby names may find Ruby hits a comfortable middle ground between distinctive and recognizable.

7. Alice Has Lasted For Generations

Alice is less a forgotten name than a classic that keeps finding new audiences. It ranked No. 15 in 1920, when 11,596 girls received the name, according to historical naming data. In 2025, Alice remained firmly in use at No. 65. The name is familiar enough that spelling and pronunciation are unlikely to create much confusion. Yet it still carries the storybook quality many parents want from an older name.

8. Mabel Is Becoming Less Dusty

Mabel once sounded like the definition of a grandma name, but that perception is changing. The name rose 21 positions in 2025 to No. 201 among girls, according to The Bump’s Mabel popularity data. That ranking makes it considerably less common than Evelyn, Eleanor or Hazel. Parents can also use Mae as a natural nickname. Mabel is worth considering for families who want vintage style without choosing a name already near the top of the charts.

9. Vera Packs History Into Four Letters

Vera is short, recognizable and still relatively uncommon. It ranked No. 205 among girls in 2025, giving it substantially more breathing room than many revived classics. The name also works without requiring a nickname or unusual spelling. That simplicity can be useful when parents want something distinctive without creating constant pronunciation corrections. Vera shows that vintage baby names do not need to be long or elaborate.

10. Dorothy Could Be Ready For Rediscovery

Dorothy provides a striking example of how dramatically naming fashions can change. It was the No. 2 girls’ name in 1920, with 36,643 births recorded that year. Today it is far less common, making its instantly recognizable sound somewhat deceptive. Nicknames Dot and Dottie can also make Dorothy feel more playful. Parents looking beyond already-popular revival names may find that contrast especially appealing.

11. Florence Offers Serious Old-School Style

Florence was once everywhere, ranking No. 16 in 1920 with 10,731 births. Today, that history can make the name feel distinctive rather than ordinary. Flo, Florrie and Flora offer possible alternatives for everyday use. The tradeoff is that Florence has a stronger antique character than relatively mainstream choices such as Alice or Evelyn. Families should say the full first, middle and last name aloud before deciding whether that formality works for them.

12. Edith May Be Ready For Another Turn

Edith ranked No. 32 in 1920, when 7,773 girls received the name. A century later, its old-fashioned character is exactly what may appeal to parents searching beyond current favorites. Edie also provides a breezier nickname that feels less formal. Choosing Edith before any larger revival could appeal to families who value recognizable but uncommon vintage baby names. As with every revival choice, the real test is whether parents love the name itself rather than simply the trend.

Yesterday’s Names Are Finding New Families

The comeback of vintage baby names shows that “old-fashioned” is often only a temporary label. Some former grandma names, particularly Evelyn and Eleanor, have already become mainstream choices, while Dorothy, Vera and Edith remain much less expected. Parents should check current rankings, consider likely nicknames and test how a name sounds with their surname before committing. A family name can also add personal meaning that no popularity chart can measure.

Which grandma-style baby name deserves another generation, and which one should stay in the family scrapbook? Share your pick in the comments.

What to Read Next

10 Baby Names Everyone Thought Were Gone for Good — But Parents Are Bringing Them Back

The Babysitter Wants $25 an Hour: Is That Really the Going Rate Now?

9 Baby Names That Sound Rare Without Being Hard to Spell

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: baby name trends, baby names, girl names, grandma baby names, old-fashioned baby names, Parenting, Pregnancy, vintage baby names

Should a Teen Pay Rent After Turning 18 if They Still Live at Home?

October 3, 2026 | Leave a Comment

Working Teen
Turning 18 does not automatically mean a young adult is financially ready to leave home. A reasonable household contribution can teach budgeting while still giving teens room to save for college, emergencies, and eventual independence. (Pexels).

Turning 18 makes a teenager a legal adult, but it does not automatically make them financially independent. With housing, education, groceries, transportation, and insurance taking sizable bites out of young workers’ paychecks, many families are reconsidering what adulthood at home should look like. Recent research from Pew Research Center found that 57% of 18-to-24-year-olds live with a parent, so remaining home after high school is hardly unusual. The debate over whether a teen should pay rent after 18 is really about balancing responsibility with the opportunity to build a financial foundation. For many households, the best solution may fall somewhere between completely free housing and charging market-rate rent.

Living At Home Is Increasingly An Economic Strategy

High housing costs make living with parents a practical decision for many young adults rather than evidence that someone is refusing to grow up. A July 2026 analysis from the Urban Institute found that about 20% of Americans ages 25 to 34 live with their parents, nearly double the 11.8% recorded in 2005. Researchers also found that young adults are more likely to remain home in metropolitan areas with higher rents, even across different income levels. That matters when deciding whether a teen should pay rent after 18 because moving out prematurely can replace inexpensive family housing with rent, utilities, deposits, furniture, and other costs. Parents should therefore consider whether charging rent advances their child’s independence or simply makes saving enough to leave home harder.

A Contribution Does Not Have To Mean Market Rent

Parents who expect some financial participation are far from unusual, but writing a monthly rent check is only one option. Pew found that 72% of young adults living with parents contribute financially to their household, including 65% who help with groceries or utilities and 46% who contribute toward rent or the mortgage. A teenager earning $1,800 a month after taxes, for example, might pay $250 toward household expenses while putting $500 into savings and covering transportation and personal bills. That approach gives the young adult experience managing recurring obligations without consuming such a large percentage of income that saving becomes impossible. Families deciding whether a teen should pay rent after 18 should look at actual income and expenses instead of choosing an arbitrary amount.

Parents Should Protect Their Own Finances Too

Free housing can be generous, but parents should not provide it by jeopardizing retirement, emergency savings, or debt repayment. A Bankrate survey found that 61% of parents with adult children had made financial sacrifices to help them, including 37% who reported sacrificing retirement savings. That is an important hidden cost because parents approaching retirement have fewer working years available to rebuild depleted accounts. If another adult increases grocery, utility, insurance, transportation, or household costs by several hundred dollars monthly, requesting a reasonable contribution may protect the entire family. Before setting rent, parents should calculate what their adult child actually costs the household rather than treating the payment as punishment for reaching a birthday.

College And Early Careers Change The Equation

An 18-year-old attending school full time is in a different financial position from a 19-year-old working 40 hours a week with few personal expenses. The College Board reports average published in-state tuition and fees at public four-year colleges reached $11,950 for 2025-26, while public two-year in-district tuition averaged $4,150. Those figures exclude many everyday expenses, meaning charging substantial rent could force a student to work additional hours or borrow more money. Families might instead require smaller contributions, household chores, or measurable savings while the student remains enrolled and progressing toward a degree or credential. Whether a teen should pay rent after 18 should therefore depend partly on what that young person is actively doing to become self-supporting.

The Rent Can Become A Forced-Savings Tool

Parents who do not need their child’s contribution have another option: charge rent but quietly save some or all of it for the child’s future. For example, collecting $300 monthly for two years would produce $7,200 before any interest, potentially helping with a security deposit, emergency fund, reliable vehicle, or other move-out costs. The arrangement still teaches that housing carries a monthly cost while preventing the money from disappearing into everyday spending. Parents should decide beforehand whether they will eventually return the money and whether telling their child about the plan would undermine its budgeting lesson. Whatever approach is chosen, the amount, payment date, chores, savings expectations, guests, and target for eventual independence should be discussed clearly.

The Goal Should Be Independence, Not A Rent Check

There is no universal amount every family should charge when deciding whether a teen should pay rent after 18. A reasonable arrangement should reflect the young adult’s income, education plans, household costs, savings goals, and the parents’ financial situation rather than relying on age alone. Charging modest rent can teach budgeting and protect parents financially, while reduced or free rent can be equally productive when it allows a responsible young adult to finish school, eliminate debt, or accumulate meaningful savings. The strongest arrangement is one with a purpose, measurable expectations, and regular conversations about what comes next.

Would charging your 18-year-old rent prepare them for independence, or would helping them save that same money give them a stronger start—what would you do in your household? Share your thoughts in the comments.

What to Read Next

Living Alone and Working from Home? Here’s How to Stay Social

Should Parents Charge Adult Kids Rent When They Move Back Home?

Would You Charge Your Adult Child Rent If They Moved Back Home?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: adult children, budgeting, Cost of Living, family finances, financial independence, Parenting, personal finance, rent, Saving Money, teenagers

At What Age Should Kids Know the Family Is Struggling Financially?

October 2, 2026 | Leave a Comment

Mom And Daughter
Age-appropriate conversations about family financial struggles can help children understand changing budgets without making them responsible for adult money problems. Younger kids need simple explanations, while teenagers can handle more detail about household tradeoffs and financial planning. (Pexels).

Kids often notice family financial struggles long before parents officially explain them. They hear conversations about bills, notice when restaurant dinners disappear, or wonder why a planned vacation suddenly gets canceled. The challenge for parents is deciding how much honesty is appropriate without making children feel responsible for fixing an adult problem. There is no universal “right age,” but child-development experts suggest gradually increasing financial transparency as children become capable of understanding budgets, tradeoffs, and consequences.

Start With Simple Money Lessons In Elementary School

Children do not need a detailed explanation of credit-card balances or overdue bills to understand that money has limits. The Child Mind Institute says most children have enough math skills by second or third grade to begin learning about money, budgeting, saving, and spending decisions. For a 7-year-old, explaining family financial struggles might mean saying, “We’re spending less right now, so we’re cooking at home instead of ordering pizza.” That provides an honest explanation without making the child wonder whether the family will lose its home. Parents can also involve younger children in low-stakes decisions, such as comparing grocery prices or choosing between two affordable activities.

Give Tweens More Context Without Giving Them Your Anxiety

By roughly ages 10 to 12, many children can understand that household income must cover housing, food, transportation, utilities, and other necessities before extras. This is a reasonable stage to explain that family financial struggles sometimes require temporary changes, such as postponing a vacation or buying fewer new clothes. The American Academy of Pediatrics’ HealthyChildren.org recommends teaching children to divide money among saving, spending, and sharing, helping them understand that financial choices involve priorities. Parents should still avoid unloading fears such as, “I don’t know how we’ll survive if I lose my job.” A better message is specific but reassuring: “Money is tighter this year, so we have a plan to spend less.”

Teenagers Can Handle More Of The Real Numbers

Teenagers generally need more financial information because family finances increasingly affect decisions they participate in, from driving and extracurricular activities to college planning. Consider a household that previously spent $300 monthly on entertainment but must cut that amount to $100 after a parent’s hours are reduced; showing a teenager that $200 tradeoff can make the situation concrete without handing them the entire household ledger. Financial pressure is hardly unusual: an April 2026 LendingTree survey found 82% of parents said raising children had become more expensive over the previous year, while 64% said they had gone into debt to cover child-related costs. Discussing family financial struggles honestly can therefore teach teenagers that changing spending habits is a practical response rather than something shameful. Older teens can even help identify discretionary expenses, provided parents make clear that paying household bills remains the adults’ responsibility.

The Hidden Risk Is Making Kids Feel Responsible

The biggest issue may not be whether children know money is tight, but whether they start believing they must rescue the family. Research published in the Maternal and Child Health Journal in 2025 found that 55% of low-income families with young children in its study showed profiles involving medium-to-high levels of family stressors, highlighting how economic pressure can extend beyond the bank account. That is why statements such as “We can’t afford anything because you kids cost so much” can be especially damaging and should be avoided. Instead, parents can frame family financial struggles around choices and plans: “We’re cutting expenses while we rebuild our savings.” Children should understand the reality affecting their lives without becoming emotional partners in managing debt, job insecurity, or marital disagreements about money.

Financial Pressure Is More Common Than Children May Realize

Parents may also worry that acknowledging money problems will make their family seem unusually unsuccessful, but recent numbers provide important perspective. Bankrate’s 2026 Emergency Savings Report found 29% of U.S. adults had more credit-card debt than emergency savings, while 58% said their emergency savings were the same as or lower than a year earlier. Meanwhile, 85% said they would need at least three months of expenses saved to feel comfortable, yet only 46% actually had that much. Those numbers can help older teens understand why an unexpected $1,500 car repair can force an otherwise responsible family to change its budget quickly. The lesson is not that financial hardship is inevitable, but that emergency savings, controlled spending, and honest planning matter.

Kids Need Honesty Without Carrying The Burden

Children should gradually learn about money from elementary school onward, while detailed conversations about genuine financial hardship should expand as they mature. Parents do not need to reveal every debt balance, collection notice, or fear simply to be truthful. Instead, explain what is changing, why reasonable spending limits exist, and what the adults are doing about the situation. That approach gives children useful financial knowledge while preserving the sense of security they still need from their parents.

At what age did you first realize your family was struggling financially, and do you think your parents handled that conversation well? Share your experience in the comments.

What to Read Next

Why Children With Autism Often Struggle With Summer Transitions

The Truth About Teen Finances: 10 Money Habits Parents Are Teaching Kids That Keep Them Poor

How to Raise a Resilient Kid—Even If You’re Struggling Yourself

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: Family Budgeting, family finances, financial literacy, financial stress, kids and money, Parenting, parenting advice, Saving Money

Next Page »
  • Facebook
  • Pinterest
  • RSS
  • Twitter
Best Parenting Blogs

Most Popular

Baby

9 Unusual Baby Names That Sound Like They Belong to Future CEOs

Evan Morgan
Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Target Store

Choking Incident Prompts Recall of 49,000 Target Gigglescape “Under the Sea” Popping Toys

Evan Morgan
Frustrated Girl

Why Some Students on the Spectrum Are Labeled With ODD

Evan Morgan
Coke Bottles

12 Things Kids Took to School in the ’70s That Would Never Be Allowed Today

Evan Morgan

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette