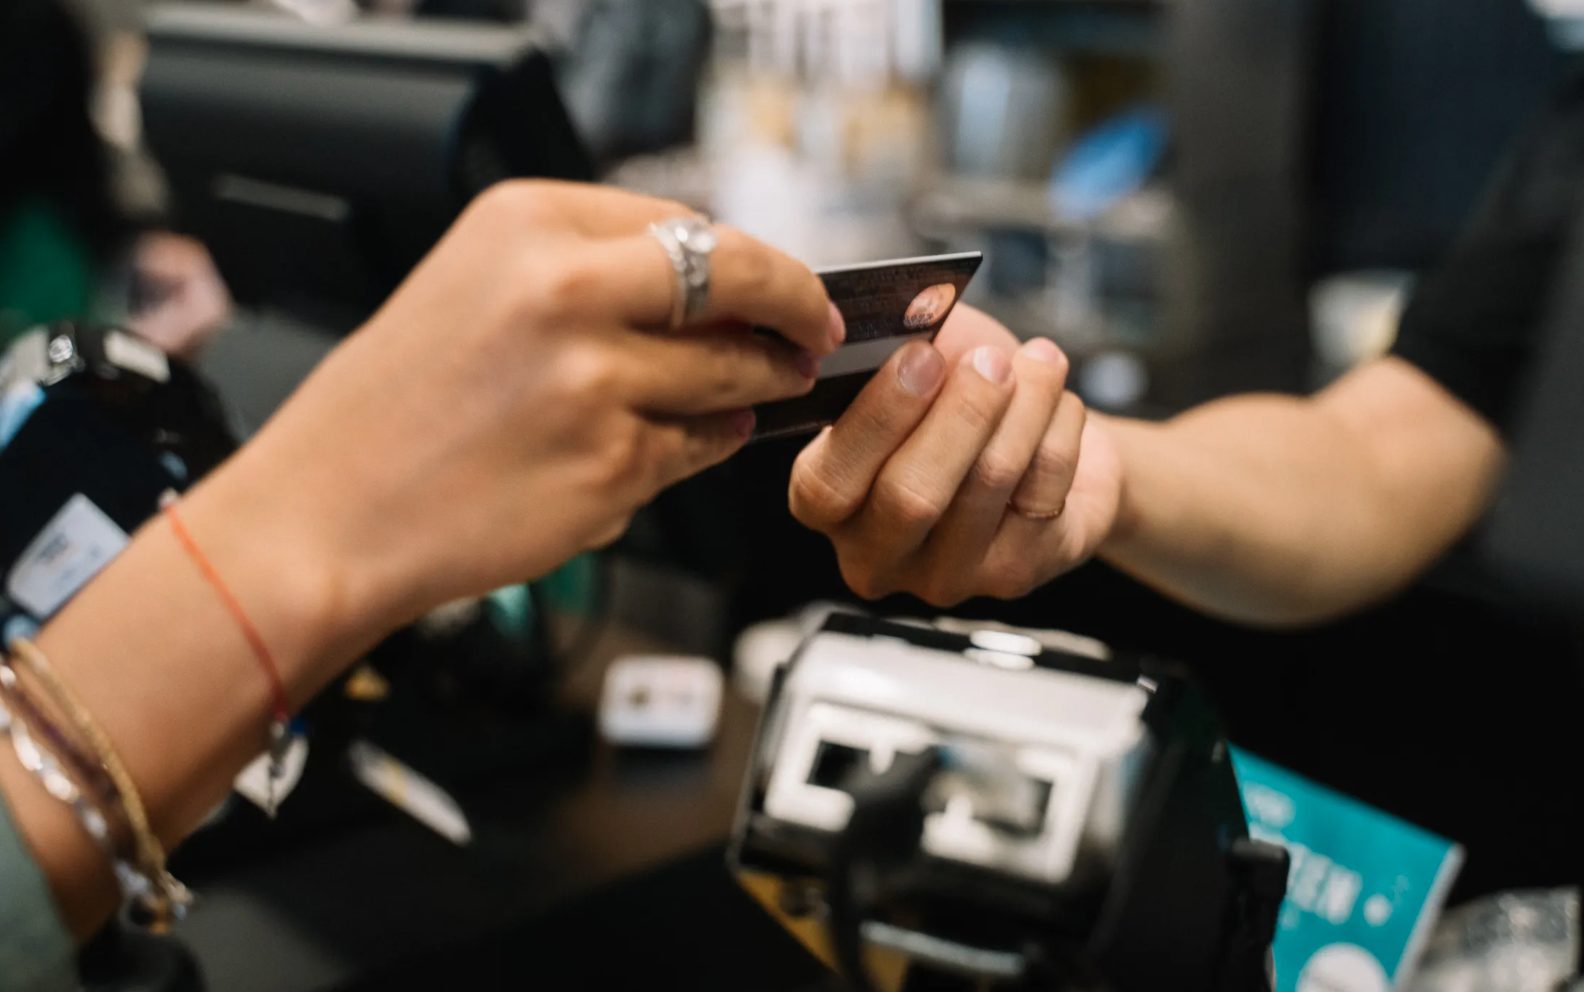
Handing your teenager a debit card can feel like a small step, but it changes how quickly money can disappear. A teen debit card gives young people independence while giving parents an opportunity to teach budgeting, fraud awareness, and responsible spending before larger financial decisions arrive. Those lessons matter in an increasingly cash-light world, where tapping a phone or card can make a $20 purchase feel less tangible than handing over a $20 bill. Before activating the card, families should agree on rules that make everyday purchases teachable rather than stressful.
Decide What The Card Can Actually Pay For
Start by defining which expenses your teen owns and which remain the parents’ responsibility. Lunch with friends, gaming purchases, gas, clothing, and school expenses can quickly blur together unless everyone understands the boundaries. A practical rule might be that parents cover necessary school supplies while entertainment and restaurant purchases come from the teen’s personal balance. That distinction matters because Greenlight’s 2025 Family Trends Report found that 92% of surveyed kids said they regretted impulse purchases, showing that buyer’s remorse can become a useful financial lesson. A teen debit card works best when running out of spending money has a predictable consequence rather than automatically triggering a parental bailout.
Create A Spending Limit Before Money Hits The Account
Giving a teenager access to $300 does not necessarily mean allowing $300 of discretionary spending. Consider dividing incoming money among spending, short-term savings, and a longer-term goal, with percentages adjusted to your family’s circumstances. For example, a teen earning $200 from a weekend job might put $50 toward a car fund, $30 into emergency savings, and have $120 available for current spending. Schwab’s 2026 Teen Investing Survey found that 65% of parents and 50% of teens ranked money management or financial education among the three most important subjects to learn in school. A teen debit card can turn that education into real practice because each purchase forces a choice between spending today and keeping money for tomorrow.
Make Balance Checks Part Of The Routine
One of the easiest mistakes is assuming the number shown in an account always represents money available for guilt-free spending. Pending restaurant tips, subscriptions, and other transactions can complicate the picture, so teens should learn to review recent activity rather than rely solely on memory. NerdWallet recommends looking for teen accounts with reasonable spending controls and notes that some accounts let parents restrict ATM withdrawals, transfers, or debit-card spending. Consider requiring a quick balance check before purchases above an agreed amount, such as $25 or $50. That simple habit can make a teen debit card a budgeting tool instead of merely a more convenient way to spend.
Know What Happens When The Balance Hits Zero
Parents should understand an account’s overdraft rules before their teenager learns about them through an unpleasant surprise. Some institutions decline debit purchases when there is insufficient money, while account structures and overdraft options vary, making the fine print worth reading. Parents should ask whether the account can become overdrawn, whether another account is linked as backup, and whether any fees can be charged. Also check monthly charges and ATM costs because seemingly small recurring fees can eat into a teenager’s limited balance; Fidelity, for example, currently advertises its Youth Account for ages 13–17 with no subscription fees, account fees, or opening minimum. A declined $12 purchase can be a far cheaper lesson than repeatedly covering overspending without discussing what happened.
Establish Security Rules Before The Card Goes Missing
Teenagers need to know immediately what to do if their card disappears or an unfamiliar charge appears. Set a rule that a missing card gets reported to a parent and locked through the banking app as soon as possible, rather than waiting several days hoping it turns up. Teach teens never to share a PIN, send card information through messages, or approve unexpected requests for account credentials or verification codes. Parents should also activate transaction and low-balance alerts when available so suspicious purchases or rapid spending are easier to spot. Experian notes that most debit-card activity is not reported to the major credit bureaus, so parents should also explain that responsible use builds money-management skills but generally does not build a teen’s credit history.
The Bigger Goal Is Independence, Not Perfect Spending
A teen debit card should provide enough freedom for a teenager to make decisions, including an occasional inexpensive mistake, without putting significant family money at risk. Greenlight reported that its young users transferred $66 million among kids and friends in 2025, illustrating how routine digital money movement has become for many young consumers using its platform. Parents can use monthly account reviews to discuss unexpected purchases, subscriptions, savings progress, and what the teen would do differently next month rather than scrutinizing every snack purchase. The goal is not to raise a teenager who never wastes $15; it is to raise a young adult who understands why that $15 mattered and can make a better choice next time.
What debit-card rule would you insist on before giving your teenager financial freedom, and which mistakes should teens be allowed to learn from themselves? Share your thoughts in the comments.
What to Read Next
Your Teen’s First Job Could Change More Than Their Spending Money
Your Teen Works 15 Hours a Week: What Expenses Should Become Their Responsibility?
6 Money Rules Every Family Should Set Before a Teen Starts Driving

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Read More
Image Source: 123rf.com Raising a teenage son comes with its challenges, but one of the…

Parenting styles evolve over time, yet some approaches from the Baby Boomer era have stood…
Parents often rely on the same familiar question after school, but many child development specialists…
Image Source: 123rf.com Children don’t always come right out and say what’s on their minds.…

Credit scores have gotten more attention this week thanks to the news of a data…

You may be watching your child’s screen time, but are you watching who’s watching them?…


Leave a Reply