• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

One Parent Quits Working to Avoid Daycare: Does the Family Actually Save Money?

October 10, 2026 | Leave a Comment

Mother And Daughter At Home
With daycare expenses potentially exceeding $30,000 annually for two children, some parents are considering leaving their jobs to save money. However, lost wages, employer benefits, and retirement contributions can make staying home more expensive than expected. (Pexels).

Daycare costs have become so expensive that some American families are questioning whether having two working parents makes financial sense. When childcare bills rival mortgage payments, quitting a job to stay home can seem like an obvious money-saving decision. However, the financial reality is more complicated than simply eliminating a daycare payment. Before making that decision, families need to understand the hidden costs of becoming a single-income household.

Daycare Costs Are Taking A Bigger Bite Out Of Family Budgets

According to Child Care Aware of America’s 2026 report, the national average annual childcare price reached $13,184 in 2025. That represents approximately 10% of the median income for two-parent households, although actual expenses vary considerably by location. Meanwhile, Care.com’s 2026 Cost of Care Report found average advertised daycare prices of $332 weekly for one infant and $585 for two children. At those rates, two children could cost approximately $30,420 annually, assuming 52 weeks of paid care. For families earning modest salaries, these expenses can make leaving the workforce appear financially attractive.

The Salary You Lose Matters More Than The Daycare Bill

Consider a hypothetical family where one parent earns $45,000 annually and pays $18,000 for daycare. After approximately $9,000 in combined income and payroll taxes, that parent brings home $36,000 before childcare expenses. Subtract daycare, and the household still retains approximately $18,000 annually from that income, before other work-related expenses. Quitting would eliminate the childcare bill but also sacrifice that remaining income. Families considering childcare savings should compare actual take-home pay against avoidable expenses rather than comparing daycare costs with gross salary.

Quitting Could Mean Losing Thousands In Employee Benefits

A paycheck represents only part of what an employee receives from working. According to KFF’s 2025 Employer Health Benefits Survey, average employer-sponsored family health insurance premiums reached $26,993 annually, with employees contributing $6,850. Losing employer coverage could increase household insurance expenses, depending on the other parent’s available benefits. Families must also consider disability coverage, paid leave, and retirement contributions that disappear when employment ends. Before resigning, request a complete benefits summary and calculate what replacing essential coverage would actually cost.

Retirement Savings Could Become The Biggest Hidden Expense

Leaving the workforce temporarily can create financial consequences that continue long after children enter school. Fidelity’s retirement analysis reports that employers contribute an average of 4.8% of employee pay to retirement accounts, including matching and nonmatching contributions. For someone earning $45,000, that percentage represents approximately $2,160 annually in employer retirement contributions. Five years away from employment could mean losing $10,800 in contributions alone, excluding potential investment growth. Families should consider funding a spousal IRA when eligible and reviewing retirement contributions before deciding that staying home delivers meaningful childcare savings.

Staying Home Can Reduce Expenses Beyond Daycare

Daycare isn’t the only expense families might eliminate when one parent stops working. Commuting, parking, professional clothing, workplace meals, and occasional backup childcare can collectively consume thousands of dollars annually. For example, eliminating $200 monthly in commuting costs and $100 in work-related meals saves another $3,600 yearly. However, staying home can increase grocery bills, household utility usage, and spending on children’s activities. Track three months of actual work-related expenses to determine which costs would disappear and which might simply shift elsewhere.

A Break-Even Calculation Can Reveal The Better Choice

Before making a decision, calculate how much employment actually contributes to the household after avoidable expenses. Suppose a parent brings home $36,000 annually while spending $18,000 on daycare and another $3,600 on commuting and workplace expenses. Continuing employment would contribute approximately $14,400 annually before accounting for benefits, retirement contributions, or changes in household taxes. Quitting might still make sense for personal reasons, but it would not produce immediate cash savings under those assumptions. Compare both scenarios using realistic insurance costs, tax estimates, childcare prices, and emergency savings requirements.

Flexible Work Arrangements May Offer A Financial Middle Ground

Families don’t necessarily have to choose between expensive full-time daycare and completely abandoning employment. Remote work, flexible schedules, part-time positions, and coordinated parental shifts may reduce paid childcare hours. However, working remotely while supervising young children is not always practical, particularly when employers require uninterrupted availability. Parents should also investigate employer childcare benefits, dependent care flexible spending accounts, sibling discounts, and licensed home-based childcare options. Comparing at least three local providers and discussing scheduling flexibility with employers could reveal meaningful childcare savings without sacrificing an entire salary.

The Smartest Decision Isn’t Always The Cheapest One

Leaving work to avoid daycare can improve family life, but the financial outcome depends on more than childcare savings. Families should calculate lost take-home income, employer benefits, retirement contributions, and future earning opportunities before deciding. For some households, especially those paying for multiple children, staying home may genuinely be the better financial choice. Others may discover that maintaining employment protects thousands of dollars in annual income and long-term financial security.

Would you give up a paycheck to avoid daycare costs, or does maintaining two incomes provide greater peace of mind? Share your experience and thoughts in the comments.

What to Read Next

Are Parents Talking Enough About Emotional Safety at Home?

3 Unexpected Options for Stay At Home Moms to Make Extra Money

Childcare Costs More Than the Mortgage for Some Families — When Does Working Still Pay?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Personal Finance Tagged With: childcare savings, daycare costs, family finances, household budget, Money Saving Tips, Parenting, personal finance, retirement savings, stay at home parents, working parents

Kids Outgrow Clothes Fast — But These 7 Things Shouldn’t Be Bought Used

September 28, 2026 | Leave a Comment

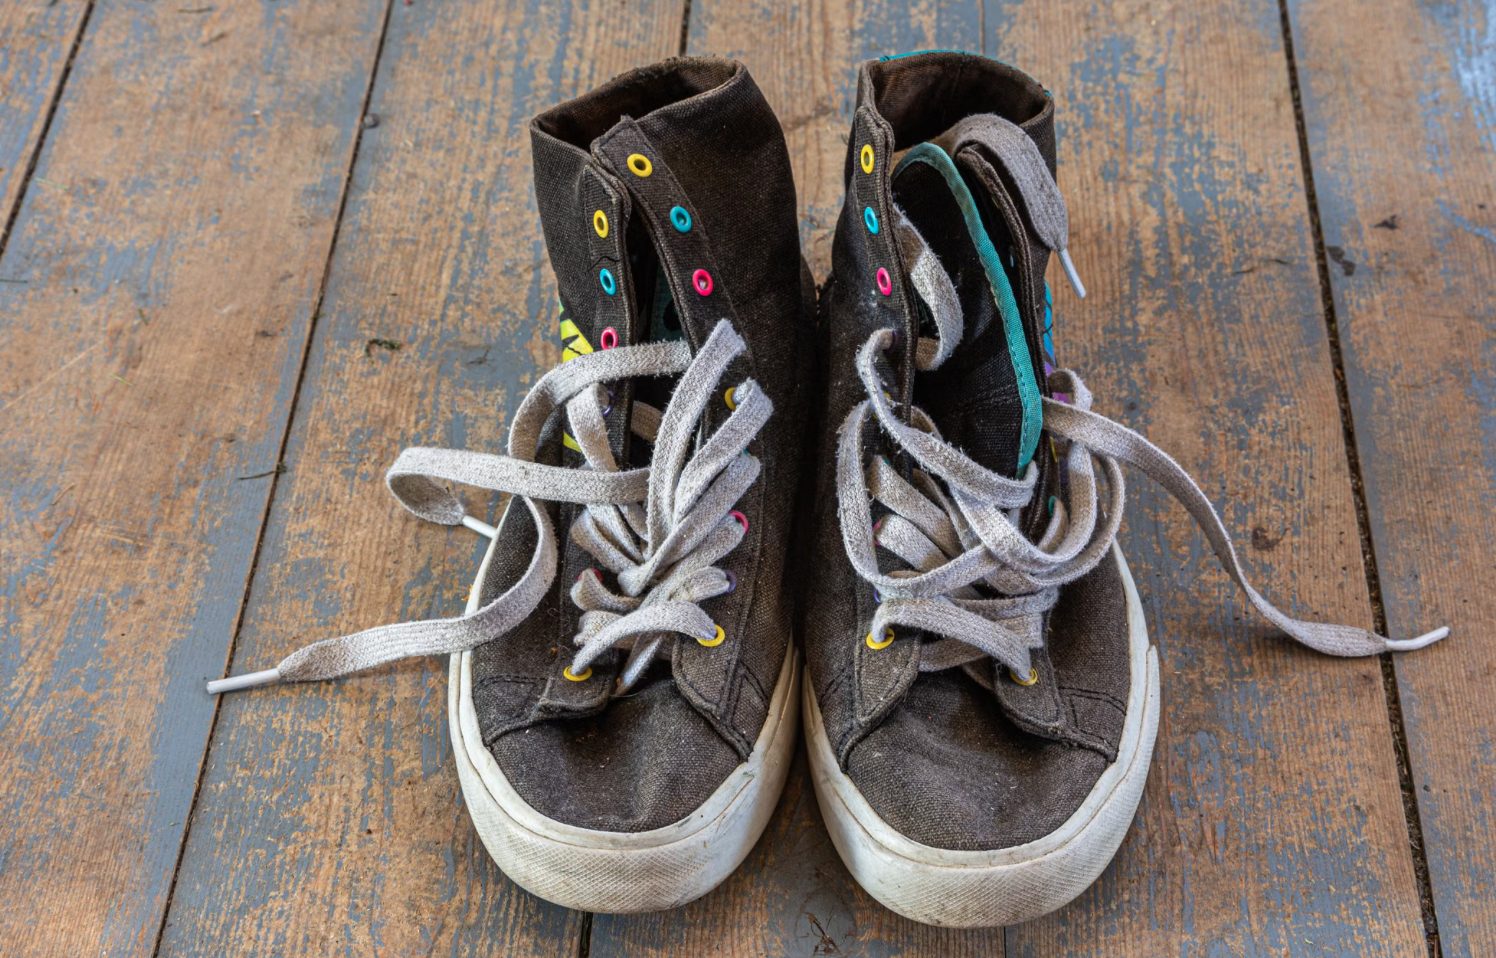
Kids Shoes
Secondhand clothing can stretch a family budget, but safety-sensitive products such as car seats, helmets and sleep gear require more caution. Knowing what to buy new can prevent a bargain from becoming a costly mistake. (Pexels).

Anyone raising children knows how quickly perfectly good clothes can become too small. Buying secondhand can be a smart way to stretch a family budget, particularly when many shirts and jeans are barely worn before they are outgrown. In 2026, the National Retail Federation reports that K-12 families expect to spend an average of $250.29 on clothing and accessories and another $174.01 on shoes. National Retail Federation That makes used kids items tempting, but some purchases carry risks that a bargain price cannot reveal.

1. Car Seats With An Unknown History

A used car seat can look spotless while hiding damage that cannot be seen from the outside. Consumer Reports notes that most car seats have useful lives of roughly six to 10 years, and crash history, recalls and expiration dates all matter. A marketplace seller may honestly believe a seat is safe without knowing whether it experienced damaging crash forces years earlier. If a new seat costs $180 while a used one costs $70, that $110 savings is difficult to justify when its complete history is uncertain. Among used kids items, car seats deserve particularly careful scrutiny.

2. Bike And Sports Helmets

Helmets are another product where damage may be hidden beneath a good-looking exterior. Consumer Reports recommends replacing a bicycle helmet after a crash even when damage is not visible, because the impact-absorbing foam may already have been compromised. It also recommends replacing a well-used helmet after approximately five years. Unless you personally know the helmet’s entire history, buying new removes an important unknown. Parents can still save by choosing a basic safety-rated model instead of paying extra for graphics or a fashionable brand.

3. Cribs With Missing Parts Or Labels

That beautiful hand-me-down crib may have more history than a seller realizes. The American Academy of Pediatrics advises families using previously owned cribs to make sure they meet current standards, have proper slat spacing and are not missing hardware. Repeated assembly, disassembly, or improvised replacement hardware can also make evaluating an older crib difficult. Older models may lack instructions or identifying information needed to check their history. A dresser can be a terrific secondhand find, but an infant’s primary sleep space deserves a higher bar.

4. Used Crib Mattresses

A crib mattress is another used item where appearance does not tell the whole story. Safe infant sleep requires a firm, flat surface that fits the crib properly, and a previously used mattress can develop sagging or damaged areas. The American Academy of Pediatrics emphasizes that the sleep surface should be firm and should not indent under the baby. Stains, moisture exposure, and unknown storage conditions provide additional reasons to be cautious with mattresses from strangers. Saving elsewhere in the nursery may make more sense than gambling on the condition of a baby’s sleep surface.

5. Single-User Breast Pumps

A secondhand breast pump can seem like an easy way to avoid another large baby expense, but check the manufacturer’s designation first. Medela, for example, states that its Freestyle Mini is a single-user product and should not be borrowed or purchased secondhand, even though it uses a closed-system design. That is different from equipment specifically designed and validated for multiple users, such as certain hospital-grade rental pumps. Parents should therefore never assume that “closed system” automatically means “safe to share.” With these used items, the model’s instructions matter more than the seller’s description.

6. Heavily Worn Shoes

Shoes are trickier because experts do not universally say every lightly used pair must immediately go in the trash. However, the American Podiatric Medical Association recommends checking children’s shoe sizing every four to six months and allowing roughly 10 to 15 millimeters of room ahead of the longest toe. A used shoe may already have compressed cushioning, uneven tread, or a shape influenced by its previous wearer. That makes heavily worn athletic shoes and everyday sneakers poor places to economize. Families can instead buy fewer new pairs, measure both feet and prioritize fit over expensive logos.

7. Children’s Sleepwear With Missing Safety Information

Used pajamas may look like ordinary clothing, but children’s sleepwear is subject to special flammability requirements. U.S. rules distinguish qualifying tight-fitting sleepwear from other children’s sleepwear, making fit and labeling more important than many parents realize. Cornell Legal Information Institute provides details on the federal requirements covering children’s sleepwear. Be cautious when resale pajamas have missing labels, unclear sizing, damaged fasteners or enough stretching that formerly snug sleepwear now hangs loosely. Buying new makes it easier to verify the intended size, labeling, and condition.

The Best Bargain Is Knowing Where Not To Cut Corners

Secondhand shopping still makes excellent financial sense for many children’s shirts, jeans, coats, books and other easy-to-inspect belongings. The key is separating cosmetic wear from products whose safety depends on history, structure, hygiene or precise fit. With families budgeting $174.01 on average for K-12 shoes alone in 2026, choosing carefully matters more than simply choosing new or used every time. Before buying used items for kids, ask whether you can verify the product’s age, condition, instructions, recall history and previous use.

Which children’s products do you happily buy secondhand, and which ones will you only purchase new? Share your experience in the comments.

What to Read Next

Bought Kids’ Toys From SHEIN or Amazon? Check These New Recalls Before Playtime

8 Money Lessons Kids Can Learn From One Trip to the Grocery Store

Are Parents Buying Too Many Clothes Before Kids Actually Need Them?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Baby Gear, car seats, child safety, children's clothing, Family Budget, Kids, Money Saving Tips, Parenting, parenting tips, secondhand shopping

7 School Purchases That Are Usually Cheaper After Classes Begin

September 9, 2026 | Leave a Comment

Stack Of Notebooks
Waiting until classes begin can help families avoid unnecessary school purchases and take advantage of later-season deals. Clothing, supplies, dorm accessories and some technology may be worth postponing. (Pexels).

Back-to-school shopping can feel like a race to buy everything before the first bell, but rushing may cost families more than necessary. In 2026, families with K-12 students expect to spend an average of $863.86 on school-related purchases, according to the National Retail Federation. Nearly half of shoppers who had not finished buying their supplies in early July said they were waiting for better deals. That makes patience a practical strategy for finding back-to-school savings, especially on items students do not need immediately. If your child can get through the first few weeks with the essentials, these seven purchases may be worth postponing.

1. Fall Clothing And Accessories

Buying an entire fall wardrobe before classes begin can mean paying when seasonal demand is strongest. Consumer Reports has previously recommended holding off on much of the fall apparel shopping because retailers may cut prices in September. Waiting also lets kids see what they actually enjoy wearing once their school routine begins. A practical compromise is buying a few first-week outfits, then filling wardrobe gaps as promotions appear. This approach creates back-to-school savings while reducing the risk of buying clothes that remain untouched in the closet.

2. Backpacks And Lunch Bags

A backpack is essential if your child does not already have a usable one, but replacing a perfectly functional bag before school starts is another matter. Retailers devote considerable shelf space to backpacks and lunch bags during peak shopping season, and leftover seasonal merchandise can become more attractive when stores need that space for fall inventory. Waiting also gives students time to determine whether they need extra compartments, laptop protection or a larger lunch bag. Keep using last year’s gear for several weeks if it remains comfortable and structurally sound. Just don’t delay if worn straps, broken zippers or poor fit make the existing backpack impractical.

3. Extra Notebooks, Binders And Folders

Those giant stacks of notebooks and folders look useful in August, but students may not need nearly as many as parents expect. The NRF reports that 47% of 2026 shoppers plan to buy only essentials initially and replenish supplies throughout the year. That strategy can prevent waste when teachers have specific requirements for binder sizes, notebook types or folder colors. Buy what’s explicitly listed, then watch for clearance prices on extras after the initial rush. Small purchases add up, making basic supplies an easy place to find back-to-school savings.

4. Dorm Room Decorations

College students can easily overspend trying to create a picture-perfect dorm before they have spent a single night there. Waiting a week or two reveals what actually fits, what a roommate already brought and which decorative items are genuinely wanted. That matters because 2026 back-to-college spending is expected to reach a record $103.5 billion, with shoppers budgeting an average of $194 for dorm or apartment furnishings. Consumer Reports also notes that back-to-school sales on dorm essentials can continue through the season rather than disappearing immediately. Start with bedding and necessities, then add rugs, organizers, lamps or decorative storage when you know the room’s real needs.

5. Shoes For The Entire Semester

Children need properly fitting shoes, but buying several pairs before school begins may unnecessarily lock families into August prices and sizes. Growing children can change sizes surprisingly quickly, while teenagers may reconsider which styles they want after seeing what works with their school routine. Instead of purchasing athletic shoes, casual shoes and backups simultaneously, consider buying the essential pair first. In 2026, K-12 families expect to spend an average of $174.01 on shoes, so avoiding even one unnecessary pair can protect the household budget. Spreading purchases across the semester also creates more opportunities for back-to-school savings.

6. Printers And Nonessential Tech

Electronics consume a major share of school budgets, but not every device must be purchased before classes begin. The NRF says K-12 shoppers expect to spend an average of $293.11 on electronics in 2026, while some schools provide devices directly to students. Waiting can reveal whether a student truly needs a home printer, tablet, headphones or another accessory. Consumer Reports says technology discounts can fluctuate throughout the back-to-school period, and later seasonal sales can provide additional opportunities. Before spending hundreds of dollars, check the school’s technology requirements and confirm what equipment is already provided.

7. Backup Supplies For Later In The Year

Families often buy extra pencils, markers, paper and classroom supplies because they assume everything will eventually be needed. Stocking up makes sense when the price is exceptionally low, but otherwise those extras can tie up money and create clutter. Once classes begin, parents have a clearer picture of which supplies their children use quickly and which barely leave the backpack. Keep a short replenishment list and compare unit prices instead of assuming a large multipack automatically offers the best value. This targeted approach can produce back-to-school savings without sacrificing anything a student genuinely needs.

Patience Can Be Part Of Your School Shopping Strategy

The goal isn’t to postpone every purchase, because students should start school with the essentials their teachers require. Instead, separate immediate needs from items that can comfortably wait several weeks. Current shopping behavior supports that strategy: NRF found that shoppers had completed only 44% of their lists on average by early August 2026, showing that plenty of families were still purchasing as classes approached. Delaying selected purchases can help families compare prices, understand actual classroom needs and avoid paying for things children never use.

Which school purchase have you learned to wait on, and where have you found your best bargains? Share your experience in the comments.

What to Read Next

8 School Expenses That Can Hit Families After the First Day

7 Back-to-School Expenses Parents Forget to Budget for Until September

Youth Sports Cost Families $1,016 a Year on Average — 8 Expenses New Parents Don’t Expect

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Personal Finance Tagged With: Back To School Shopping, back-to-school savings, Family Budget, Money Saving Tips, Parenting, school shopping, school supplies, student expenses

Back-to-School Costs Are Climbing Again: Which Expenses Do Parents Forget Until August?

July 26, 2026 | Leave a Comment

Group Of Students
Hidden back-to-school costs often include technology accessories, activity fees, classroom supplies, and everyday expenses that appear after classes begin. Planning ahead for these overlooked purchases can help families stay on budget. (Pexels).

As summer winds down, many families think the biggest back-to-school purchases are already behind them. Then August arrives, and a wave of overlooked expenses begins piling onto the budget. While backpacks, notebooks, and lunchboxes usually make the shopping list, several hidden costs often catch parents off guard. According to the National Retail Federation, families with K-12 students are expected to spend an average of nearly $864 this back-to-school season, with electronics, clothing, shoes, and supplies driving much of the increase.

Classroom Requests Keep Growing After School Starts

Many parents assume the school supply list is final, but teachers frequently request additional materials once classes begin. Items like tissues, hand sanitizer, printer paper, art supplies, headphones, or specialty notebooks often appear during the first few weeks of school. In classrooms with limited budgets, teachers sometimes ask families to replenish shared supplies throughout the year. A parent who budgeted $150 for supplies may easily spend another $50 to $100 before September ends. Planning for these follow-up requests can prevent an unpleasant surprise.

Technology Costs Go Beyond Buying a Laptop

Technology has become one of the largest back-to-school costs for many families. Even if a child already owns a laptop or tablet, parents may still need to purchase headphones, chargers, software subscriptions, calculators, printer ink, or protective cases. Some schools also recommend backup batteries or cloud storage for assignments. The National Retail Federation reports that electronics remain the largest spending category for many families, reflecting how essential digital learning has become. Budgeting for accessories is just as important as budgeting for the device itself.

Activity Fees Add Up Faster Than Expected

School registration often doesn’t include every expense students will face during the year. Sports participation fees, band uniforms, field trips, club memberships, yearbooks, parking permits, and fundraising commitments frequently arrive weeks after classes begin. Families with multiple children can quickly find themselves paying several hundred dollars beyond their original budget. Even public schools often charge optional fees that become difficult to avoid once children become involved. Setting aside a separate activities fund before August can make these costs much easier to handle.

Clothing Isn’t Finished After the First Shopping Trip

Many parents buy new clothes before school starts, only to discover their child still needs additional items later. Dress code requirements, seasonal weather changes, growth spurts, and worn-out shoes can all lead to unexpected purchases. Teenagers may also need specific clothing for athletics, science labs, or school performances. Retail experts note that many families intentionally buy only essential items at first and return later for additional purchases as needs become clearer. Leaving room in the clothing budget helps reduce financial stress.

Lunches, Transportation, and Everyday Extras Stretch the Budget

Some of the biggest forgotten back-to-school costs aren’t purchased in stores at all. School lunches, after-school snacks, increased grocery bills, fuel for daily drop-offs, parking fees, and childcare during early dismissal days quietly add up over time. Families also spend more replacing reusable water bottles, lunch containers, and other everyday items that wear out during the school year. Recent surveys show many parents continue making back-to-school purchases well after classes begin, with more than half spending at least another $250 after the first day of school. Tracking these ongoing expenses helps families avoid overspending.

The Smartest Way to Prepare for Hidden Back-to-School Costs

The easiest way to reduce financial stress is to expect these hidden back-to-school costs before they happen. Instead of spending every dollar before school begins, consider reserving 15% to 20% of your budget for August and September surprises. Shopping during major summer sales, comparing prices online, reusing supplies when possible, and involving children in budgeting decisions can also help stretch every dollar. Financial experts recommend focusing first on necessities rather than trends or brand-name items that often increase spending without adding real value. A little flexibility in your budget today can prevent relying on credit cards later in the school year.

Budgeting Today Can Save Stress Tomorrow

Hidden back-to-school costs often create more financial pressure than the supplies parents plan for months in advance. Building a realistic budget that includes classroom requests, technology, activities, clothing, and daily expenses can help families stay ahead. Every household will face different priorities, but planning for the unexpected makes the school year less stressful.

Which hidden school expense has surprised your family the most? Share your experience and budgeting tips in the comments to help other parents prepare.

What to Read Next

10 Places Parents Can Find Free School Supplies Before Classes Begin

Teachers Beg Parents: Stop Buying These 7 Expensive School Supplies

Here’s Why School Supplies Continue to Cost More and More Every Year

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Finance Tagged With: back-to-school costs, education, Family Budget, Money Saving Tips, Parenting, personal finance, school shopping, school supplies

The One Back-to-School Expense Families Forget Every Year

July 19, 2026 | Leave a Comment

Backpacks
Parents often budget for backpacks and supplies but overlook the smaller school costs that appear throughout the year. Planning ahead for hidden school expenses can help reduce financial stress. (Pexels).

Back-to-school shopping usually starts with notebooks, backpacks, and new shoes, but one important cost often catches families by surprise after the first day of class. Hidden school expenses can quietly add hundreds of dollars to a family’s budget over the course of the school year. While many parents carefully plan for supply lists, they often overlook the steady stream of smaller costs that arrive weeks or months later. Recognizing these expenses early can help families avoid financial stress and keep their budgets on track.

The Hidden School Costs That Add Up Fast

The biggest forgotten expense isn’t a single purchase but the ongoing costs that appear throughout the school year. Field trips, classroom activity fees, school photos, book fairs, spirit wear, fundraisers, replacement supplies, and club dues can easily add up before parents realize how much they’ve spent. A child who loses a water bottle, breaks headphones, or needs new folders halfway through the year creates additional surprise expenses. According to the National Retail Federation, families already expect to spend hundreds of dollars before school even begins, making unexpected costs even harder to absorb. Planning for these hidden school expenses from the beginning helps prevent financial surprises later.

Why These Expenses Catch Families Off Guard

Most school shopping happens during a few busy weeks, giving parents the impression that the largest costs are behind them. However, schools often send permission slips, fundraiser announcements, and activity requests throughout the year instead of all at once. A family might pay $20 for a field trip one week, $35 for school pictures the next, and another $25 for a classroom celebration shortly afterward. None of these expenses seems overwhelming on its own, but together they can significantly stretch a monthly budget. This pattern explains why many families feel financially squeezed even after finishing their back-to-school shopping.

Simple Ways to Prepare Before the School Year Starts

Creating a small “school extras” fund is one of the easiest ways to stay ahead of unexpected costs. Even setting aside $15 to $25 each month throughout the year can build a helpful cushion before classes begin. Keeping extra pencils, glue sticks, folders, and notebooks at home also reduces last-minute trips to the store when supplies run out. Shopping during seasonal sales and purchasing generic brands whenever schools allow can stretch every dollar further. Many parents also reuse gently used backpacks, lunch boxes, and binders if they remain in good condition, saving money without sacrificing quality.

Don’t Forget Technology and Replacement Costs

Technology has become another overlooked category of hidden school expenses. Many students now need headphones, calculators, charging cables, computer mice, or device cases, and these items occasionally need replacing during the school year. Younger children are especially likely to misplace accessories or accidentally damage them through everyday use. Purchasing inexpensive protective cases and labeling personal items can reduce replacement costs while helping children keep track of their belongings. Spending a little on prevention often saves much more than repeatedly replacing lost or broken equipment.

Looking Beyond the Supply List

Back-to-school shopping doesn’t truly end when the first bell rings because hidden school expenses continue appearing throughout the year. Families who plan ahead for these smaller costs often experience less financial stress and avoid relying on credit cards for unexpected purchases. A realistic annual school budget should include not only supplies and clothing but also room for activities, replacement items, and special events. Preparing for the expenses you cannot always predict is one of the smartest financial moves parents can make.

Which hidden school expense surprised your family the most, and what tips would you share with other parents? Leave a comment and join the conversation.

What to Read Next

Why “Back to School” Shopping Feels Like a Mortgage Payment Now

5 Ideas For Back To School Photos

6 School Policy Changes Parents Should Watch This Year

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: Back to School, education, Family Budget, hidden school expenses, Money Saving Tips, Parenting, personal finance, school supplies

Why Savvy Moms Are Refusing to Buy These 7 Kid Essentials Brand New

March 14, 2026 | Leave a Comment

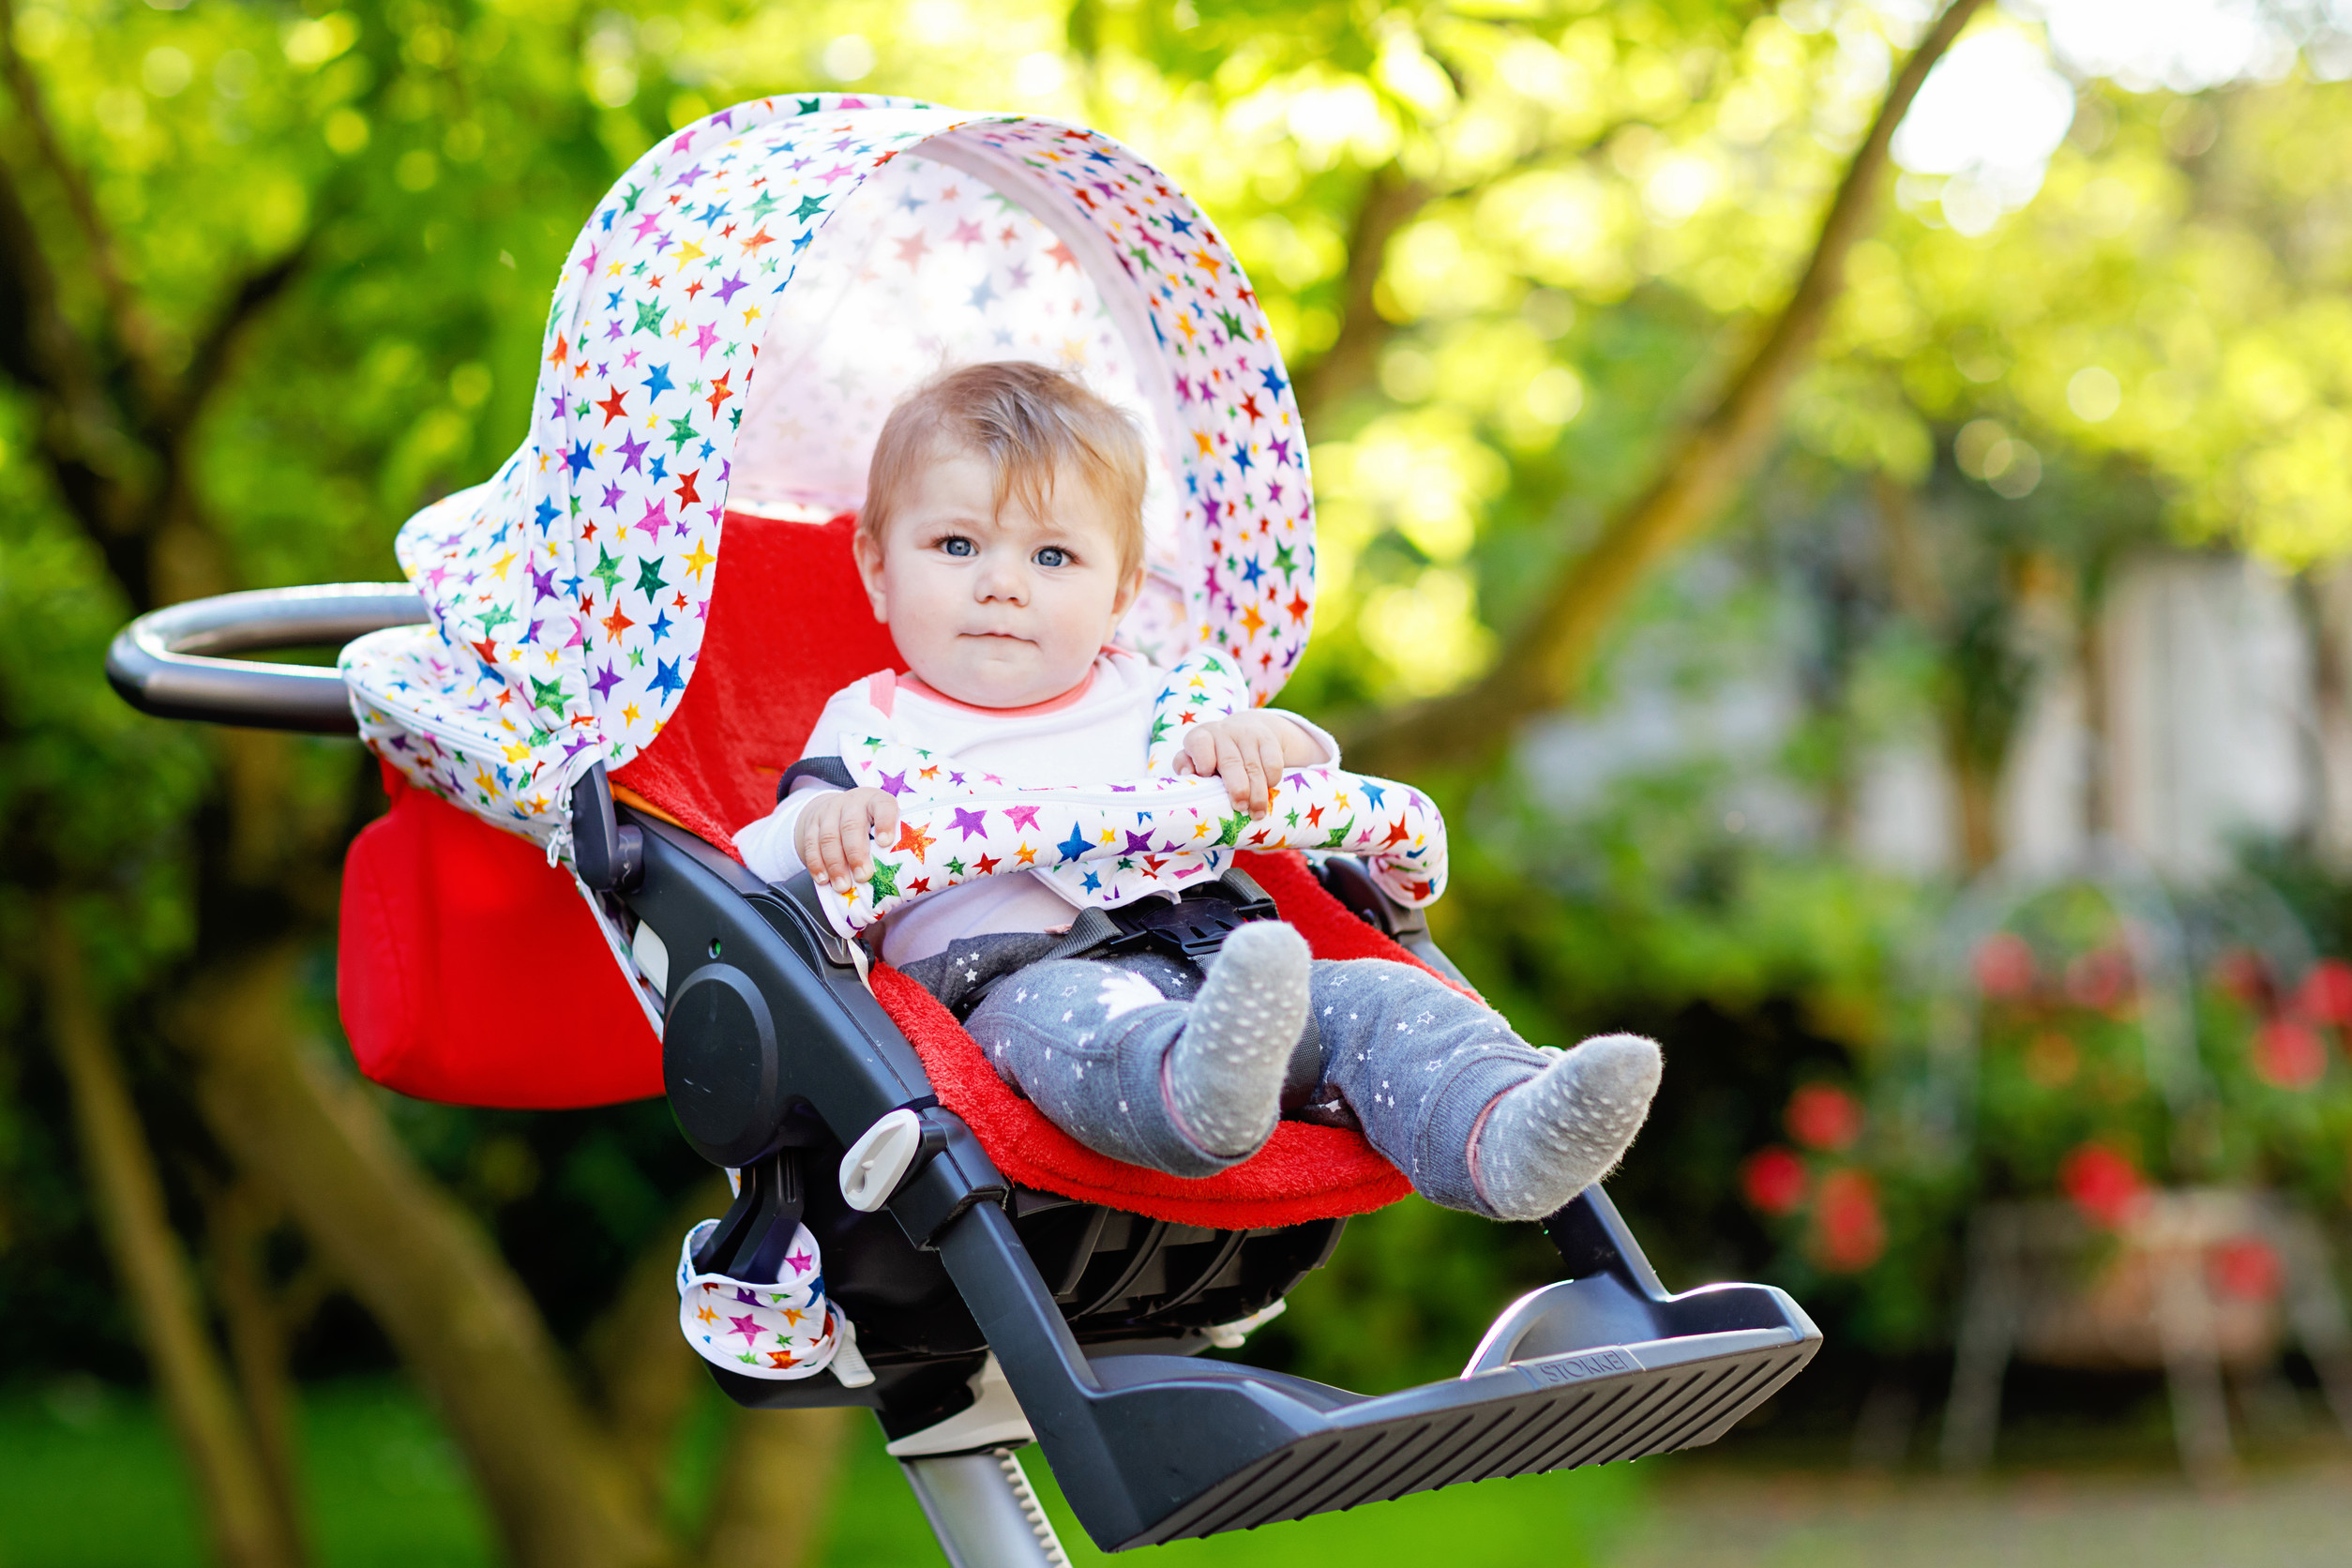
Cute healthy little beautiful baby girl sitting in the pram or stroller and waiting for mom. Happy smiling child with blue eyes. With green tree background. Baby daughter going for a walk with family.
Image Source: 123rf.com

When you walk into a high-end baby boutique, the scent of new plastic and organic cotton can feel like a rite of passage. It is easy to believe that spending a small fortune on a nursery is a direct reflection of your love. However, the retail industry spends billions on psychological marketing to convince you that love equals a high price tag. Savvy moms are finally waking up to the reality of depreciating assets. Most kid gear loses half its value the second you leave the store. We want to help you opt out of the consumerist cycle that drains your savings before your child even walks. Here is why buying these 7 kid essentials brand new is a financial trap.

1. The Stroller Depreciation Trap

High-end strollers are the luxury SUVs of the parenting world. You see them priced at over a thousand dollars in glossy magazines, often marketed with advanced suspension systems as a safety requirement. The truth is that many of these strollers end up in garage sales after only eighteen months. You can find top-tier brands like UPPAbaby or Bugaboo on marketplaces for a fraction of the cost. According to Consumer Reports, many used strollers remain perfectly safe if they lack damage or recalls. Buying used allows you to skip the massive initial markup. You can score high-end baby brands at consignment prices by knowing where to look.

2. Why Hardwood Nursery Furniture is a Sunk Cost

Surprisingly, that heirloom-quality crib is not a great financial investment. Most infants only use a crib for two years before moving to a toddler bed. The system of nursery decor relies on nesting instincts to drive emotional spending, like buying a dresser that matches the crib perfectly. Then, your toddler inevitably scratches the wood or spills juice on the finish. On the other hand, the secondary market is flooded with nursery sets from parents who need the space. You can often find solid wood pieces for eighty percent off the retail price. Focusing on a minimalist nursery approach ensures you only buy what you actually need.

3. The High Cost of Tiny Occasion Wear

Have you ever spent eighty dollars on a flower girl dress that your child wore for exactly four hours? Retailers love occasion wear because they know parents feel pressured to make memories look perfect. This clothing has almost no resale value once the season passes. You can find these items at consignment shops in pristine condition. Many of them still have the original tags because the previous child grew too fast. Opting for used formal wear doesn’t make the photos less special. It simply makes the bill easier to stomach while you save for the actual celebration.

4. High Chairs and the Cleaning Nightmare

Manufacturers design high chairs to look sleek and modern in your kitchen. However, after three meals, every high chair becomes a magnet for dried oatmeal and sticky juice. Buying a new high chair is often a waste of money because the materials are highly durable. Plastic and metal frames last through multiple children without losing any functionality. You can easily sanitize a used chair with basic household cleaners. According to the American Academy of Pediatrics, the main concern is the stability of the harness. If the straps work, a used chair is just as effective and saves you nearly a hundred dollars on average.

5. Why Activity Jumpers are Fleeting Phases

These large plastic contraptions take up a massive amount of floor space. Most babies only enjoy them for a window of about four months. Once they learn to crawl or walk, the jumper becomes a giant dust collector. The retail price for these items is often over sixty dollars, but you can find them at thrift stores for ten dollars. Most parents are desperate to get them out of their houses to reclaim their living room. Taking a used jumper off their hands is a win for everyone, as you get the gear for pennies.

6. Plastic Outdoor Toys and Playhouses

The sun is the enemy of expensive plastic playhouses. Within one summer, the bright colors fade and the material starts to weather. Buying these brand new is a mistake because they are built to withstand the elements anyway. A used playhouse functions exactly the same as a new one. You can find them on local community boards for free if you are willing to haul them away. Children do not care if the plastic is slightly faded. They only care about the imaginary world they build inside. Use that saved cash to build a college fund on a single income instead.

7. Specialized Training Gear and Sports Equipment

Kids change their minds about hobbies faster than they change their socks. You might buy brand new soccer cleats and pads only for your child to quit after two weeks. The sports industry relies on this churn of equipment to drive profits. You should always look for used sports gear during the first year of a new activity. Many league families trade equipment as kids grow. This ensures you aren’t stuck with expensive gear for a sport your child no longer plays. It is a smart way to support their interests without risking your 2026 budget.

Winning the Parenting Budget Battle

The goal of this investigation is to validate your choice to spend wisely. You are not a cheap parent for choosing used items. You are a savvy one who understands the hidden costs of retail marketing. Empowerment comes from realizing that your child needs your presence more than new plastic. By refusing to buy these 7 kid essentials brand new, you reclaim thousands of dollars. This money can fund family experiences that actually last a lifetime. You deserve to have financial peace while raising your family. It is time to treat your household budget with the authority it deserves. Which of these items have you successfully found used? Leave a comment below and share your best marketplace find with us.

What to Read Next…

  • 8 Once-Normal ’70s Kids Hobbies That Helicopter Parenting Quietly Killed
  • 5 Baby Products Pediatricians Warn Parents to Stop Using Early
  • Pediatricians Say Parents Are Overbuying These 4 Baby Items (And Skipping What Matters)
Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.  As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy.

Filed Under: Budgeting Tagged With: baby essentials, frugal living, marketplace finds, Money Saving Tips, parenting budget, savvy shopping, used baby gear

6 Budgeting Hacks from Depression Era Grandmothers

March 5, 2026 | Leave a Comment

budgeting hacks
Image source: shutterstock.com

In a world of digital apps and automated transfers, we have lost touch with the gritty, effective wisdom of the past. Honestly, our grandmothers knew more about stretching a dollar than any modern finance guru ever will. They lived through a time when every penny was a lifeline, and “waste not, want not” was a survival strategy. This hidden system of extreme frugality is the ultimate weapon against today’s rising inflation and economic uncertainty. You do not need a fancy spreadsheet to get your finances in order; you need to look back at the habits that kept families fed during the Great Depression. Here are the timeless hacks that will change how you look at your bank account.

1. The Power of the Cash Envelope

Before credit cards, people only spent what they physically had in their hands. Using cash for your daily expenses like groceries and gas creates an immediate psychological barrier to overspending. When the envelope is empty, the spending stops—period. This simple act of physical accounting prevents the “invisible” leak of digital transactions that drain our accounts. You will be surprised how much more carefully you shop when you have to count out the bills. Modern budgeters call this cash stuffing, and it remains the most effective way to see exactly where your money goes every week. It is a discipline that turns into freedom.

2. Eating from the Back of the Pantry

Depression-era cooks never let a single ingredient go to waste, turning scraps into hearty meals. We have become accustomed to “re-stocking” before we have even finished what we already own. By committing to a “pantry week” once a month, you can save hundreds on your grocery bill. Use the rice, beans, and canned goods you have hidden in the back before buying anything new. This habit reduces food waste and forces you to get creative with what you have. According to the EPA, the average family of four loses nearly $3,000 a year to uneaten food. You are literally eating your way to a better budget.

3. The Art of the “Make Do and Mend”

We live in a disposable culture where it is easier to buy a new shirt than to sew on a button. Our grandmothers knew that maintaining what you own is the secret to long-term wealth. Learning basic repair skills can save you thousands over the course of a lifetime. This mindset stems from the historic Make Do and Mend campaign, which encouraged families to revitalize old clothes rather than buy new ones. Whether it is mending a hem or fixing a leaky faucet, doing it yourself keeps your money in your pocket. This mindset shifts you from a consumer to a caretaker of your belongings.

4. Growing Your Own Vitamin Bank

A small garden is more than just a hobby; it is a hedge against rising food prices. Even a few pots of herbs or a tomato plant on the balcony can significantly lower your produce costs. During the Great Depression and WWII, Victory Gardens were essential for family survival, eventually producing 40% of the nation’s vegetables. Starting small allows you to learn the skill without a massive initial investment. Fresh, home-grown food is better for your health and your wallet than anything you can buy at the store. Every harvest is a win for your budget.

5. Practicing the 24-Hour Rule

Impulse buying was a luxury that didn’t exist for most people eighty years ago. They had to weigh every purchase against the actual hours of labor it cost to earn that money. By waiting 24 hours before any non-essential purchase, you allow the “want” to fade and the “need” to be evaluated. This psychological cooling-off period ensures that your rational mind, rather than a temporary impulse, makes the final decision. Often, the urge to buy disappears entirely once you step away from the screen. Patience is a budgeting superpower.

6. Finding Joy in Free Community

Entertainment does not have to be a line item in your budget every single weekend. Depression-era families relied on potlucks, public parks, and libraries for their social lives. We have been conditioned to believe that “going out” must involve spending money at a restaurant or theater. Transitioning to free local activities allows you to save for big goals without sacrificing your social life. Public libraries today offer far more than just books; they provide free workshops, movies, and even “libraries of things” where you can borrow tools or equipment for free.

Timeless Wisdom for Modern Times

The habits of our grandmothers are more relevant today than ever before as we navigate an uncertain economy. You have the power to break free from the cycle of debt by embracing these simple, proven strategies. It is not about deprivation; it is about intentionality and respect for the money you work hard to earn. These hacks provide a roadmap to security that no app can match. By looking to the past, you are securing a much brighter financial future for your family.

Which of these old-school hacks are you going to try first? Leave a comment below!

What to Read Next…

  • Budgeting Tips for Parents in the Month After the Big Holiday Bills Arrive
  • 10 Mistakes Parents Make When Talking About Money With Kids
  • Why Meal-Planning During the Holidays Can Save You More Than Just Money
Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.  As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy.

Filed Under: Money and Finances Tagged With: budgeting hacks, debt free, Family Finance, financial wisdom, frugal living, Great Depression, inflation tips, Money Saving Tips, old school budgeting, Saving Money

15 Surprising Ways Your Daily Habits Impact Your Finances

May 20, 2024 | Leave a Comment

daily habits

Your financial health isn’t just determined by major decisions like investments or big purchases—it’s often influenced by the everyday habits you might not even think twice about. From your morning routine to how you unwind at night, here are 15 surprising ways your daily habits can impact your finances.

1. Morning Coffee Run

coffee run

Your daily coffee run might seem like a harmless indulgence, but those small expenses can add up quickly. Spending $5 on a latte every day translates to $1,825 a year—money that could be put towards savings or investments. Consider brewing your coffee at home or investing in a quality coffee maker to save hundreds of dollars annually. By cutting back on this daily habit, you’ll not only save money but also start your day with a financial boost.

2. Skipping Breakfast

skipping breakfast

Missing the most important meal of the day can lead to impulsive spending on snacks later. Investing in a nutritious breakfast can boost your energy and save you money in the long run. Especially if you are commuting to work, grabbing an on-the-go breakfast from home, like a breakfast bar, can save you a good amount of money. In sum, skip the Dunkin Donuts run to cut back on your spending.

3. Online Shopping Binges

online shopping

Those late-night scrolling sessions can lead to unnecessary purchases. Consider implementing a waiting period before hitting “checkout” to curb impulse buys. Shopping when you’re tired or bored can lead to impulse buys. Avoid online shopping late at night and save your purchases for when you’re more alert and focused.

4. Unplanned Grocery Trips

unplanned grocery trips

Shopping without a list can result in buying items you don’t need. Plan your meals for the week and stick to a shopping list to avoid overspending at the grocery store. Also, don’t grocery shop when you’re hungry. Everything looks good when you’re starving and can seriously alter your grocery shopping list.

5. Unused Subscriptions

subscriptions

Unused subscriptions often fly under the radar, silently draining your bank account month after month. Whether it’s a streaming service you signed up for but rarely use or a gym membership that collects dust, these subscriptions can add up to significant expenses over time. Take the time to review your subscriptions regularly and cancel any that you don’t actively utilize. By freeing up this extra cash, you can redirect it towards more meaningful expenses or savings goals.

6. Eating Out Frequently

eating out

Frequent dining out may provide convenience, but it often comes at a hefty price. The cost of restaurant meals, beverages, and tips can quickly escalate, putting a strain on your budget. By opting to cook at home more often, not only can you save money, but you also gain control over ingredients and portion sizes, leading to potentially healthier eating habits. Planning meals ahead of time and enjoying home-cooked dishes can not only benefit your wallet but also your overall well-being.

7. Ignoring Energy Efficiency

energy efficiency

Ignoring energy efficiency practices at home can lead to inflated utility bills month after month. Leaving lights on, keeping electronics plugged in, and neglecting to adjust thermostat settings can all contribute to unnecessary energy consumption. By developing simple habits such as turning off lights when leaving a room, unplugging electronics when not in use, and adjusting the thermostat to conserve energy, you can significantly reduce your utility costs over time. Taking proactive steps to improve energy efficiency not only saves money but also reduces your environmental footprint, making it a win-win situation.

8. Paying ATM Fees

ATM fees

Frequently using out-of-network ATMs can result in substantial fees that eat into your budget. These fees, often ranging from $2 to $5 per transaction, can add up quickly, especially if you make multiple withdrawals each month. Planning ahead and withdrawing cash from your bank’s ATM or opting for cashback at stores can help you avoid these unnecessary charges. Some banks also offer ATM fee reimbursement, so make sure to take advantage of this perk if offered by your bank.

9. Daily Commute Costs

daily habits commuting to work

Driving solo to work every day can drain your budget with gas and parking expenses. The average commuting expense per year in 2023 was $8,466. To cut down on costs, ask your employer for a hybrid work schedule, working from home on some days. If this isn’t possible, consider carpooling, biking, or using public transportation to save money on transportation.

10. Impulse Buying

impulse buying

Those small impulse purchases at the checkout counter can add up over time. Impulse buying is often linked to unhappiness, which motivates impulsive buying decisions. Often we believe that impulse buys will make us feel better, but that often is a fleeting feeling. Stick to your shopping list and avoid the temptation to save money and also improve your well-being.

11. Mindless Snacking

snacking

Constant snacking throughout the day can lead to overspending on convenience foods. Plan healthy snacks ahead of time to avoid impulse purchases. It may be helpful to portion out snacks or buy pre-portioned snack packs to avoid mindless snacking. This can help your whole family manage portions and ultimately save money.

12. Overusing Credit Cards

overusing credit cards

Swiping your credit card for every purchase can lead to debt accumulation due to high interest rates. Use cash or a debit card for everyday expenses to stay within your budget. If you do utilize your credit cards, make sure that you can pay off your balance at the end of the month to avoid interest fees. At the very least, make sure that you can comfortably pay the minimum balance owed to avoid unnecessary late fees.

13. Ignoring Discounts and Coupons

coupons

Failing to take advantage of discounts and coupons means missing out on potential savings. Keep an eye out for deals and promotions to stretch your dollars further. Many influencers on social media will post the best deals of the week, so you don’t have to do a lot of extra work to snag the most savings. You can also get helpful rebates on Ibotta and Fetch to help you offset the cost of groceries and everyday purchases.

14. Not Tracking Expenses

budget

Ignoring your daily spending habits can lead to financial leaks. Keep track of your expenses using budgeting apps or spreadsheets to identify areas where you can cut back. Knowledge is power when it comes to managing your finances. Many banking apps can help you set up a budget that makes sense for your financial goals.

15. Rewarding Yourself with Little Treats

treat yourself

Usually, when we’re stressed it’s easy to motivate ourselves with the thought of a little reward. This could be grabbing a drink after work, buying something you’ve been eyeing on Amazon, or getting a massage. While these treats are great for your well-being, it’s important to keep your financial goals in mind. Make sure treats don’t become daily habits that you justify by saying, “I deserve this.”, or “I don’t do this often.” Ultimately, treating yourself can have a heavy financial impact at the end of the month.

Considering Your Financial Well-Being

financial health

Being mindful of your daily habits is crucial for maintaining financial well-being and achieving long-term goals. Small changes, such as brewing your coffee at home, cooking meals instead of eating out, and turning off lights when leaving a room, can have a significant impact on your budget over time. By consistently making smart choices in your daily routine, you can save money, reduce unnecessary expenses, and allocate funds toward your financial priorities. Ultimately, practicing mindfulness in your daily habits empowers you to take control of your finances and build a more secure future.

Read More

12 Things You Should Never Do at a Casino

17 Odd Rituals People Do Behind Closed Doors

Teri Monroe
Teri Monroe
Teri Monroe started her career in communications working for local government and nonprofits. Today, she is a freelance finance and lifestyle writer and small business owner. In her spare time, she loves golfing with her husband, taking her dog Milo on long walks, and playing pickleball with friends.

Filed Under: Money and Finances Tagged With: Money Saving Tips, personal finance, Saving Money

How to Save Money – 35 Top Ways for Parents to Save Money

May 15, 2017 | 2 Comments

how to save moneyNo matter what you earn in a year, if you’re raising a child, then saving money is going to be a huge part of your life. You’ll save for diapers, school supplies, soccer cleats, and college. To help in your frugal efforts, here is a master list of how to save money.

Many of these tips came from real parents discussing this important topic via SavingAdvice.com.

How to Save Money – 35 Top Ways for Parents to Save Money

This is one of those articles that can be a useful resource for you, time and time again. As you read through, there will be things you can apply to your life today, but some tips may not apply til later. I suggest you bookmark or pin this post to ensure you have access to you it later.

  1. Switch to bank accounts with no fees.
  2. Cancel unused memberships.
  3. Cancel subscriptions. Examples include magazines, newspapers, online entertainment, dating, or networking memberships.
  4. Skip the cafe and bring home brewed coffee to work.
  5. Eat out less; cook at home more.
  6. Save money on your electricity bill. Install a smart meter (some libraries loan them out for free) to measure how much electricity your appliances are using. You could be saving more by simply unplugging what you can.
  7. Contact your cell phone provider to ask how to save money on your bill. They may have a discount plan to offer.
  8. When other phone companies cold call you, ask if they can beat your current company’s price.
  9. Are you looking at a phone for your child that’s only to be used for emergencies? Try buying a prepaid phone rather than something on contract.
  10. Comparison shop. This is huge for every major purchase in your life – from cribs to colleges.
  11. Don’t buy “convenient foods” when you can make something from scratch. Frozen meals are quicker to prepare but you pay for the convenience and they’re often much less healthy for you.
  12. Buy in bulk versus smaller quantities at traditional supermarkets (Costco, Amazon’s Subscribe and Save).
  13. Batch your meals on the weekends. By preparing a large quantity of breakfast or snack foods during the weekend, you’re setting up your week to be more frugal and freeing up a considerable amount of time.
  14. Save those pennies and dimes. Designate a family piggy bank for all your coins. When it’s full, go do something fun together.
  15. Don’t balk at used items. Yard sales, thrift stores, and online garage sales may have just the items you’re looking for at a fraction of the price. Children’s clothing is a prime example, especially when they’re very young. They grow so fast!
  16. Whenever you can, shut off your heat or air conditioning and throw open those windows. You’ll save a considerable amount on your utility bill in the long run.
  17. Get creative with transportation. Can you carpool, ride a bike, or even walk to work? These may seem like extremes, but they’re also fantastic ways to save money on gas as well as preserve the life of your vehicle.
  18. Reconsider that credit card “deal.” As popular as it is to accumulate airline miles or to snag that 30% savings at Kohl’s consider the long-term drawback your experiencing.
  19. Be mindful of your spending habits. If you’re bringing home a paycheck, but there’s nothing left at the end of the week to drop into savings, then it’s time to dig in and evaluate what you’re really spending.
  20. Clip or download coupons. Apps like Cartwheel or Paribus or RetailMeNot can give you convenient methods for saving on weekly expenses.
  21. Wait at least 24 hours before making a large purchase. Give yourself a chance to come down from your “fever” to make a more thought-out decision.
  22. Check your wallet. By knowing how much money you have before you walk out the door, you’ll be aware of what you can and cannot spend throughout that day.
  23. Pack your lunch.
  24. Find some free hobbies.
  25. Identify wants versus needs.
  26. Lower your car insurance by combining policies or paying it annually instead of monthly.
  27. Learn how to save money on child-related taxes. See a full run-through of your options here.
  28. Launch a “No-Spend Challenge”. Choose a spending category (i.e. fast food) and set a time for not spending any money in that category.
  29. Try the 52-Week Money Challenge. Learn how to save over $1,300 a year here.
  30. Use a monthly budget. I know from experience that this will help you conquer debt more quickly and save money before you ever spend money elsewhere.
  31. Find deep discounts on Amazon merchandise through SnagShout.com.
  32. Don’t spend your tax return; save it.
  33. Automate a monthly transfer into savings. You’re much more likely to stick with it!
  34. Pay $100 extra on your mortgage each month. This doesn’t save money in the short-term, obviously, but you’ll save thousands in interest over time.
  35. Get accountability. However you’re saving money for your family, one of your most powerful tools is support. Not only does my spouse hold me accountable on a continual basis, but I love feeding off the positive energy in a supportive Facebook group of like-minded savers called “Your Debt Freedom Family.” We only discuss things related to our families and our finances – no spam or marketing. If you’d like to join, you can do so here!

The biggest progress I made when I was trying to figure out how to save money as a parent was remembering my “Why.” In my case, it was the little one growing rapidly in my tummy. She didn’t know it at the time, but my first child gave me strength, every day, to cut back, live on the budget, and save. It was worth it for her.

What’s one money-saving tip you’d add to this list? We’d love to hear about it in the comments below!

Are you a stay-at-home mom? Check out these bonus resources just for you!

  • 10 Steps to a Successful Stay-at-Home Mom Budget
  • How to Afford Your Dream of Becoming a Stay-at-Home Mom
  • 14 Online Jobs for Stay-at-Home Moms (That Are Worth Your Time)
  • 13 Ways for Stay-at-Home Moms to Save Money
  • Loans for Stay-at-Home Moms – What Are YOUR Options?
  • The SAHM Budget Test: How to Afford to Be a Stay-at-Home Mom

Filed Under: Family Time, Money and Finances, Parenting Tagged With: best ways to save money as parents, how to save money, Money Saving Tips, personal finance, Saving Money

Money Saving Tips For First Year College Students

November 14, 2013 | 1 Comment

first year college studentsAll over the world high school students are preparing to graduate and embark on their post secondary adventures. I know all too well how expensive post secondary can be after completing two degrees and accumulating over $90,000 in debt. In my six years of university I have made many financial mistakes but learned something from all of them.


Textbooks

Don’t buy new textbooks. If you are absolutely required to even buy a book at all, buy used textbooks. In my first year I went to the book store and dropped hundreds of dollars on my brand spankin’ new books for my accountancy and finance degree course . What a total waste of money. I could have managed just fine with used or nowadays, digital copies. Always check online at stores like Amazon or Better World Books before succumbing to the campus bookstore. Even better, borrow the book from the library. By year three or so I figured this out and did quite well without books. I went to the library almost everyday, took good notes, photocopied pages I may have needed and went home. This forced me to study and saved money.


Living Arrangements

Obviously living at home would be an ideal situation but if it’s not an option, find roommates and share costs. While you may think you’ll need a nice big apartment for yourself you’ll end up spending 90% of your time out socializing, in your room pulling all nighters sleeping or somewhere like the library. As long as you have a room of your own to retire to at the end of the day for some Z’s and a little privacy, shared accommodation should work just fine. If you’ve been accepted into a specific program try to reach out to fellow students via Facebook, Craigslist or other social media outlets and see if anyone else is seeking roommates. Living with someone else within your program means live-in study-buddy!


Paying Tuition

If you’re responsible for funding your own way through post secondary, getting an early start with a part-time job is a must. If getting loans is inevitable, borrow only what you need! Depending on the program you get accepted to you may have an opportunity to borrow hundreds of thousands of dollars. Even with these funds being offered to you, if you don’t need them don’t borrow.

If you’re able to, make the most of your long summers off and work to save as much as possible. There are many summer job options to college students from working at resorts to manual labour jobs. It isn’t impossible to find a summer-only position. Capitalize on your summers to get a job somewhere you would like to travel to. Children’s summer camps are around the world and always looking for university students to work for them. See the world while getting paid, why not?  Plus, it helps you avoid college budget woes!

Though the primary focus of post secondary should always be academics, if you’re able to maintain a part-time job while in school, even better. Anything you can do to offset your monthly costs will help.


Budget

If you aren’t already, the most important thing you can do regarding your finances in post secondary is budget. This is especially important if you’re borrowing to pay for school, but even if your expenses are being taken care of by someone else, the monies still need to be accounted for and budgeted appropriately. Learning how to budget now will make the rest of your life much easier, trust me!

Graduating high school and embarking on a post secondary education is an exciting time. It is expensive but there are ways to help off set the costs. Enjoy your new adventures but watch your expenses!

What money saving tips do you have for college students?

Catherine
Catherine

Catherine is a first time momma to a rambunctious toddler. When she isn’t soaking up all that motherhood has to offer, you can find her blogging over at Plunged in Debt where she chronicles her and her husbands journey out of debt. You can also follow her on Twitter.

plungedindebt.com

Filed Under: Education, Money and Finances Tagged With: Money Saving Tips, Year College Students

  • Facebook
  • Pinterest
  • RSS
  • Twitter

Basic Principles Of Good Parenting

Here some basic principles for good parenting:

  1. What You Do Matters: Your kids are watching you. So, be purposeful about what you want to accomplish.
  2. You Can’t be Too Loving: Don’t replace love with material possessions, lowered expectations or leniency.
  3. Be Involved Your Kids Life: Arrange your priorities to focus on what your kid’s needs. Be there mentally and physically.
  4. Adapt Your Parenting: Children grow quickly, so keep pace with your child’s development.
  5. Establish and Set Rules: The rules you set for children will establish the rules they set for themselves later.  Avoid harsh discipline and be consistent.
  6. Explain Your Decisions: What is obvious to you may not be evident to your child. They don’t have the experience you do.
  7. Be Respectful To Your Child: How you treat your child is how they will treat others.  Be polite, respectful and make an effort to pay attention.
Best Parenting Blogs

Most Popular

Baby

9 Unusual Baby Names That Sound Like They Belong to Future CEOs

Evan Morgan
Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Target Store

Choking Incident Prompts Recall of 49,000 Target Gigglescape “Under the Sea” Popping Toys

Evan Morgan
Frustrated Girl

Why Some Students on the Spectrum Are Labeled With ODD

Evan Morgan
Coke Bottles

12 Things Kids Took to School in the ’70s That Would Never Be Allowed Today

Evan Morgan

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette