• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

Should a Teen Pay Rent After Turning 18 if They Still Live at Home?

October 3, 2026 | Leave a Comment

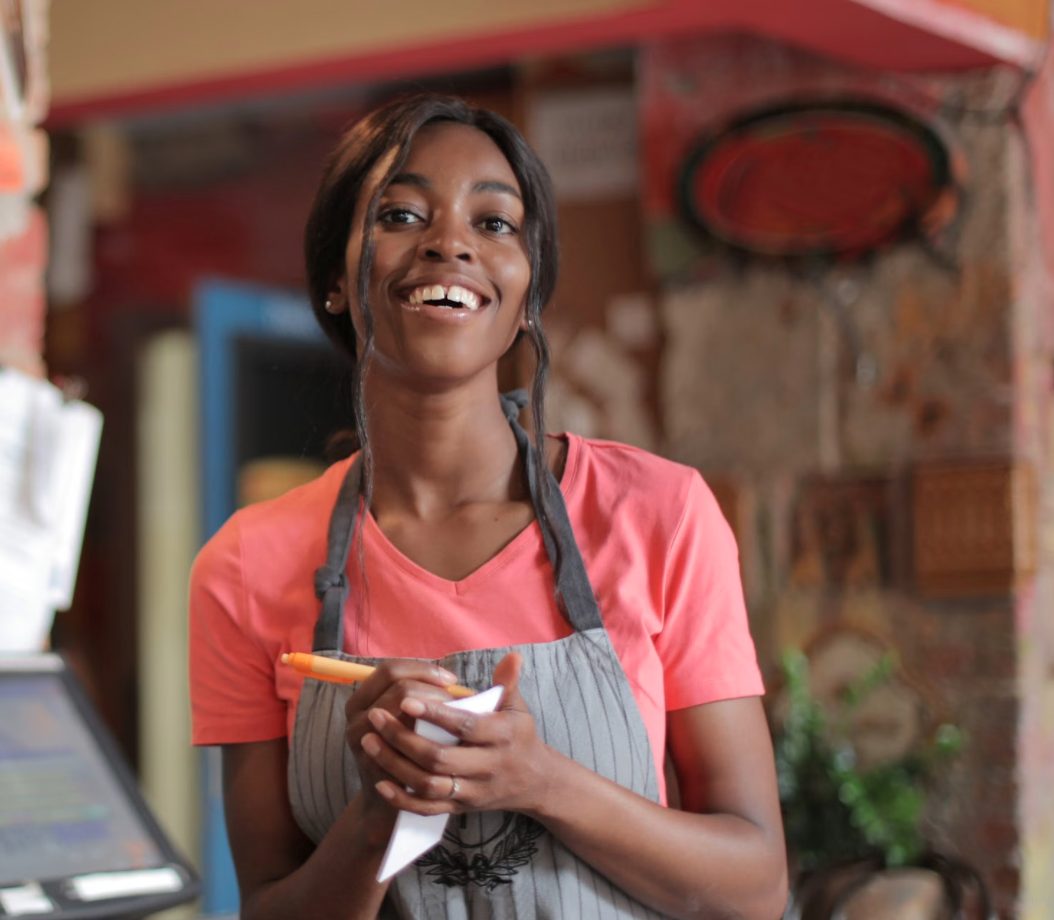
Working Teen
Turning 18 does not automatically mean a young adult is financially ready to leave home. A reasonable household contribution can teach budgeting while still giving teens room to save for college, emergencies, and eventual independence. (Pexels).

Turning 18 makes a teenager a legal adult, but it does not automatically make them financially independent. With housing, education, groceries, transportation, and insurance taking sizable bites out of young workers’ paychecks, many families are reconsidering what adulthood at home should look like. Recent research from Pew Research Center found that 57% of 18-to-24-year-olds live with a parent, so remaining home after high school is hardly unusual. The debate over whether a teen should pay rent after 18 is really about balancing responsibility with the opportunity to build a financial foundation. For many households, the best solution may fall somewhere between completely free housing and charging market-rate rent.

Living At Home Is Increasingly An Economic Strategy

High housing costs make living with parents a practical decision for many young adults rather than evidence that someone is refusing to grow up. A July 2026 analysis from the Urban Institute found that about 20% of Americans ages 25 to 34 live with their parents, nearly double the 11.8% recorded in 2005. Researchers also found that young adults are more likely to remain home in metropolitan areas with higher rents, even across different income levels. That matters when deciding whether a teen should pay rent after 18 because moving out prematurely can replace inexpensive family housing with rent, utilities, deposits, furniture, and other costs. Parents should therefore consider whether charging rent advances their child’s independence or simply makes saving enough to leave home harder.

A Contribution Does Not Have To Mean Market Rent

Parents who expect some financial participation are far from unusual, but writing a monthly rent check is only one option. Pew found that 72% of young adults living with parents contribute financially to their household, including 65% who help with groceries or utilities and 46% who contribute toward rent or the mortgage. A teenager earning $1,800 a month after taxes, for example, might pay $250 toward household expenses while putting $500 into savings and covering transportation and personal bills. That approach gives the young adult experience managing recurring obligations without consuming such a large percentage of income that saving becomes impossible. Families deciding whether a teen should pay rent after 18 should look at actual income and expenses instead of choosing an arbitrary amount.

Parents Should Protect Their Own Finances Too

Free housing can be generous, but parents should not provide it by jeopardizing retirement, emergency savings, or debt repayment. A Bankrate survey found that 61% of parents with adult children had made financial sacrifices to help them, including 37% who reported sacrificing retirement savings. That is an important hidden cost because parents approaching retirement have fewer working years available to rebuild depleted accounts. If another adult increases grocery, utility, insurance, transportation, or household costs by several hundred dollars monthly, requesting a reasonable contribution may protect the entire family. Before setting rent, parents should calculate what their adult child actually costs the household rather than treating the payment as punishment for reaching a birthday.

College And Early Careers Change The Equation

An 18-year-old attending school full time is in a different financial position from a 19-year-old working 40 hours a week with few personal expenses. The College Board reports average published in-state tuition and fees at public four-year colleges reached $11,950 for 2025-26, while public two-year in-district tuition averaged $4,150. Those figures exclude many everyday expenses, meaning charging substantial rent could force a student to work additional hours or borrow more money. Families might instead require smaller contributions, household chores, or measurable savings while the student remains enrolled and progressing toward a degree or credential. Whether a teen should pay rent after 18 should therefore depend partly on what that young person is actively doing to become self-supporting.

The Rent Can Become A Forced-Savings Tool

Parents who do not need their child’s contribution have another option: charge rent but quietly save some or all of it for the child’s future. For example, collecting $300 monthly for two years would produce $7,200 before any interest, potentially helping with a security deposit, emergency fund, reliable vehicle, or other move-out costs. The arrangement still teaches that housing carries a monthly cost while preventing the money from disappearing into everyday spending. Parents should decide beforehand whether they will eventually return the money and whether telling their child about the plan would undermine its budgeting lesson. Whatever approach is chosen, the amount, payment date, chores, savings expectations, guests, and target for eventual independence should be discussed clearly.

The Goal Should Be Independence, Not A Rent Check

There is no universal amount every family should charge when deciding whether a teen should pay rent after 18. A reasonable arrangement should reflect the young adult’s income, education plans, household costs, savings goals, and the parents’ financial situation rather than relying on age alone. Charging modest rent can teach budgeting and protect parents financially, while reduced or free rent can be equally productive when it allows a responsible young adult to finish school, eliminate debt, or accumulate meaningful savings. The strongest arrangement is one with a purpose, measurable expectations, and regular conversations about what comes next.

Would charging your 18-year-old rent prepare them for independence, or would helping them save that same money give them a stronger start—what would you do in your household? Share your thoughts in the comments.

What to Read Next

Living Alone and Working from Home? Here’s How to Stay Social

Should Parents Charge Adult Kids Rent When They Move Back Home?

Would You Charge Your Adult Child Rent If They Moved Back Home?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: adult children, budgeting, Cost of Living, family finances, financial independence, Parenting, personal finance, rent, Saving Money, teenagers

Would You Charge Your Adult Child Rent If They Moved Back Home?

September 19, 2026 | Leave a Comment

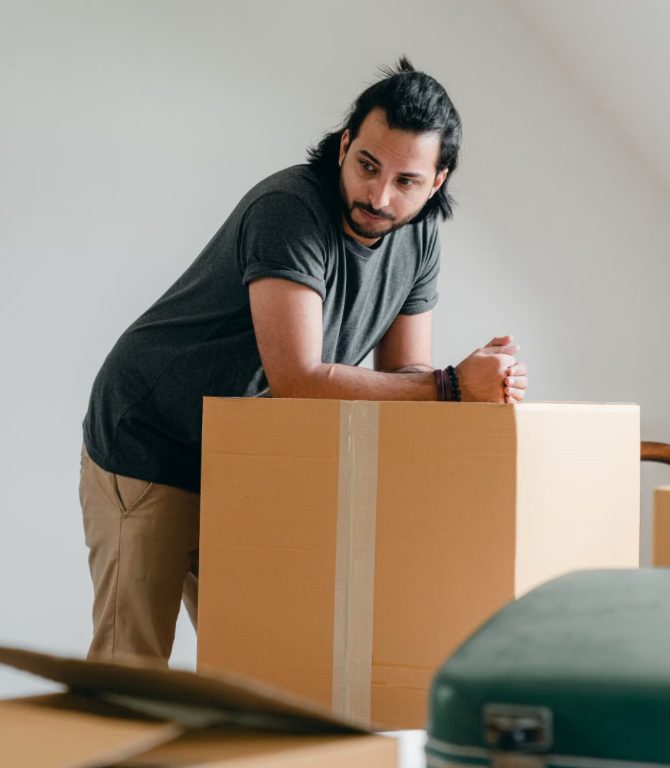
Man Moving
With typical U.S. rent still near $2,000 a month by one major measure, moving back home can give adult children valuable financial breathing room. Setting a fair household contribution can help them save without shifting the financial burden entirely to their parents. (Pexels).

Your adult child calls with a familiar request: Can I move back home for a while? With housing costs still elevated, returning to the family home can be a practical way to rebuild savings, pay down debt, or recover from a job change. But once the boxes arrive, another question can become surprisingly uncomfortable: Should parents charge adult child rent? The answer depends on the family’s finances, the child’s circumstances, and what everyone expects from the arrangement. Treating the decision like a financial agreement rather than an emotional test can prevent resentment later.

Moving Back Home Is More Common Than You Might Think

Living with parents well into adulthood is hardly unusual in today’s housing market. A 2025 Pew Research Center analysis found that 18% of Americans ages 25 to 34 were living in a parent’s home in 2023, with substantial differences across metropolitan areas. Meanwhile, Realtor.com’s August 2026 rental report put the median asking rent for studios through two-bedroom homes across the 50 largest metros at $1,699 a month. Although that figure was down 0.9% from a year earlier, it remained 15.4% above its August 2019 level. For someone trying to establish financial stability, moving home can therefore create breathing room that even a modest adult child rent would preserve.

Charging Rent Does Not Have To Mean Charging Market Rent

Parents do not have to choose between letting a child live completely free and demanding the same rent a landlord would charge. Pew Research Center research found that 72% of young adults living with a parent contributed financially to the household in some way, including 46% who contributed toward rent or the mortgage. A reasonable adult child rent could instead reflect added groceries, utilities, internet use, and household expenses while still allowing the child to save. For example, charging $500 monthly instead of a market-rate apartment approaching $1,700 could leave roughly $1,200 each month available for debt repayment, emergency savings, or a future security deposit. The important point is that parents should calculate what the additional person actually costs the household instead of choosing an arbitrary number.

Free Housing Can Carry A Hidden Cost For Parents

Allowing an adult child to live rent-free feels generous, but generosity becomes risky when parents begin subsidizing the arrangement from money intended for their own future. A Bankrate survey found that 61% of parents with adult children had made or were making financial sacrifices to help them, while 43% reported sacrificing emergency savings and 37% retirement savings. Those numbers highlight an important boundary: parents should not raid a 401(k), carry credit-card balances, or postpone essential expenses simply to avoid discussing rent. Before agreeing to free housing, calculate the added monthly cost of food, electricity, water, transportation, insurance, and other expenses the arrangement may create. If another adult adds $350 to household spending each month, asking for a $350 contribution may simply prevent the parents from quietly absorbing $4,200 a year.

Rent Can Become Part Of A Bigger Financial Plan

The strongest arrangement may be one in which rent has a specific purpose rather than functioning as punishment for moving home. Parents could charge $500 a month while requiring their child to save another $500, creating $6,000 in personal savings after one year while still contributing $6,000 toward household costs. That matters because housing remains expensive even after recent rent declines: Zillow’s August 2026 analysis estimated typical U.S. rent at $1,948 per month. Families should decide whether the goal is covering expenses, encouraging financial responsibility, building savings, paying down debt, or establishing a move-out fund before setting the amount. Parents who can comfortably afford the household expenses might even privately save some or all of the rent and later return it toward a deposit, although they should avoid promising that unless they are certain they can follow through.

Put The Rules In Writing Before The Boxes Arrive

Money is only one part of living together, which is why a simple written household agreement can prevent arguments over expectations. It should spell out the adult child rent, payment date, groceries, chores, guests, parking, privacy, shared spaces, and what happens if a payment is missed. Families should also establish a review date—perhaps after three or six months—rather than leaving the arrangement indefinitely open-ended. This is particularly relevant when 87% of Americans in a May 2026 Pew Research Center survey said buying a home is harder for young adults today than it was for their parents’ generation, while 82% said saving for the future is harder. Parents should also check applicable state and local landlord-tenant rules before assuming that calling someone “family” automatically eliminates legal considerations surrounding a long-term living arrangement.

The Best Arrangement Protects Both Generations

Charging an adult child rent does not have to communicate, “You’re on your own,” just as free housing does not automatically represent better parenting. A workable arrangement gives the adult child an opportunity to improve financially without forcing parents to jeopardize emergency savings, retirement contributions, or their monthly budget. Start by asking three questions: What does having another adult at home actually cost, what financial goal is the child working toward, and how long is the arrangement expected to last? Then choose a contribution that fits those answers and revisit the agreement as circumstances change.

Would you charge your adult child rent, let them live completely free, or collect rent and secretly save it for their future—and why? Share your approach in the comments.

What to Read Next

5 Things to Consider Before Moving Your Parents Into Your Home

Should Parents Charge Adult Kids Rent When They Move Back Home?

Value Killer: 5 Home Renovations Decreasing Kids’ Safety

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: adult children, budgeting, family finances, financial independence, housing costs, multigenerational living, Parents, personal finance, rent, Saving Money

Should Parents Charge Adult Kids Rent When They Move Back Home?

August 21, 2026 | Leave a Comment

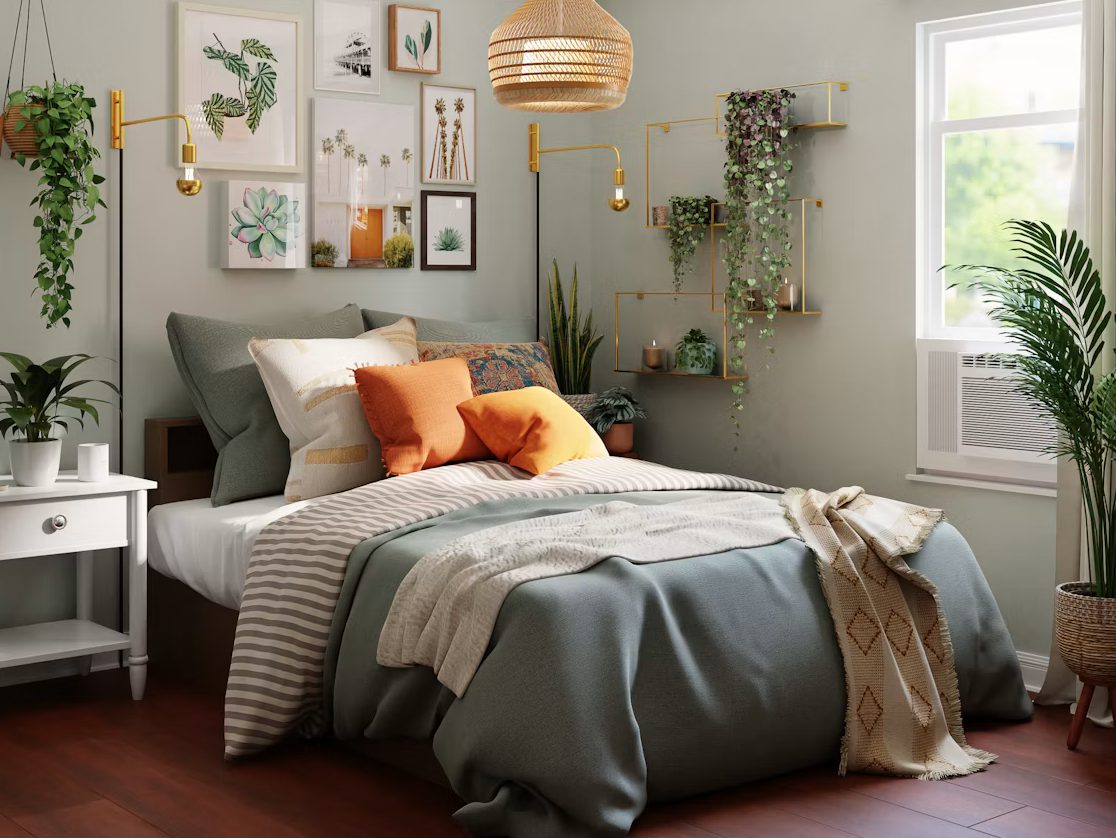
Bedroom
As more adult children live with their parents, families are deciding whether charging rent can protect household finances while helping young adults build independence. A clear plan for rent, savings, expenses, and a move-out goal can help both generations know what to expect. (Unsplash).

Moving back home as an adult is no longer unusual. In 2023, 18% of Americans ages 25 to 34 lived in a parent’s home, according to Pew Research Center, and housing costs, job changes, student debt, divorce, and saving for a home can all make returning to the family home financially attractive. For parents, however, opening the door raises an uncomfortable question: Should you charge your adult child rent or give them a financial break? There is no universal dollar amount that works for every household, but there is a useful rule: The arrangement should improve the adult child’s financial position without damaging the parents’ financial security. Done thoughtfully, rent can create structure and independence without turning Mom and Dad into landlords.

Charging Rent Can Protect the Parents’ Finances

Before deciding that living at home will be free, calculate what another adult actually adds to groceries, utilities, transportation, insurance, subscriptions, and other household expenses. That is particularly important for parents approaching retirement, when there may be fewer working years available to replenish money spent supporting an adult child. A Bankrate survey of parents with adult children found 61% had made financial sacrifices to help their children, including 43% who sacrificed emergency savings, 41% who delayed paying down debt, and 37% who sacrificed retirement savings. If an employed 28-year-old is living rent-free while a 60-year-old parent reduces retirement contributions to cover the increased household costs, the arrangement deserves another look. Parents should establish what they can genuinely afford to contribute before deciding what their adult child should pay.

Rent Should Have a Purpose, Not Just a Price

Charging $500 because “$500 sounds fair” misses an important opportunity to decide what the living arrangement is supposed to accomplish. Is the adult child trying to eliminate $15,000 in credit-card debt, accumulate a $20,000 apartment or home fund, recover financially after divorce, or simply find cheaper housing indefinitely? A 26-year-old earning $3,500 a month might, for example, pay $500 toward household costs while automatically saving another $700 toward moving out. Pew found that financial contributions are already normal among young adults living with parents: 72% contribute financially in some way, including 65% who help with household expenses and 46% who contribute toward rent or the mortgage. A good rent arrangement should therefore answer two questions at once: What is fair to the parents, and how is this helping the adult child become more financially independent?

Sometimes Charging No Rent Is the Smarter Choice

There are circumstances when charging rent can actually slow the goal everyone is trying to achieve. Suppose your daughter can afford $800 a month, but she has $8,000 of high-interest credit-card debt and agrees to put that entire $800 toward the balance while living at home. Giving her a temporary rent-free window could potentially get her out of expensive debt faster than collecting household rent and leaving the card balance lingering. Pew found that 64% of young adults living with parents said doing so had a positive impact on their personal finances, suggesting that moving home can genuinely function as a financial reset. The key word is temporary: “Stay here free until you get back on your feet” is vague, while “Stay rent-free for six months while paying $800 monthly toward your credit card” creates a measurable plan.

Use a Simple Test to Decide What the Rent Should Be

Instead of automatically using the local market rent for a bedroom, start with the parents’ actual financial situation. Calculate the additional household costs created by another adult, determine whether the parents need a contribution to avoid subsidizing those expenses, and then consider the child’s income and financial objective. For example, parents spending an additional $350 a month because their son moved home might charge $400 or $500 rather than the $1,200 he would pay for an apartment, leaving him significant room to save while preventing his parents from absorbing the expense. Alternatively, financially secure parents might charge more and secretly save some of the rent to return later, although that strategy should not replace teaching the child to save independently. The right amount is not necessarily the highest amount the parents could charge; it is an amount that protects both generations while supporting the purpose of the move.

Don’t Let Helping Your Child Delay Your Own Retirement

This deserves more emphasis than the original draft gives it because parents can recover from many financial decisions more easily than they can recover lost retirement years. A 30-year-old moving home potentially has decades of earnings ahead, while parents in their late 50s or 60s may be approaching the end of their highest-earning years. Fidelity’s 2026 guidance for parents with adult children living at home specifically recommends understanding your own income, expenses, and retirement needs before deciding how much support you can provide. Parents should be especially cautious if supporting an adult child requires withdrawing from retirement accounts, stopping retirement contributions, carrying credit-card balances, draining emergency savings, or postponing debts they need to eliminate before retiring. Generosity makes considerably less financial sense when Mom and Dad may eventually need financial assistance from the same children they are supporting today.

What If Your Adult Child Can Afford Rent but Doesn’t Want to Pay It?

An employed adult living at home indefinitely presents a different situation from someone recovering from a layoff or trying to escape high-interest debt. If your child has enough disposable income for frequent travel, restaurant meals, expensive electronics, or a new vehicle but says contributing to household expenses is unaffordable, the disagreement may be about priorities rather than income. Parents do not have to subsidize discretionary spending simply because their child would rather use earnings elsewhere. A reasonable household contribution can help recreate one financial reality of independent adulthood: housing and utilities have to be paid before entertainment and lifestyle upgrades. That does not require charging market rent, but it does require both generations to agree that living at home is financial assistance rather than an unlimited entitlement.

Put the Agreement in Writing Before the Moving Boxes Arrive

Money is only one source of friction when an adult child returns home, so establish the entire arrangement beforehand. Fidelity recommends setting clear financial and nonfinancial expectations, including household contributions, chores, meals, savings goals, and how long the arrangement is expected to last. A simple agreement could say the child pays $500 on the first of every month, saves at least $750 monthly, buys groceries twice a month, handles certain chores, and sits down with the parents after six months to review progress. Privacy deserves similar clarity because an adult returning home should not automatically become the 16-year-old who once occupied the same bedroom. Discuss guests, overnight visitors, shared spaces, food, parking, chores, quiet hours, pets, and other predictable sources of conflict before everyone is irritated by them.

Add an Exit Goal, Not Just an Exit Date

“You’re moving out in one year” sounds clear, but financial milestones can make the arrangement more productive. A child might agree to move when she has eliminated $10,000 of debt and accumulated a $6,000 emergency fund, or when she has saved enough for a security deposit, moving expenses, and three months of basic expenses. Parents and adult children can then review progress every few months rather than waiting until month 11 to discover that little has changed. If circumstances change because of unemployment, illness, or another legitimate setback, the plan can change too. The goal is not to rush someone out of the house; it is to prevent temporary assistance from drifting into permanent dependence without anyone consciously choosing it.

Consider the “Rent Now, Gift Later” Strategy Carefully

Some parents choose to charge rent and quietly save the money, intending to return it when their child buys a home or moves out. Fidelity describes exactly this type of strategy in its discussion of adult children returning home, although the family featured ultimately chose another approach. It can create a useful forced-savings windfall, but there is also an argument for telling the adult child to build those savings personally so they learn to manage the money themselves. Parents who intend to return a significant amount should also consider whether there could be tax or estate-planning implications based on the amount and circumstances. Either approach can work, but it should fit the larger objective rather than becoming another financial secret between parents and their adult child.

The Best Arrangement Should Leave Both Generations Better Off

There is no universal answer to whether parents should charge adult kids rent because a struggling 22-year-old graduate, a 29-year-old saving for a first home, and an employed 38-year-old moving home indefinitely present very different situations. What matters is whether the arrangement protects the parents’ emergency savings and retirement while helping the child make measurable progress toward financial independence. Before anyone moves in, answer five questions: How much will the child contribute, what will they save or pay down, what household responsibilities will they assume, how long is the arrangement expected to last, and what does successful moving out look like? If nobody can answer those questions, deciding whether rent should be $0, $400, or $800 is probably premature.

If your adult child moved home tomorrow, would you charge rent, offer free housing with conditions, or create another arrangement—and why?

What to Read Next

43% of Parents Would Go Into Debt to Help Their Kids Fit In — 7 Money Traps to Avoid

Youth Sports Cost Families $1,016 a Year on Average — 8 Expenses New Parents Don’t Expect

Should Kids Get Paid for Good Grades? What Parents Should Consider Before Offering Cash

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: adult children, family finances, financial independence, living at home, money management, multigenerational households, Parenting, personal finance, rent, Retirement

  • Facebook
  • Pinterest
  • RSS
  • Twitter

Basic Principles Of Good Parenting

Here some basic principles for good parenting:

  1. What You Do Matters: Your kids are watching you. So, be purposeful about what you want to accomplish.
  2. You Can’t be Too Loving: Don’t replace love with material possessions, lowered expectations or leniency.
  3. Be Involved Your Kids Life: Arrange your priorities to focus on what your kid’s needs. Be there mentally and physically.
  4. Adapt Your Parenting: Children grow quickly, so keep pace with your child’s development.
  5. Establish and Set Rules: The rules you set for children will establish the rules they set for themselves later.  Avoid harsh discipline and be consistent.
  6. Explain Your Decisions: What is obvious to you may not be evident to your child. They don’t have the experience you do.
  7. Be Respectful To Your Child: How you treat your child is how they will treat others.  Be polite, respectful and make an effort to pay attention.
Best Parenting Blogs

Most Popular

Baby

9 Unusual Baby Names That Sound Like They Belong to Future CEOs

Evan Morgan
Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Target Store

Choking Incident Prompts Recall of 49,000 Target Gigglescape “Under the Sea” Popping Toys

Evan Morgan
Frustrated Girl

Why Some Students on the Spectrum Are Labeled With ODD

Evan Morgan
Coke Bottles

12 Things Kids Took to School in the ’70s That Would Never Be Allowed Today

Evan Morgan

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette