• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

7 Things Parents Should Stop Buying New Every School Year

September 3, 2026 | Leave a Comment

Students With Backpacks
Before back-to-school shopping, parents can inspect backpacks, lunch containers, clothing and school supplies they already own. Reusing functional items can help families cut unnecessary expenses. (Pexels).

Back-to-school shopping can make even a careful parent feel like their wallet has sprung a leak. In 2026, families with K-12 students are expected to spend an average of $863.86 on clothing, shoes, school supplies, and electronics, according to the National Retail Federation. But a new school year does not automatically mean everything your child owns needs to be replaced. Before filling your cart, take inventory of what still works and consider making “buy new only when necessary” your new back-to-school rule.

1. Backpacks

A sturdy backpack can often survive several school years, particularly if the zippers, straps, and seams are still in good condition. Before buying a replacement, empty last year’s bag, wash or wipe it according to its care instructions, and inspect the high-stress areas for damage. If your child complains that the backpack looks old, remember that appearance alone does not make it unusable. A backpack that comfortably holds school supplies and fits properly can continue doing its job for another year. Reusing it can also teach children that “new” and “necessary” are not the same thing.

2. Lunch Boxes And Reusable Containers

Parents do not necessarily need to replace lunch boxes and reusable food containers every August simply because a new school year begins. If the lunch bag can be thoroughly cleaned and the containers remain intact, there may be plenty of life left in them. Check for cracked plastic, broken seals, damaged insulation or lingering odors that cleaning cannot remove before deciding. The same principle applies to reusable water bottles, which can be kept when they remain safe, functional, and easy to clean. Reusing these everyday items can reduce both shopping costs and household waste.

3. Binders And Folders

Binders are another classic example of something parents may replace unnecessarily. If a binder still closes securely, holds paper properly, and has functioning rings, it may only need a quick cleaning before returning to school. Folders can also be reused when they are not torn, excessively bent or covered with old information that could cause confusion. Instead of buying a complete new set, let your child identify which supplies are genuinely worn out. This small inventory can turn last year’s leftovers into instant savings.

4. Basic School Supplies

Pens, pencils, rulers, scissors, pencil cases, and other basic supplies do not magically expire when summer vacation begins. The Environmental Protection Agency recommends checking existing school materials before shopping because many supplies can be reused or recycled. A quick household “school supply sweep” might uncover unopened notebooks, several perfectly good pencils, and enough folders to eliminate part of the shopping list. Even small savings matter when you are buying for multiple children, especially as some school supplies have become more expensive. Forbes Advisor recently reported increases in items including notebooks, index cards, notebook paper, and scissors.

5. Clothes That Still Fit

A new grade level does not require an entirely new wardrobe if last year’s clothes still fit and remain wearable. Start by pulling everything from closets and drawers, then separate items into keep, repair, donate, and replace piles. A child who needs three new shirts does not necessarily need ten, particularly when clean, comfortable clothes already exist at home. This approach also creates an opportunity to buy better-quality replacement pieces rather than rushing into a large shopping spree. If children have outgrown clothing, donating usable pieces or passing them to younger siblings can extend their value instead of sending them straight to the trash.

6. Shoes That Aren’t Worn Out

Shoes deserve a little more scrutiny than shirts because worn soles, poor fit, or damaged support can affect comfort and safety. However, if last year’s shoes still fit properly, have adequate tread, and show no significant structural damage, there may be no reason to replace them simply because school is starting. Have your child try them on with the socks they normally wear and check for tightness around the toes and heel. Children can grow quickly, so this is one category where replacing an item because it no longer fits is completely reasonable. The goal is not to avoid spending money at all, but to spend it where the need is real.

7. Electronics That Still Work

A new school year can create pressure to upgrade headphones, tablets, calculators, or computers, but functioning technology does not automatically become obsolete in September. First, check the school’s actual requirements and whether the device your child already owns meets them. If the battery, software, storage, and physical condition remain adequate, an upgrade may simply be an expensive want rather than a school necessity. This matters because electronics are one of the biggest K-12 back-to-school spending categories, with the NRF estimating $293.11 per shopper in 2026. Spending that money only when an actual need exists can leave more room in the family budget for unavoidable expenses.

Make “Use What You Have” The New Back-To-School Habit

The smartest back-to-school shopping strategy may be surprisingly simple: shop your home before shopping the store. NerdWallet’s 2026 survey found that 62% of back-to-school shoppers planned to shop sales, while 21% planned to seek free school supplies and 19% planned to buy at least some clothing secondhand. Reusing what you already own does not mean your child has to miss out; it means distinguishing between something that needs replacing and something that merely feels new. Before buying, make three lists: what you already have, what needs replacing and what can wait until later.

Which school item do you plan to reuse this year, and what money-saving strategy has worked best for your family? Share your thoughts in the comments.

What to Read Next

The $20 School Fundraiser Question: How Many Times Are Parents Expected to Say Yes?

Why “Back to School” Shopping Feels Like a Mortgage Payment Now

5 Ideas For Back To School Photos

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Back To School Shopping, back-to-school tips, budgeting, family finances, frugal living, Parenting, parenting tips, Saving Money, school supplies

The $20 School Fundraiser Question: How Many Times Are Parents Expected to Say Yes?

August 28, 2026 | Leave a Comment

Group Of Girls
Repeated $20 school fundraiser requests can quickly become a significant household expense when added to supplies, activities, and other school-year costs. Setting an annual giving budget can help parents support their school without putting unnecessary pressure on family finances. (Pexels).

Another $20 school fundraiser lands in your inbox, and at first, it does not seem like a major expense. Then you remember the fun run, teacher wish list, sports donation, book fair, and classroom collection that already appeared this semester. For many families, the problem is not one $20 request but how quickly repeated requests add up. A 2026 NerdWallet survey found that 51% of parents with children in K-12 or college feel overwhelmed by financial requests from their children’s schools. That raises an uncomfortable question: How many times should parents really be expected to say yes?

The Small Requests Can Become A Big Expense

Twenty dollars sounds manageable until a family receives 10 similar requests, turning a seemingly minor contribution into $200. Add multiple children, and the annual total can climb even faster, particularly when fundraising overlaps with activity fees, uniforms, supplies, and field trips. NerdWallet found that parents of K-12 or college students plan to spend an average of $531 on broader school-community costs, including fundraising, teacher wish lists, and crowdfunded classroom supplies. That comes on top of ordinary back-to-school expenses families already face. A school fundraiser may support something worthwhile, but parents still need to consider the cumulative cost.

Parents Are Already Spending Heavily On School

Fundraising does not happen in a financial vacuum, especially when families are paying hundreds of dollars just to prepare children for school. Deloitte’s 2025 Back-to-School Survey estimated that K-12 parents planned to spend an average of $570 per student on back-to-school purchases. Nine in 10 surveyed parents also expected to enroll their children in extracurricular activities, spending an average of $532 per child on fees and equipment. Those numbers help explain why another school fundraiser can feel much bigger than the amount printed on the donation form. Families should look at their entire school-year budget rather than treating every new request as an isolated expense.

There Is No Required Number Of Yeses

Parents may feel social pressure when classmates participate or fundraising messages emphasize reaching a schoolwide goal, but families should establish their own limits. A useful approach is deciding at the beginning of the school year how much money is available for optional school giving. A household might budget $100, for example, and divide it among the causes that matter most rather than automatically giving $20 every time. Once that amount is spent, saying no to another school fundraiser becomes a budget decision rather than a judgment about the cause. Parents should never feel obligated to sacrifice groceries, bills, savings, or debt payments to meet an optional fundraising request.

Fundraising Fatigue Can Hurt Schools Too

Schools and parent organizations have reasons to be cautious about repeatedly approaching the same families. PTO Today advises groups to consider a community’s income levels and available time when choosing fundraisers, while also clearly explaining what the money will support. The organization has also warned that running too many fundraisers can reduce parent involvement. That makes sense because families who feel constantly solicited may eventually stop opening fundraising emails altogether. A well-planned school fundraiser with a clear purpose may generate more goodwill than several smaller campaigns competing for attention.

Not Every Family Can Give The Same Amount

One potential problem with school fundraising is the assumption that every household has similar financial flexibility. A 2026 national study of 2,474 parents found that about 28% reported making a K-12-related charitable donation during the previous 12 months, with contributions varying considerably. The reality is that $20 may be pocket change for one household and part of the grocery budget for another. Schools can reduce awkwardness by making contributions genuinely optional and avoiding rewards that publicly highlight which children raised the most money. Fundraising should strengthen a school community rather than create embarrassment for families who cannot participate financially.

Saying No Does Not Mean You Do Not Support The School

Parents can contribute to a school community without reaching for their wallets every time a request arrives. Volunteering at an event, donating an unused item, helping with setup, or sharing professional skills can sometimes be just as valuable. Families can also choose one or two causes they strongly support and politely decline the rest. If a school fundraiser does not explain where the money is going, parents are reasonable to ask about its goal before contributing. Giving intentionally can make participation feel meaningful instead of turning fundraising into another recurring bill.

Your Family Gets To Set The Limit

There is no universal answer to how many $20 requests are too many because household budgets and school communities vary widely. The better question is whether each contribution fits comfortably within your family’s financial priorities and whether you understand what your money will support. Schools benefit when parents participate, but sustainable support depends on families feeling respected rather than pressured. Set an annual giving limit, choose the causes that matter most, and give yourself permission to decline when that limit has been reached.

How many school fundraiser requests would it take before you started saying no, and should schools place limits on how often families are asked to contribute? Share your thoughts in the comments.

What to Read Next

7 School Fundraising Scams That Parents Are Tired Of

The 7 School Fundraisers That Quietly Cost Parents the Most (And What to Skip)

Teachers Support It: Why Parents Are Boycotting Class Gift Funds in 2026

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: back-to-school costs, education costs, Family Budget, Parenting, Parents, PTO fundraising, Saving Money, school expenses, school fundraiser, school fundraising

7 Things Parents Should Never Drain Their Emergency Fund to Buy for Their Kids

August 25, 2026 | Leave a Comment

Parent Paying
Parents may want to give their children everything from new cars to dream weddings, but those purchases should not come at the expense of the family’s financial safety net. Keeping emergency savings intact can help protect the household when a true crisis arrives. (Pexels).

Parents naturally want to give their children opportunities, memorable experiences, and things that make life easier. But generosity can become financially dangerous when it means emptying savings meant for a job loss, major repair, or other genuine crisis. Bankrate reported in January 2026 that only 30% of Americans said they would cover a $1,000 emergency expense from savings, highlighting how fragile many household safety nets remain. An emergency fund for parents should protect the entire household when something unexpected happens, not serve as a shortcut for purchases that can be planned or scaled down.

1. A Brand-New Car

Handing a teenager or young adult keys to a new car can feel like an incredible gift, but the financial commitment extends far beyond the purchase price. AAA’s latest analysis puts the average annual cost of owning and operating a new vehicle at $11,577, including expenses such as depreciation, insurance, fuel, and maintenance. A reliable used vehicle, shared family car, or contribution toward a child’s independently funded purchase may accomplish the same goal without wiping out savings. Parents should also consider whether their child can afford ongoing insurance, repairs, registration, and fuel. An emergency fund for parents is too valuable to exchange for a rapidly depreciating asset.

2. An Expensive Wedding

Helping a child celebrate a wedding can be meaningful, but parents do not need to jeopardize their financial security to create a beautiful day. The Knot’s 2026 Real Weddings Study found that couples who married in 2025 spent an average of $34,200, although actual costs varied considerably. Parents should decide what they can comfortably contribute before venues, catering packages, and guest lists begin expanding the bill. Offering $5,000 from designated savings is very different from pulling $20,000 out of emergency reserves. A wedding lasts a day, while the financial consequences of depleted savings can linger for years.

3. Luxury Electronics And Upgrades

A premium smartphone, gaming computer, or tablet may seem essential when classmates already have the newest models. Yet Consumer Reports notes that premium phones can easily exceed $1,000 while strong alternatives are available for under $600. Parents can establish a technology budget, consider refurbished devices, or require older children to contribute toward upgrades. Replacing a genuinely broken device needed for school may be necessary, but choosing the most expensive version usually is not. Protecting an emergency fund for parents should take priority over keeping up with technology trends.

4. A Dream College At Any Cost

Education is an investment, but parents should carefully separate college savings from emergency savings. College Board reports average published 2025-26 tuition and fees of $11,950 for in-state students at public four-year colleges and $45,000 at private nonprofit four-year institutions. Families can compare financial-aid offers, scholarships, community college pathways, and lower-cost universities before spending emergency reserves. Students may understandably prefer a particular campus, but preference alone does not make the expense a financial emergency. Parents still need protection against layoffs, home repairs, and unexpected bills while tuition payments are coming due.

5. Designer Clothes And Status Purchases

Teenagers can feel intense pressure to own the shoes, handbags, watches, and clothing popular among their peers. Those feelings are real, but financing status from emergency savings creates the wrong trade-off. Give children a clothing budget and let them decide whether one expensive item is worth sacrificing several affordable purchases. Older teens can also save earnings from part-time work when they want something beyond the family’s normal budget. An emergency fund for parents exists to preserve household stability, not finance social competition.

6. An Elaborate Graduation Or Birthday Celebration

Milestone birthdays and graduations deserve recognition, but memorable does not have to mean expensive. A family might easily spend thousands on venue rental, catering, decorations, entertainment, and professional photography when a smaller gathering would be equally meaningful. Set the celebration budget using current disposable income or money saved specifically for the event. If paying the bill means losing the cash needed for an unexpected furnace replacement or insurance deductible, the party is too expensive. Children benefit more from financially stable parents than from one spectacular celebration.

7. A Child’s Business Idea Without A Financial Plan

Supporting an entrepreneurial child can be exciting, especially when the idea appears promising. However, enthusiasm should not turn the family’s emergency fund into unprotected startup capital. Ask for a basic business plan covering startup costs, customers, pricing, expected revenue, and how much the child can contribute personally. Parents who want to help can provide a predetermined amount they could afford to lose without affecting essential savings. Treating an emergency fund for parents as investment capital removes the safety net exactly when a separate household emergency could strike.

Protect The Safety Net That Protects Your Family

Fidelity recommends starting with $1,000 in emergency savings and eventually building enough to cover three to six months of essential expenses. That money is designed for genuine financial shocks, such as lost income or unavoidable unexpected expenses, rather than predictable wants. Saying “not from our emergency savings” does not mean parents cannot help their children; it means finding an affordable way to help. Separate savings accounts for college, cars, weddings, and other goals can make those decisions much easier.

What would you refuse to drain your family’s emergency fund to buy for your kids, and where should parents draw the line? Share your thoughts in the comments.

What to Read Next

Your Child Got Birthday Money — Should You Let Them Spend All of It?

6 Money Rules Every Family Should Set Before a Teen Starts Driving

43% of Parents Would Go Into Debt to Help Their Kids Fit In — 7 Money Traps to Avoid

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: budgeting, emergency savings, family finances, financial planning, money management, Parenting, personal finance, Saving Money

7 Things Parents Buy Because Other Parents Have Them — Not Because Their Kids Need Them

August 24, 2026 | Leave a Comment

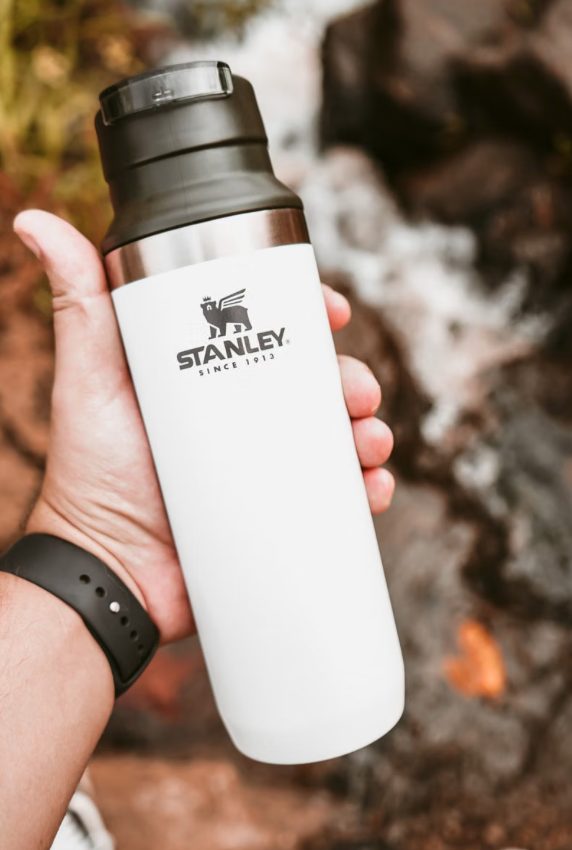
Stanley Tumbler
From trendy water bottles and tablets to designer clothes and high-tech gadgets, parents can easily spend money on products their children don’t truly need. Pausing to separate genuine needs from social pressure can protect the family budget while teaching children a valuable lesson about comparison. (Pexels).

Parenting has always come with a certain amount of comparison, but social media, school pickup lines, birthday parties, and group chats can make it feel impossible to ignore what other families own. Suddenly, an ordinary backpack seems inadequate because three classmates have a trendy one, or a perfectly functional stroller looks outdated beside the premium models at the playground. That pressure can lead to unnecessary kids’ purchases that drain the family budget without making childhood meaningfully better. Before buying the next must-have item, it helps to ask one simple question: Does my child actually need this, or do I just keep seeing it everywhere?

1. The Latest Trendy Water Bottle

A reusable water bottle is practical, but children rarely need a collection of expensive bottles simply because certain brands become playground status symbols. Parents.com has reported on children feeling social pressure over popular Stanley tumblers, showing how quickly an everyday object can become tied to fitting in. A $10 bottle that doesn’t leak and keeps water accessible can perform the same basic job as a significantly pricier viral version. If your child’s current bottle works, replacing it primarily because classmates have another brand is a classic example of unnecessary kids’ purchases. Parents can acknowledge that trends are fun while still teaching children that owning a particular logo isn’t a requirement for belonging.

2. A Personal Tablet Before It Is Necessary

Seeing other children carrying tablets on road trips or at restaurants can make parents wonder whether their own child is missing something. The American Academy of Pediatrics’ latest digital-media guidance recommends considering children’s maturity, content, communication, and what screen use may displace rather than treating devices as automatic childhood necessities. For younger children especially, a shared family device may provide occasional entertainment or educational access without immediately purchasing another screen. Before spending hundreds of dollars, decide exactly what problem a personal tablet would solve and what rules would accompany it. Otherwise, it can become one of those unnecessary kids’ purchases made because technology seems universal rather than because the child genuinely needs it.

3. Too Many Specialized Baby Gadgets

First-time parents are particularly vulnerable to comparison because every stroller walk, parenting video, and baby registry can introduce another supposedly essential product. Babylist’s 2026 survey of first-time parents found commonly regretted items included bottle sterilizers, wipes warmers, baby food makers, bottle warmers, and baby floor seats. One parent may swear by a bottle warmer while another discovers that their baby happily drinks room-temperature or cold milk, which is why copying another household’s setup can backfire. Buying gradually gives parents time to learn their baby’s preferences before filling cabinets with specialized equipment. This wait-and-see strategy can reduce unnecessary kids’ purchases while leaving money available for products the family actually uses.

4. Designer Or Trend-Driven Children’s Clothing

Children need comfortable, weather-appropriate clothes, but they don’t need an entirely new wardrobe whenever a particular sneaker, jacket, or matching set becomes fashionable. The pressure often becomes noticeable once children enter school and start comparing labels, characters, and styles with classmates. Before paying premium prices, parents can calculate cost per wear: a $70 outfit worn twice before a growth spurt effectively costs $35 each time. Save expensive pieces for situations where durability or frequent use justifies the price, and use affordable basics for everyday play. Avoiding unnecessary kids’ purchases doesn’t mean children can never enjoy trends; it means trends don’t automatically dictate the household budget.

5. Elaborate Birthday Party Extras

A child’s birthday can quietly turn into a competition when parents see rented backdrops, balloon installations, custom cookies, entertainment, elaborate favors, and coordinated decorations at other parties. None of those extras is inherently wrong, but they can make a simple celebration feel inadequate even when children would be delighted with pizza, cake, games, and friends. Establishing a total party budget before browsing social media or vendors helps prevent individual upgrades from accumulating into a surprisingly large bill. Ask the birthday child which two or three elements matter most, because their answers may be far simpler than adults expect. Cutting unnecessary kids’ purchases from the party can also free up money for an experience, savings, or a gift the child will enjoy longer.

6. Smart Devices With Features Kids Rarely Use

Smartwatches, connected toys, and other tech can offer useful features, but purchasing them simply because families around you have them deserves a second look. Common Sense Media notes that smart products may collect information and recommends examining privacy settings, data practices, and security updates before bringing connected devices into the home. Parents should identify the specific benefit they need, such as communication after school, rather than paying for an extensive feature list a child may barely touch. A simpler device may accomplish the same goal with fewer distractions and potentially fewer privacy concerns. When technology lacks a clear purpose, it can quickly join the pile of expensive unnecessary kids’ purchases.

7. Multiple Versions Of Gear That Does The Same Job

Parents can accumulate surprising amounts of duplicate gear because another family’s solution looks more convenient than what they already own. Think multiple strollers, several diaper bags, overflowing toy-storage systems, or different seats and soothing devices intended for nearly identical situations. Babylist’s updated minimalist guidance recommends favoring products that are multifunctional, work in small spaces, or grow with children rather than repeatedly buying separate single-purpose items. Before purchasing, ask what the new product accomplishes that something already in your home cannot. If the answer is mostly that the newer version looks better online or everyone else seems to have one, waiting 48 hours can prevent an impulse buy.

Your Child Needs Your Judgment More Than The Latest Trend

There is nothing wrong with buying something simply because it is fun, stylish, or convenient when it comfortably fits the family budget. The problem begins when comparison turns optional spending into an obligation and parents feel that saying no somehow shortchanges their children. Avoiding unnecessary kids’ purchases is ultimately about separating genuine family needs from social pressure, advertising, and the fear of being different. A useful habit is to pause before nonessential purchases and ask whether you would still want the item if you had never seen another parent owning it.

Which children’s product have you bought because everyone else seemed to have one, and did it turn out to be worth the money? Share your experience in the comments.

What to Read Next

The $500 Birthday Party Question: When Did Kids’ Birthdays Get So Expensive?

6 Ways Parents Are Quiet Quitting Expensive School Spirit Days

The 3 Most Expensive Mistakes Parents Make When Saving for College

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: consumer trends, Family Budget, family finances, Kids, Parenting, parenting tips, Saving Money, social pressure, unnecessary kids' purchases

Your Child Got Birthday Money — Should You Let Them Spend All of It?

August 23, 2026 | Leave a Comment

Young Boy Opening Gift
Birthday cash can give children more than spending power—it can provide a practical lesson in saving, budgeting, and making thoughtful choices. Giving kids some control while setting age-appropriate guidelines can help turn a birthday gift into valuable financial experience. (Pexels).

Birthday cards are opened, cake crumbs are everywhere, and suddenly your child is holding $100 from generous relatives. Their first instinct may be to spend every dollar on toys, games, clothes, or something they spotted online. For parents, birthday money for kids presents an interesting question: Should children have complete control because the money was given to them? The better approach often involves giving children meaningful freedom while using the moment to teach financial habits they can carry into adulthood.

Remember That It Really Is Their Gift

Birthday money for kids is different from a regular allowance because someone specifically gave that money as a gift. Taking complete control can unintentionally make children feel that money they receive never truly belongs to them. Instead, parents can establish reasonable boundaries while allowing children to participate in deciding what happens next. A 10-year-old receiving $100, for example, might be allowed to immediately spend a portion rather than surrendering everything to savings. That sense of ownership makes the financial lesson more meaningful because the child has something personally at stake.

Avoid Making Saving Feel Like Punishment

Requiring children to save every birthday dollar sounds financially responsible, but it can send the wrong message about saving. Children may begin viewing savings as money that disappears into an account they cannot enjoy. Fidelity recommends age-appropriate money lessons and suggests putting part of birthday and special-occasion money into savings. A better conversation explains what the saved money can eventually accomplish, whether that means purchasing a bicycle, laptop, or another meaningful item. Giving savings an identifiable purpose transforms it from a parental restriction into progress toward something the child actually wants.

Try Dividing The Money Into Buckets

One practical approach to birthday money for kids is dividing it among spending, saving, and possibly giving. There is no universally correct percentage, so families can choose numbers that match the child’s age and their household values. If a child receives $120, for instance, parents might discuss spending $60, saving $50, and donating $10. Fidelity describes a similar “bucketing strategy” as a way to help children understand that savings should not simply consist of leftover money. Older children can gradually take greater responsibility for deciding the percentages themselves.

Let Small Spending Mistakes Become Lessons

Parents naturally want to stop children from wasting $40 on something that may lose its appeal by next weekend. Yet making a disappointing purchase with birthday money can teach a lesson that lectures about budgeting rarely accomplish. Fidelity advises parents not to intervene too quickly when children are earning and saving toward things they want because personal financial decisions provide valuable experience. If the purchase is safe and age-appropriate, consider letting the child make the choice and experience the consequences. Losing $25 to an impulsive toy at age nine may prevent considerably more expensive impulse purchases later.

Introduce A Waiting Period For Bigger Purchases

Excitement can make birthday money for kids feel as though it needs to be spent immediately. For a larger purchase, consider introducing a 24-hour waiting period for younger children or several days for older kids. Fidelity even suggests that teenagers consider a two-week pause before committing their own money to an expensive purchase. During that waiting period, encourage your child to compare prices, read reviews, and think about how frequently the item will actually be used. The objective is not to prevent spending but to demonstrate the difference between wanting something immediately and deciding it offers lasting value.

Match The Rules To Your Child’s Age

A six-year-old and a 16-year-old should not necessarily follow identical rules for birthday money for kids. Younger children may benefit from physical cash because seeing bills disappear makes spending easier to understand. Fidelity recommends beginning with tangible money before gradually teaching children how digital spending works. Teenagers can handle more independence, including budgeting larger gifts and potentially managing money through an appropriate bank or youth account. Increasing freedom gradually gives children opportunities to practice financial decision-making while parents are still available to provide guidance.

Give Them Freedom Without Losing The Lesson

Parents do not have to choose between letting children spend everything and forcing them to save everything. A balanced approach gives children enough freedom to enjoy their birthday gift while encouraging them to save toward something meaningful. The strongest rules are usually explained through conversation rather than announced after the birthday cards have already been opened. Everyday experiences involving money can become useful financial lessons, and Fidelity recommends using real-life situations to discuss budgeting, wants, needs, and saving.

If your child received $100 tomorrow, how much control would you give them over it, and why? Share your approach in the comments.

What to Read Next

43% of Parents Would Go Into Debt to Help Their Kids Fit In — 7 Money Traps to Avoid

8 Money Skills Kids Should Know Before They Get Their First Debit Card

Money Lessons Kids Should Learn Before School Starts

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: birthday money, budgeting, family finances, financial literacy, kids and money, Money Lessons, Parenting, Saving Money

The $1,000 School Trip Question: When Should Parents Just Say No?

August 22, 2026 | Leave a Comment

School Trip
A $1,000 school trip can offer a memorable educational experience, but parents should consider the full cost, available financial assistance, and their household budget before signing the permission slip. Saying no may be the responsible choice when attending would require debt or jeopardize essential expenses. (Pexels).

A permission slip lands on the kitchen counter, and suddenly a parent is staring at a four-figure decision: Is a $1,000 school trip worth it? For many families, the answer is complicated because educational travel can offer memorable learning experiences while also putting serious pressure on a household budget. That pressure is especially relevant in 2026, when 37% of parents surveyed by NerdWallet said their children would likely miss at least one school activity because of cost. An expensive school trip may sound like a once-in-a-lifetime opportunity, but parents should not feel obligated to sacrifice financial stability to make it happen. Before saying yes, families need to separate the educational value from the fear that their child will be left out.

Start With What The Trip Actually Offers

Before paying for an expensive school trip, ask the school exactly what students will learn and experience that they cannot reasonably get closer to home. Educational trips can have real value, with research highlighted by Edutopia linking culturally enriching field trips to improved academic and behavioral outcomes. However, an overnight trip costing $1,000 should offer considerably more than sightseeing, restaurant meals, and time with friends. Ask for the itinerary, planned educational activities, supervision details, transportation arrangements, and a breakdown of what the fee covers. If the educational purpose sounds vague after those questions are answered, saying no becomes much easier to justify.

Decide Whether $1,000 Is Really $1,000

The advertised price may not represent the final cost of an expensive school trip, especially when families must separately pay for meals, luggage, spending money, clothing, insurance, or transportation to a departure point. A real-world example shows how quickly costs can climb: documents for one Massachusetts eighth-grade trip reported families paying $1,564 per student plus $160 for insurance during the 2024-2025 school year. Parents should therefore ask for a complete list of expected expenses before making a deposit. A trip advertised at $1,000 could realistically require another $100 or $200 once extras are included. Building a small cushion into the calculation prevents an exciting opportunity from turning into an unpleasant financial surprise.

Do Not Put The Trip On A Credit Card Without A Payoff Plan

A school trip becomes much harder to defend financially if the family must carry high-interest credit card debt to pay for it. Travel-related spending is already creating problems for some households, with a 2026 K12 survey finding that 46% of parents had taken on debt or charged more than they could afford for a family summer vacation. Although a school trip is different from a vacation, the budgeting principle is similar: memories should not create months of financial stress. If paying $1,000 means missing bills, draining emergency savings, or carrying a balance with no realistic repayment date, that is a strong reason to decline. Parents can acknowledge their child’s disappointment while explaining that protecting the family’s essential expenses comes first.

Ask About Financial Help Before Saying No

Before automatically rejecting an expensive school trip, parents should ask whether scholarships, fundraising opportunities, installment plans, or financial assistance are available. Some educational travel programs specifically provide scholarships, and Edutopia highlighted a high school study-abroad initiative that helped more than 100 students obtain over $300,000 in scholarships during the past decade. Families can ask the teacher or administrator privately whether the school has hardship funds or whether local organizations help cover student travel expenses. Payment plans may also turn a $1,000 lump sum into manageable monthly payments, although parents should confirm whether deposits are refundable. Asking about assistance is not embarrassing; it is a practical step before deciding an opportunity is unaffordable.

Consider What Saying No Actually Means

Parents often worry that declining a trip will leave their child socially isolated or permanently deprived of an important experience. That concern deserves consideration, particularly when most classmates are attending, but it should not automatically override financial reality. An expensive school trip is still optional if students can meet academic requirements without participating, so ask the school what alternative activities will be provided. Parents can also discuss the decision honestly in age-appropriate terms rather than simply saying, “We can’t afford it,” and ending the conversation. A teenager may be disappointed, but understanding how families weigh wants, opportunities, and financial limits can itself become a valuable lesson.

The Best Answer Protects Both Opportunity And Stability

There is nothing wrong with paying $1,000 for a genuinely valuable experience when the family can comfortably afford it, and there is equally nothing irresponsible about saying no. The best decision considers educational value, total costs, financial assistance, household priorities, and the consequences of taking on debt. Parents should ask questions rather than allowing urgency, guilt, or fear of their child missing out to make the decision for them. Sometimes the answer will be yes, while other families may decide that financial stability is worth more than one memorable weekend away.

Would you pay $1,000 for your child’s school trip, or is there a price where you would simply say no? Share your thoughts and experiences in the comments.

What to Read Next

5 School Field Trip Threads That Expose Emotional Trauma Risks

The Hidden Costs of After-School Care for Kids With Special Needs

When Parents Should Put a School-Lunch Accommodation Request in Writing

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: Back to School, budgeting, education, family finances, Parenting, parenting decisions, Saving Money, school expenses, school trips, student travel

43% of Parents Would Go Into Debt to Help Their Kids Fit In — 7 Money Traps to Avoid

August 20, 2026 | Leave a Comment

Young Parent Budgeting
From trendy school gear to costly extracurriculars, the pressure to help children fit in can push parents beyond their budgets. Setting clear spending limits can protect family finances while teaching children valuable money lessons. (Pexels).

The expensive sneakers. The travel team all their friends joined. The class trip. The birthday outing everyone is talking about. For parents, saying “we can’t afford that” can feel like saying no to far more than a purchase—it can feel like risking your child’s place in the group. That pressure is powerful enough that a 2026 NerdWallet survey found 43% of parents would go into debt for back-to-school purchases that could help their child fit in, while 45% would take on debt for extracurriculars their child wants to participate in. The goal isn’t to deny children every expensive experience; it’s to recognize when the fear of letting them feel left out starts making financial decisions for the entire family.

1. Going Into Debt So Your Child Can Keep Up

The pressure to say yes can be surprisingly powerful when a child insists that “everyone else” has the shoes, backpack, phone, or clothes they want. In a 2026 Credit Karma survey, 54% of parents said they would rather put something on a credit card than tell their child they couldn’t have what classmates have, while 57% were already entering back-to-school season carrying credit card debt. The problem is that borrowing turns a temporary social concern into a financial obligation that can remain long after the shoes are outgrown or the trend disappears. Give children a defined clothing or extras budget instead and let them decide whether one expensive item is worth giving up several cheaper purchases. Saying, “We can spend $150, so let’s decide together what matters most,” teaches considerably more about money than pretending every purchase is affordable.

2. Upgrading Activities Because “All Their Friends Are Doing It”

Sports, dance, music, clubs, and other activities can provide friendships and experiences that make the expense worthwhile, but the pressure to keep up can turn one activity into an escalating series of commitments. A child may begin with recreational soccer before friends move to a travel program involving higher registration fees, uniforms, hotels, tournament meals, and private training. NerdWallet’s 2026 research found 45% of parents would go into debt for extracurricular activities their children wanted to participate in, illustrating how emotionally difficult these decisions can become. Before saying yes, ask for the full-season price—including travel, equipment, fundraising, and optional training—not simply the registration fee. Sometimes the financially sustainable answer is one activity the child truly values rather than attempting to match every opportunity their friends receive.

3. Letting Social Media Turn Wants Into “Needs”

Money Mistakes
The pressure to help children fit in can turn ordinary purchases into difficult financial decisions for parents. Kzenon/Shutterstock

Today’s pressure to fit in doesn’t stop when children leave school because TikTok, Instagram, YouTube, and other platforms can continuously show them what their peers and influencers are buying. Credit Karma found that 60% of surveyed parents said their children requested nonessential back-to-school items they’d seen trending online, while 48% said their child’s wish list was very far from what the family budget allowed. A trendy water bottle, backpack accessory, collectible, sneaker, or phone upgrade can suddenly feel socially necessary even when a perfectly usable version is sitting at home. Try putting nonessential trend purchases through a seven-day waiting period and let older children contribute allowance, birthday money, or earnings toward expensive upgrades. If they still want the item after waiting—and are willing to use some of their own money—the purchase probably matters more than an impulse generated by this week’s feed.

4. Cutting Essentials to Protect Kids From Feeling the Pinch

Parents naturally want financial stress to remain an adult problem, but shielding children from every budget limitation can create more serious problems for the household. Credit Karma found that 49% of surveyed parents expected to sacrifice essentials such as groceries or bills to make room for back-to-school expenses, while 63% said they hide back-to-school financial stress from their children. There is an important difference between protecting children from adult financial anxiety and pretending the household has no financial limits. Groceries, housing, utilities, insurance, minimum debt payments, and emergency savings should generally come before optional upgrades designed primarily to help a child keep up socially. An age-appropriate “that’s not something we’re spending money on right now” can be healthier than quietly making the household less secure.

5. Shopping Without Separating “Need” From “Fit In”

Back-to-school shopping mixes genuine necessities with social wants, which makes overspending especially easy. A child may legitimately need new shoes but want a particular $140 pair because friends are wearing them, or need a backpack while insisting the perfectly functional one from last year is suddenly unacceptable. NerdWallet found only 36% of back-to-school shoppers planned to set a firm budget in 2026, while one-quarter said most of their shopping would be for non-necessities requested by their children. Before shopping, divide the list into three columns: Must Replace, Still Usable, and Wants/Upgrades, then assign the available budget accordingly. Giving older children control over the “wants” portion allows them to choose the expensive sneakers if they’re willing to sacrifice something else.

6. Sacrificing Your Future for Every Experience Today

The hardest “no” may involve experiences rather than possessions because parents understandably worry their child will remember being the one who missed the trip, camp, concert, or vacation. But repeatedly reducing retirement contributions, carrying credit-card balances, or postponing important financial goals to finance optional experiences simply moves today’s cost into the future. Before spending $2,000 on an activity or trip, ask a different question: “If none of my child’s friends were doing this, would we still think it was worth $2,000?” If the answer changes, social pressure may be driving more of the decision than the experience itself. Children can have memorable childhoods without participating in every opportunity available to families with different incomes and priorities.

7. Hiding Every Financial Limit From Your Children

Protecting children from adult financial stress is healthy; teaching them that money has no limits is not. Credit Karma found 55% of surveyed parents were having direct conversations with their children about what the family could and couldn’t afford, while one-third were asking children to contribute some of their own money toward back-to-school purchases. Those conversations don’t require telling a 10-year-old the mortgage balance or frightening children about household finances. Parents can simply say, “We have $100 available for this,” or “You can choose the expensive shoes, but that means keeping last year’s backpack.” Learning that money involves choices may ultimately prepare children better than growing up believing their parents can always find a way to say yes.

Try the “Fit-In Test” Before Saying Yes

When emotion makes a purchase feel urgent, parents can run through a few questions before reaching for a card:

Ask YourselfWhy It Matters
Would we buy this if none of their friends had it?Separates genuine value from social pressure
Can we pay for it without debt?Tests actual affordability
Are we sacrificing a necessity or savings goal?Reveals the hidden trade-off
Will they still care about this in a month?Filters short-lived trends
Can my child contribute toward the upgrade?Creates ownership and teaches saving
Is there a cheaper way to get the same experience?Keeps the opportunity without matching someone else’s spending

The point isn’t that every “yes” must pass all six questions. A parent may knowingly spend more on something because it matters enormously to their child, and that’s a perfectly legitimate use of money when the household can afford it. The test simply helps distinguish an intentional family choice from a purchase driven primarily by fear that a child might temporarily feel left out.

Your Child Doesn’t Need Your Family to Keep Up With Every Other Family

No parent can eliminate every moment when a child feels left out, and attempting to do so can create financial consequences that last far longer than the disappointment. The 2026 surveys are striking precisely because they show how powerful that pressure has become: substantial shares of parents say they would take on debt to help children fit in or participate in desired activities. A healthier goal is not automatically saying no, but deciding what your household can afford before another family’s spending sets the standard. Let children participate in some financial choices, teach them that different families prioritize different things, and save the big “yes” for experiences and purchases that genuinely matter. Sometimes giving children a financially stable home requires being willing to let them hear “not this time.”

What purchase or activity creates the most pressure for parents to keep up with other families—clothes, phones, sports, vacations, birthday parties, or something else? Share your experience in the comments.

What to Read Next

The $500 Birthday Party Question: When Did Kids’ Birthdays Get So Expensive?

Should Kids Get Paid for Good Grades? What Parents Should Consider Before Offering Cash

Back-to-School Anxiety in Autistic Students: Signs Parents May Notice

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Personal Finance Tagged With: Back to School, budgeting, Family Budget, family finances, financial planning, kids and money, money mistakes, parental spending, Parenting, Saving Money

The $500 Birthday Party Question: When Did Kids’ Birthdays Get So Expensive?

August 19, 2026 | Leave a Comment

Birthday Party
From venue rentals and custom cakes to balloon displays and party favors, kids’ birthday party costs can climb past $500 surprisingly quickly. More families are reconsidering whether expensive extras really create better birthday memories. (Unsplash).

A child’s birthday can go from cake and balloons to a $500 event surprisingly fast. Venue packages, pizza, decorations, favors, entertainment, taxes, and tips can turn what looked like a modest afternoon into one of the family’s bigger discretionary expenses of the year. A 2024 survey reported by The Bump found participating parents spent nearly $314 on average on a child’s party, excluding gifts, while 20% said they had spent more than $500. Meanwhile, newer 2026 research suggests many families are actively looking for less expensive celebrations. The real question isn’t whether parents can spend $500 on a birthday—it’s which parts of the party actually make the day special enough to justify the money.

How A $500 Party Happens Faster Than You Think

A 2024 survey reported by The Bump found parents spent an average of nearly $314 on a child’s birthday party, excluding gifts, and 20% said they had spent more than $500. Add a $200 venue, $100 cake, $75 worth of pizza and drinks, $60 in decorations, and $75 in favors, and a family has already crossed the $500 mark. Those numbers become even easier to reach when parents hire magicians, face painters, balloon artists, or character performers. The Philadelphia Inquirer has documented families spending $600, $1,500, and even thousands on elaborate children’s celebrations. Kids’ birthday party costs often become expensive not because of one extravagant purchase but because seemingly small expenses accumulate.

What a $500 Kids’ Birthday Party Could Look Like

ExpenseExample Cost
Venue/activity package$175
Food and drinks$90
Cake/cupcakes$55
Decorations$50
Party favors$40
Invitations/supplies$20
Extra guests/upgrades$35
Taxes/tips/fees$35
Total$500

These are illustrative amounts, not national averages. Actual costs vary enormously by location, guest count, venue, food choices, and party type.

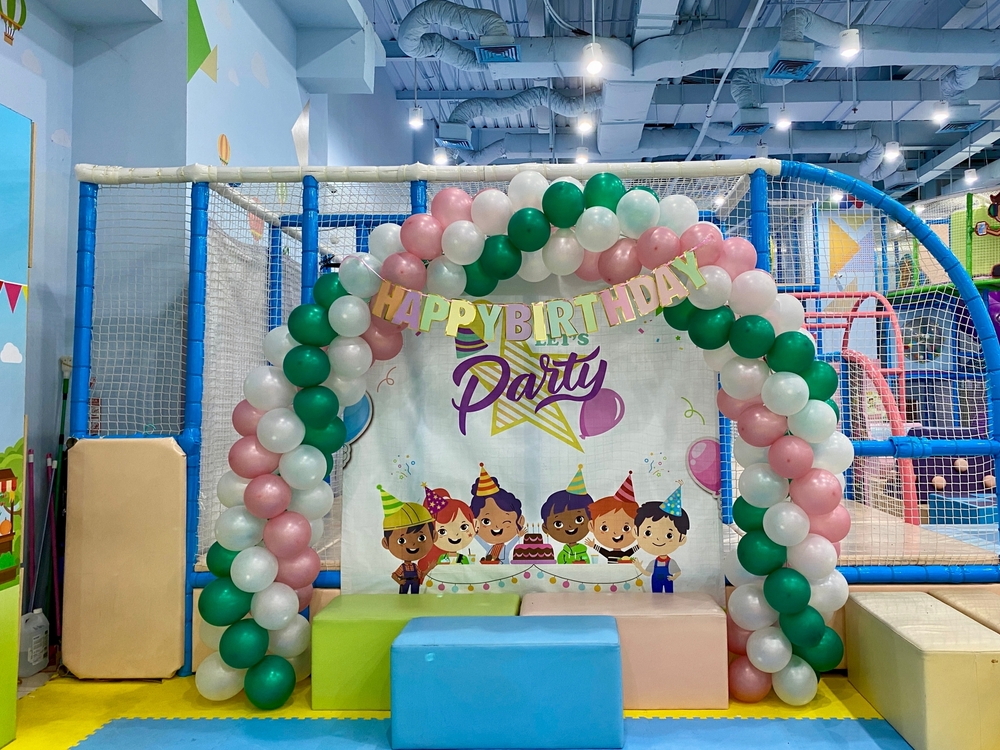
kids birthday party venue trampoline indoor playground
Birthday venues can simplify setup and entertainment, but food, additional guests, upgrades, fees, and other extras can push the final price well beyond the advertised package. MHDphonegraphy/Shutterstock

Social Media Changed What a “Normal” Birthday Looks Like

Parents once compared birthday parties mostly with celebrations hosted by relatives, neighbors, and classmates, but social media dramatically expanded the comparison group. Instagram, Pinterest, and TikTok can make balloon arches, custom signs, dessert walls, matching favors, elaborate themes, and professional photography look like standard birthday-party equipment rather than optional extras. The pressure isn’t entirely theoretical: The Philadelphia Inquirer interviewed parents who described spending hundreds or even $1,500 on children’s parties, with some acknowledging the influence of expectations created by celebrations around them. The danger is not that an elaborate party is inherently wasteful; families who can afford one may genuinely enjoy creating it. The budget problem starts when parents find themselves buying things primarily because they’ve begun to feel that a child’s birthday is incomplete without them.

The Party Industry Offers More Ways To Spend

Modern parents also have far more birthday options available than previous generations did, from trampoline parks and indoor playgrounds to mobile petting zoos and gaming trucks. These businesses can make hosting easier because someone else handles entertainment, setup, and cleanup, but convenience comes with a price. Once upgrades such as extra guests, premium food, themed decorations, party favors, and longer playtime are added, the advertised package price may no longer resemble the final bill. That helps explain why a celebration that begins with a seemingly reasonable budget can become surprisingly expensive. Parents comparing packages should calculate the total cost, including taxes, service charges, tips, food, and optional extras, before sending invitations.

What Kids Enjoy Most May Not Be the Most Expensive Part

children playing games backyard birthday party
Activities and time with friends can create the memorable part of a birthday without requiring elaborate decorations or an expensive venue. eleonimages/Shutterstock

Parents wondering whether a cheaper party automatically means a disappointing birthday have some interesting data to consider. In a 2026 survey commissioned by Chuck E. Cheese, 34% of nearly 5,000 parents said more games and activities would have most improved their child’s previous party, while 23% chose a special theme or decorations. A separate company study found gifts, family and friends, and birthday food or cake were all cited more frequently as highlights than the party venue itself. The findings come from a company that sells children’s birthday experiences, so they should be viewed in that context, but they still raise a useful budgeting question: are parents spending most heavily on the parts children value most? A backyard treasure hunt, park party, homemade pizza night, sleepover, or afternoon with a handful of close friends may deliver plenty of the experience a child wants without requiring a $500 budget.

Parents May Already Be Pushing Back on Party Inflation

There are signs that bigger-is-better celebrations aren’t the only trend shaping birthdays in 2026. Evite’s 2026 Pregame Report, based on a survey of 5,000 users, found 67% preferred DIY and affordable party options, while respondents also showed strong interest in smaller, more meaningful gatherings. That creates an opportunity for parents to reset expectations instead of assuming every birthday must become more elaborate than the previous one. Set the total budget before choosing the venue, establish the guest count early, and ask the birthday child which one or two things matter most. A child who desperately wants a bounce house may be perfectly happy trading custom favors, elaborate decorations, and a professionally decorated cake for that one memorable attraction.

Try the “One Splurge” Rule Before You Start Shopping

A useful way to control a birthday budget is to let the birthday child choose one thing that gets a larger share of the money. Maybe that’s a bounce house, trampoline-park visit, special cake, gaming party, craft activity, or dinner at a favorite restaurant. Once that priority is chosen, deliberately make the other categories inexpensive: grocery-store cupcakes instead of a custom cake, digital invitations instead of printed ones, simple decorations instead of a balloon installation, or no favors at all. This approach also forces parents to establish the total budget before browsing party packages, where upgrades can quickly turn a $250 plan into a $500 celebration. The goal isn’t to create a cheap-looking party; it’s to spend heavily on the part the child actually cares about and stop spending on things nobody will miss.

Two Very Different Birthday Budgets

Party Feature$150 Celebration$500 Celebration
LocationHome/park: $0Venue: $175
FoodPizza/snacks: $55Food/drinks: $90
CakeGrocery/homemade: $30Custom cake: $55
ActivityDIY games: $20Included/upgrades: $60
Decorations$20$50
Favors$15$40
Miscellaneous$10$30
Total$150$500

The biggest savings usually don’t come from skipping the cake. They come from controlling the venue, guest count, entertainment, and upgrades.

The Best Birthday Budget Is One You Don’t Regret the Next Morning

There is nothing inherently irresponsible about spending $500, $1,000, or more on a child’s birthday when the family can comfortably afford it and genuinely values the celebration. The warning sign is financing the party with credit-card debt, pulling money from essential expenses, or spending primarily because other families have established an expensive standard you feel obligated to match. Before booking anything, choose a maximum budget, ask your child what matters most, and price the entire event—including fees, taxes, tips, favors, food, and upgrades—rather than focusing only on the advertised venue price. A memorable birthday doesn’t require proving how much you were willing to spend on it. If the child finishes the day surrounded by people they love and talking excitedly about what they did, the party probably accomplished its purpose.

Have kids’ birthdays become unnecessarily expensive, or does $500 simply reflect what parties cost today? What do birthday parties typically cost in your family?

What to Read Next

6 Things Parents Should Stop Automatically Paying For Once Their Teen Has a Job

5 Birthday Party Traditions From the 90s That Saved Parents a Fortune

The Birthday Party Blacklist: Why Not Hosting a Luxury Experience Is Making Your Child a Social Pariah

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: affordable parties, birthday party costs, birthday party ideas, children, Family Budget, family finances, kids birthday parties, Parenting, Saving Money, Social Media

8 Money Skills Kids Should Know Before They Get Their First Debit Card

August 18, 2026 | Leave a Comment

Debit Card
A first debit card can give kids hands-on practice with budgeting, saving, checking balances, and making thoughtful spending decisions. Parents can also use the experience to teach children how to protect their card information and recognize suspicious transactions. (Pexels).

A first debit card can feel like a major step toward independence for a child, but tapping a card is much easier than understanding what happens to the money behind it. Before handing over that plastic, parents can use the moment to teach money skills for kids that will matter long after allowances and lunch purchases disappear. A debit card generally draws money directly from an account, meaning every purchase reduces the amount available for something else. Teaching a few practical habits beforehand can turn that first card into a valuable financial lesson rather than simply another way to spend.

1. Understand Where Debit Card Money Comes From

Kids should understand that a debit card is not a source of unlimited money. Unlike borrowing with a credit card, a typical debit purchase takes money from funds already available in the linked account. If a child has $40 and spends $12 on lunch, only $28 remains for future purchases. Encourage kids to check their available balance before buying rather than assuming the card will work. This is one of the most fundamental money skills for kids because it connects digital spending with real dollars.

2. Create A Simple Spending Plan

A child does not need a complicated spreadsheet to learn budgeting. Suppose your child receives $30 each week and decides to save $10, spend $15, and keep $5 available for unexpected expenses. That simple division teaches them that money usually has competing purposes. Parents can encourage kids to decide how money will be used before it lands in their account instead of figuring it out after most of it disappears. Practicing this routinely can make budgeting feel normal rather than restrictive.

3. Know The Difference Between Needs And Wants

One of the most useful money skills for kids is learning to distinguish a genuine need from something they simply want right now. School supplies might be necessary, while another game download or after-school smoothie is generally optional. The distinction does not mean kids should never buy fun things, but it encourages them to recognize trade-offs. Ask, “Would you still want this tomorrow?” before an impulse purchase. That short waiting period can help children develop stronger spending judgment.

4. Learn To Save Before Spending

Saving works better when it becomes part of the routine instead of something kids attempt with leftover money. A child saving for $80 headphones, for example, could put $10 from every allowance payment toward the goal. Watching the balance grow provides a visible connection between patience and reaching something they value. Many youth-focused financial apps now include savings goals or separate spending and saving categories, making the process easier to visualize. Developing this habit early is among the money skills for kids that can carry into adulthood.

5. Check Transactions And Account Balances

Kids should learn that managing a debit card includes reviewing what happens after they tap, swipe, or shop online. Have your child look through recent transactions regularly and compare purchases with the current balance. A forgotten $6 snack or subscription can suddenly explain why there is less money available than expected. Reviewing activity can also help families spot purchases a child does not recognize. The goal is not constant parental surveillance but teaching children that responsible account holders pay attention to their money.

6. Understand Fees And Declined Purchases

Kids may assume a declined card means something is wrong with the card itself, when the problem could simply be insufficient funds or an account restriction. Depending on the account, consumers can also encounter charges involving ATMs, foreign transactions, subscriptions, or other services. Parents should review the specific fee schedule for their child’s account because policies vary considerably among providers. Consider showing your child an example of how paying a $3 fee to access $20 would immediately make that transaction more expensive. Understanding fees helps kids recognize that how they use financial services can affect how much money they keep.

7. Protect Card And Account Information

Security belongs on every list of essential money skills for kids because debit cards can expose real money to fraud. Children should never share their PIN, card number, security code, password, or verification codes with friends or strangers. They should also know that unexpected messages claiming there is an urgent account problem can be attempts to steal information. Parents should encourage children to monitor account activity and avoid payment terminals that appear altered or suspicious. Make one family rule especially clear: if the card disappears or an unfamiliar transaction appears, tell a parent immediately rather than waiting.

8. Think Before Making Digital Purchases

Online spending can feel less real because kids never physically hand over cash. A few $2 or $5 in-app purchases can quickly become a surprisingly large total when repeated throughout the month. Before confirming an online purchase, kids should check the price, their available balance, and whether the purchase is recurring. Parents can also use available spending limits, alerts, and merchant controls as temporary guardrails while children develop good judgment. These tools work best when paired with conversations, because the long-term goal is responsible decision-making without constant supervision.

A Debit Card Should Be A Learning Tool

A child’s first debit card can provide a low-stakes opportunity to practice financial decisions before adult expenses become much larger. The strongest money skills for kids are built through everyday choices involving earning, saving, spending, security, and trade-offs. Parents do not need children to make perfect decisions; even an impulsive $15 purchase can become a useful lesson when discussed constructively afterward. Giving kids gradually increasing responsibility can help them understand that financial independence comes with accountability.

Which money skill do you think children struggle with most before receiving their first debit card, and what are you doing to prepare yours? Share your experience in the comments.

What to Read Next

Money Lessons Kids Should Learn Before School Starts

Why Giving Your Kids a Debit Card Might Be the Smartest Move You Make

Here’s What You Should Do Before Letting Your Teen Get a Debit Card

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: budgeting, debit cards, family finances, Financial Education, financial literacy, kids and money, money management, money skills for kids, Parenting, Saving Money

How Much Should a Teen Contribute Toward Their First Car?

August 18, 2026 | Leave a Comment

Teen Driving First Car
A teen’s first car should fit the family’s budget without sacrificing safety or leaving the young driver unable to cover ongoing expenses. Agreeing on the purchase contribution, insurance, fuel, and repair responsibilities before buying can turn the experience into a valuable financial lesson. (Pexels).

Buying a first car is one of those milestones that can feel exciting for a teenager and financially complicated for a parent. Families have to balance independence, safety, affordability, and the valuable lesson that a vehicle costs more than the number on the windshield. There is no universal teen car contribution that works for every household, but having a teen pay something can give them meaningful ownership in the decision. The right amount depends on income, savings, family finances, and who will cover expenses after the keys change hands. Before shopping, parents and teens should agree on those numbers together.

Start With What The Teen Can Realistically Afford

A reasonable teen car contribution should challenge a young driver without draining every dollar they have saved. For example, a teenager who has accumulated $3,000 from a summer job might contribute $1,500 toward an $8,000 vehicle while keeping the rest for insurance, fuel, and emergencies. Asking that teen to surrender the entire $3,000 could leave no financial cushion when the battery dies or the car needs tires. Families with fewer resources may need a larger contribution, while others may comfortably match what their teen saves. The goal is financial responsibility rather than making the purchase unnecessarily difficult.

Consider A Percentage Instead Of A Fixed Dollar Amount

Some families find that dividing the purchase price creates clearer expectations than choosing an arbitrary dollar figure. A teen car contribution of 25% to 50% can be a practical starting range when parents have the ability and desire to cover the remainder. On an $8,000 car, that would put the teenager’s share between $2,000 and $4,000, making the connection between work, saving, and purchasing tangible. Another option is a dollar-for-dollar match, such as parents contributing $3,000 after their teenager saves $3,000. Whatever formula you choose, establish it before visiting dealerships so emotion does not suddenly expand the budget.

Remember That The Purchase Price Is Only The Beginning

A first-time driver needs to understand that buying a car creates recurring expenses long after the initial payment. AAA’s 2025 analysis estimated that owning and operating a new vehicle averaged $11,577 annually, although an older, inexpensive used car can cost considerably less. Insurance can be particularly painful because young drivers present greater risk to insurers, and Bankrate reported an average full-coverage rate of about $5,740 annually for a 16-year-old on a parent’s policy as of November 2025. Actual premiums vary dramatically by location, vehicle, insurer, coverage, and household circumstances, so families should obtain quotes before purchasing. A teen car contribution therefore might include paying part of the insurance or fuel instead of putting every available dollar toward the purchase.

Do Not Sacrifice Safety To Make The Teen Pay More

Parents may understandably want their child to experience the satisfaction of buying a car independently, but safety should not become the price of that lesson. The Insurance Institute for Highway Safety and Consumer Reports updated their teen recommendations in May 2026 with 45 used vehicles starting below $10,000 that meet their safety criteria. Some recommended models have estimated starting prices below $5,000, demonstrating that families can find relatively affordable choices without automatically settling for the oldest vehicle available. A pre-purchase inspection by an independent mechanic is also worth considering before handing over money for a used vehicle. If increasing the parents’ contribution provides access to a substantially safer and more reliable car, that can be money well spent.

Decide Who Pays The Ongoing Bills

The fairest arrangement may depend less on the initial teen car contribution and more on what happens afterward. One family might buy the vehicle but require the teen to pay for gasoline, while another might split insurance and maintenance costs. A teen earning $600 monthly from a part-time job, for example, could reasonably set aside $100 or $150 for transportation without making saving for other goals impossible. Parents should also decide in advance who handles registration, repairs, deductibles after an accident, parking, and unexpected expenses. Writing down the arrangement can prevent disagreements when the first $700 repair bill unexpectedly arrives.

Make The Contribution A Lesson That Lasts

Ultimately, a teen car contribution should teach responsibility without turning a first vehicle into a financial burden that crowds out every other priority. For many households, asking the teenager to cover roughly 25% to 50% of an affordable used vehicle, or matching the teenager’s savings, offers a workable framework rather than an inflexible rule. Parents should factor safety, insurance, maintenance, emergency savings, and the teen’s actual earnings into the final decision. The best arrangement is one everyone understands before anyone starts scrolling through car listings or walking onto a dealer’s lot.

How much would you expect a teenager to contribute toward a first car, and which expenses should parents continue covering afterward? Share your approach in the comments.

What to Read Next

10 Reasons Why Teenagers Need Driving Restrictions

6 Things Parents Should Stop Automatically Paying For Once Their Teen Has a Job

The 3 Financial Conversations Every Parent Needs to Have with Their Teen

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: car buying, family finances, financial literacy, first car, parenting teens, Saving Money, teen car contribution, teen car insurance, teen drivers, used cars

6 Things Parents Should Stop Automatically Paying For Once Their Teen Has a Job

August 16, 2026 | Leave a Comment

Working Teen
A teen’s first paycheck creates an opportunity to practice budgeting by taking responsibility for manageable expenses such as entertainment, takeout, gas, and personal purchases. Gradually shifting these costs can teach financial independence without removing essential parental support. (Pexels).

Getting a first job is a major milestone for a teenager, but the paycheck can teach far more than how quickly money disappears at the mall. For parents, it is also an opportunity to introduce teen financial responsibility while the consequences of mistakes are still relatively small. That does not mean suddenly making a 16-year-old pay rent, groceries, and every household expense. Instead, gradually transferring a few reasonable costs can help teens learn budgeting, saving, and the difference between wants and needs before adulthood makes those lessons considerably more expensive.

1. Everyday Entertainment And Outings

Once teens receive regular paychecks, parents do not necessarily need to keep funding every movie, coffee run, concert, or night out with friends. Having a minor entertainment budget feels very different when the teenager knows those dollars represent several hours of work. If they spend everything on Friday and cannot afford Saturday’s plans, the natural consequence provides a valuable budgeting lesson without threatening an essential need. Parents can still pay for family outings, birthdays, and special occasions rather than turning every activity into a financial negotiation. This approach makes teen financial responsibility practical instead of something discussed only around the kitchen table.

2. Nonessential Clothing And Fashion Upgrades

Parents should generally continue providing necessary clothing, but trendy sneakers, designer labels, and extra outfits can become a teen’s responsibility after employment begins. Imagine a teenager choosing between $120 sneakers and putting that same money toward a future car; suddenly, comparison shopping matters. Giving teens ownership over discretionary clothing purchases also helps them recognize how quickly impulse buys can consume a paycheck. Parents can establish a clear boundary, such as covering school basics and replacing genuinely worn-out necessities while the teen pays for upgrades. The goal is not deprivation but teaching that having income requires making choices.

3. Takeout And Convenience Food

A family grocery budget should not disappear simply because a teenager starts working, but parents can stop automatically paying for every drive-through meal or food-delivery order. A small lunch purchased three times a week can add up over four weeks, which can be eye-opening for a new worker. Paying for these extras encourages teens to compare convenience with alternatives such as eating at home or packing lunch. This is an especially useful lesson because small recurring purchases are easy to overlook when creating a budget. Teen financial responsibility develops when young workers understand that frequent small expenses can compete with bigger savings goals.

4. Gas For Personal Driving

If a teen regularly drives to work, school, and social activities, contributing toward gasoline can be a reasonable next step. Parents might continue covering transportation required for school while asking the teen to pay for gas used for weekend trips and recreational driving. This creates a direct connection between driving choices and their real cost without handing a young worker an unaffordable insurance bill overnight. Families should decide expectations in advance so teenagers are not surprised when payday arrives. The arrangement can also encourage teens to combine trips, share rides appropriately, and think before making unnecessary drives.

5. Part Of Their Cellphone Costs

A smartphone is often necessary for communicating with parents, school, and employers, so requiring a teen to assume the entire family-plan bill may not make sense. However, extras such as device upgrades, premium accessories, additional storage, or replacing a carelessly damaged phone are reasonable expenses for an employed teenager. Parents could also ask for a modest monthly contribution, if that amount fits the teen’s earnings. A predictable recurring bill introduces teen financial responsibility because the money must be available every month rather than only when the teen feels like saving it. Parents should keep the amount manageable enough that work still provides an opportunity to build savings.

6. Impulse Purchases And Personal Wants

The simplest category to transfer may be all those spontaneous requests that begin with, “Can you buy me this?” Once a teen earns money, gaming purchases, cosmetics, collectibles, subscriptions, and similar wants can usually come from their paycheck. Fidelity advises parents to use everyday spending situations as opportunities to teach young people the distinction between wants and needs. Parents can help by asking teens to wait 24 or 48 hours before buying something expensive rather than immediately rescuing them from buyer’s remorse. That small habit can turn teen financial responsibility into thoughtful decision-making instead of merely paying bills.

A Paycheck Should Build Independence, Not End Parental Support

The purpose of shifting expenses is not to save parents money at their teenager’s expense; it is to provide supervised practice before adult financial obligations arrive. A teen earning a modest part-time income still needs parental support, particularly for essentials that would consume most of a paycheck. Gradually paying for discretionary expenses allows teens to make manageable mistakes, adjust their priorities, and develop teen financial responsibility while parents remain available for guidance. Families can revisit the arrangement as earnings, school demands, transportation needs, or savings goals change.

Which expenses do you think teenagers should start paying once they have a job, and which should remain a parent’s responsibility? Share your perspective in the comments.

What to Read Next

The Hidden Costs of After-School Care for Kids With Special Needs

6 Common Money Mistakes Kids Make When They Get Their First Job

10 Ways to Get Your Child Their First Paying Job This Summer

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: budgeting, family finances, financial literacy, Parenting, parenting teens, personal finance, Saving Money, teen financial responsibility, teen jobs, teenagers

7 School Lunch Payment Fees Quietly Raising Parents’ Costs

July 31, 2026 | Leave a Comment

Kids Eating Lunch
A parent should review a school lunch payment app while comparing deposit options, highlighting how transaction fees can quietly increase back-to-school costs. Understanding local payment policies may help families reduce unnecessary expenses. (Pexels).

Back-to-school shopping isn’t the only expense catching families off guard. Across the country, some parents are discovering that simply adding money to a child’s cafeteria account can come with extra costs that slowly add up over the school year. While many districts offer free ways to pay for school meals, others rely on third-party payment platforms that may charge convenience or processing fees for certain payment methods. Because policies vary by district, understanding these school lunch payment fees can help parents avoid unnecessary expenses and stretch their education budget further.

1. Convenience Fees for Online Deposits

Many school districts partner with third-party payment companies that allow parents to fund lunch accounts online or through mobile apps. Some platforms charge a flat convenience fee each time money is added, regardless of the deposit amount. The Consumer Financial Protection Bureau found average transaction fees of about $2.37, or roughly 4.4% of a deposit, in many districts it reviewed, though fees differ by provider and district. A parent making small weekly deposits could spend noticeably more over an entire school year than someone making fewer, larger deposits. Not every district passes these costs to families, so checking local payment policies is worthwhile.

2. Small Deposits Can Mean Bigger Annual Costs

Families often add $10 or $20 at a time because that fits their weekly budget. Unfortunately, when a flat fee applies to every transaction, frequent deposits can increase total costs. The CFPB estimated that parents making biweekly online deposits could pay more than $40 in fees over a school year, while those making only a few larger deposits would pay far less. These examples are estimates rather than guarantees, since every district operates differently. If your budget allows, fewer deposits may reduce the impact of school lunch payment fees.

3. Credit and Debit Card Processing Charges

Some payment platforms apply fees only when parents use a credit or debit card. Others may waive fees for electronic bank transfers or have different pricing structures depending on the payment method selected. Before completing a transaction, it is worth reviewing all available payment options on the platform. Even a quick glance at the payment screen can reveal a lower-cost alternative. Spending an extra minute comparing methods may save money throughout the school year.

4. Refund Fees or Balance Policies

When a student changes schools or graduates, families sometimes request a refund of unused lunch account balances. Depending on district policy or the payment processor, refunds may take time or involve administrative requirements. Some districts encourage families to transfer remaining balances to another student or leave funds for future use instead of requesting a refund. Since these policies vary widely, parents should review their district’s nutrition services information before making assumptions. Knowing the rules early helps avoid surprises later.

5. Automatic Reload Features

Many online payment systems offer automatic account reloading whenever a balance falls below a certain amount. While convenient, each automatic reload could trigger another processing fee if the platform charges per transaction. Parents who do not review these settings may unknowingly pay multiple fees throughout the semester. Checking account preferences once or twice a year can help ensure automatic payments still fit the family’s budget and spending habits. A larger reload amount may reduce estimated annual fees, but families should avoid depositing more than they can comfortably leave in the account.

6. Limited Awareness of Free Payment Options

Schools participating in the National School Lunch Program are expected to provide families with a fee-free way to add money to meal accounts. However, those options are not always the most visible or convenient, especially if online payment portals are promoted more prominently. In many districts, paying by cash, check, or another approved method may avoid transaction charges entirely. Families should remember that not every school charges online fees, and many districts absorb these costs on behalf of parents. Asking the school nutrition office about available payment methods can uncover options that save money.

7. Fees That Seem Small but Add Up

A single $2 fee may not seem significant during a busy school week. Over several months, however, repeated charges can quietly increase a family’s annual education expenses, especially for households with multiple children. Between school meals, activity fees, and other back-to-school costs, even modest savings can make a meaningful difference. Reviewing payment habits once each semester is a practical way to keep school lunch payment fees under control without making major lifestyle changes. A few small adjustments today could leave more room in the family budget tomorrow.

A Smarter Way to Manage School Lunch Costs

The convenience of online lunch payments has made life easier for millions of parents, but convenience sometimes comes at a price. Since every school district handles payment systems differently, families should review local policies before assuming every online deposit carries a fee. Looking for fee-free payment methods, making fewer deposits when practical, and understanding refund and reload policies can help reduce unnecessary costs. Staying informed is one of the easiest ways to protect your household budget while ensuring children have reliable access to school meals.

What strategies have helped you save money on school-related expenses, and should districts do more to make fee-free options easier to find? Share your experience or tips in the comments to help other parents navigate school lunch payment fees more confidently.

What to Read Next

Why “Back to School” Shopping Feels Like a Mortgage Payment Now

Teachers Beg Parents: Stop Buying These 7 High-Sugar Snacks for School Lunches

8 Reasons Your Kids Prefer School Lunches to What You Pack

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: Back to School, education costs, Family Budget, household budgeting, Parenting, personal finance, Saving Money, school lunch payment fees, school lunches, School Nutrition

« Previous Page
Next Page »
  • Facebook
  • Pinterest
  • RSS
  • Twitter

Basic Principles Of Good Parenting

Here some basic principles for good parenting:

  1. What You Do Matters: Your kids are watching you. So, be purposeful about what you want to accomplish.
  2. You Can’t be Too Loving: Don’t replace love with material possessions, lowered expectations or leniency.
  3. Be Involved Your Kids Life: Arrange your priorities to focus on what your kid’s needs. Be there mentally and physically.
  4. Adapt Your Parenting: Children grow quickly, so keep pace with your child’s development.
  5. Establish and Set Rules: The rules you set for children will establish the rules they set for themselves later.  Avoid harsh discipline and be consistent.
  6. Explain Your Decisions: What is obvious to you may not be evident to your child. They don’t have the experience you do.
  7. Be Respectful To Your Child: How you treat your child is how they will treat others.  Be polite, respectful and make an effort to pay attention.
Best Parenting Blogs

Most Popular

Baby

9 Unusual Baby Names That Sound Like They Belong to Future CEOs

Evan Morgan
Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Baby

9 Baby Names Inspired by Fall Without Naming Your Child Autumn

Evan Morgan
Target Store

Choking Incident Prompts Recall of 49,000 Target Gigglescape “Under the Sea” Popping Toys

Evan Morgan
Frustrated Girl

Why Some Students on the Spectrum Are Labeled With ODD

Evan Morgan

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette