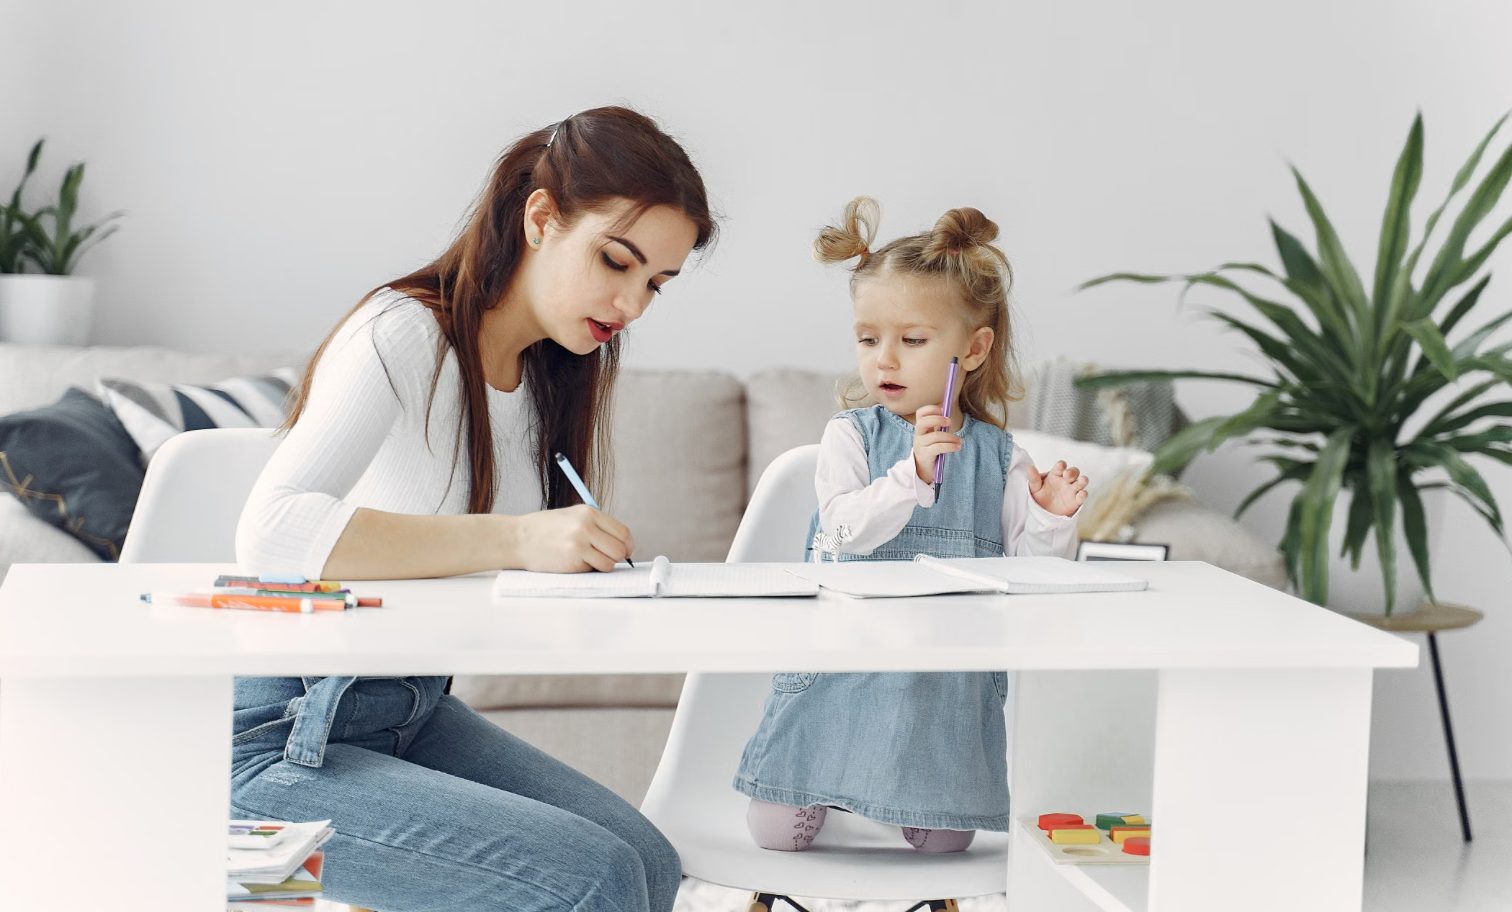
Daycare costs have become so expensive that some American families are questioning whether having two working parents makes financial sense. When childcare bills rival mortgage payments, quitting a job to stay home can seem like an obvious money-saving decision. However, the financial reality is more complicated than simply eliminating a daycare payment. Before making that decision, families need to understand the hidden costs of becoming a single-income household.
Daycare Costs Are Taking A Bigger Bite Out Of Family Budgets
According to Child Care Aware of America’s 2026 report, the national average annual childcare price reached $13,184 in 2025. That represents approximately 10% of the median income for two-parent households, although actual expenses vary considerably by location. Meanwhile, Care.com’s 2026 Cost of Care Report found average advertised daycare prices of $332 weekly for one infant and $585 for two children. At those rates, two children could cost approximately $30,420 annually, assuming 52 weeks of paid care. For families earning modest salaries, these expenses can make leaving the workforce appear financially attractive.
The Salary You Lose Matters More Than The Daycare Bill
Consider a hypothetical family where one parent earns $45,000 annually and pays $18,000 for daycare. After approximately $9,000 in combined income and payroll taxes, that parent brings home $36,000 before childcare expenses. Subtract daycare, and the household still retains approximately $18,000 annually from that income, before other work-related expenses. Quitting would eliminate the childcare bill but also sacrifice that remaining income. Families considering childcare savings should compare actual take-home pay against avoidable expenses rather than comparing daycare costs with gross salary.
Quitting Could Mean Losing Thousands In Employee Benefits
A paycheck represents only part of what an employee receives from working. According to KFF’s 2025 Employer Health Benefits Survey, average employer-sponsored family health insurance premiums reached $26,993 annually, with employees contributing $6,850. Losing employer coverage could increase household insurance expenses, depending on the other parent’s available benefits. Families must also consider disability coverage, paid leave, and retirement contributions that disappear when employment ends. Before resigning, request a complete benefits summary and calculate what replacing essential coverage would actually cost.
Retirement Savings Could Become The Biggest Hidden Expense
Leaving the workforce temporarily can create financial consequences that continue long after children enter school. Fidelity’s retirement analysis reports that employers contribute an average of 4.8% of employee pay to retirement accounts, including matching and nonmatching contributions. For someone earning $45,000, that percentage represents approximately $2,160 annually in employer retirement contributions. Five years away from employment could mean losing $10,800 in contributions alone, excluding potential investment growth. Families should consider funding a spousal IRA when eligible and reviewing retirement contributions before deciding that staying home delivers meaningful childcare savings.
Staying Home Can Reduce Expenses Beyond Daycare
Daycare isn’t the only expense families might eliminate when one parent stops working. Commuting, parking, professional clothing, workplace meals, and occasional backup childcare can collectively consume thousands of dollars annually. For example, eliminating $200 monthly in commuting costs and $100 in work-related meals saves another $3,600 yearly. However, staying home can increase grocery bills, household utility usage, and spending on children’s activities. Track three months of actual work-related expenses to determine which costs would disappear and which might simply shift elsewhere.
A Break-Even Calculation Can Reveal The Better Choice
Before making a decision, calculate how much employment actually contributes to the household after avoidable expenses. Suppose a parent brings home $36,000 annually while spending $18,000 on daycare and another $3,600 on commuting and workplace expenses. Continuing employment would contribute approximately $14,400 annually before accounting for benefits, retirement contributions, or changes in household taxes. Quitting might still make sense for personal reasons, but it would not produce immediate cash savings under those assumptions. Compare both scenarios using realistic insurance costs, tax estimates, childcare prices, and emergency savings requirements.
Flexible Work Arrangements May Offer A Financial Middle Ground
Families don’t necessarily have to choose between expensive full-time daycare and completely abandoning employment. Remote work, flexible schedules, part-time positions, and coordinated parental shifts may reduce paid childcare hours. However, working remotely while supervising young children is not always practical, particularly when employers require uninterrupted availability. Parents should also investigate employer childcare benefits, dependent care flexible spending accounts, sibling discounts, and licensed home-based childcare options. Comparing at least three local providers and discussing scheduling flexibility with employers could reveal meaningful childcare savings without sacrificing an entire salary.
The Smartest Decision Isn’t Always The Cheapest One
Leaving work to avoid daycare can improve family life, but the financial outcome depends on more than childcare savings. Families should calculate lost take-home income, employer benefits, retirement contributions, and future earning opportunities before deciding. For some households, especially those paying for multiple children, staying home may genuinely be the better financial choice. Others may discover that maintaining employment protects thousands of dollars in annual income and long-term financial security.
Would you give up a paycheck to avoid daycare costs, or does maintaining two incomes provide greater peace of mind? Share your experience and thoughts in the comments.
What to Read Next
Are Parents Talking Enough About Emotional Safety at Home?
3 Unexpected Options for Stay At Home Moms to Make Extra Money
Childcare Costs More Than the Mortgage for Some Families — When Does Working Still Pay?

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Read More
So, it has been very stressful lately. My son has been sick and this has…
For last minute gifts, some people choose to go the DIY way. I am one…
In a world that often celebrates social interaction and extroversion, some people find joy and…
Other than housing, food is probably the second largest component in a family's budget. With food prices…

I am sure you have heard me ramble on about how much my oldest son…


Technology promised to make co-parenting easier, and for many divorced or separated parents, modern co-parenting…


Leave a Reply