• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

15 Surprising Ways Your Daily Habits Impact Your Finances

May 20, 2024 | Leave a Comment

daily habits

Your financial health isn’t just determined by major decisions like investments or big purchases—it’s often influenced by the everyday habits you might not even think twice about. From your morning routine to how you unwind at night, here are 15 surprising ways your daily habits can impact your finances.

1. Morning Coffee Run
coffee run

Your daily coffee run might seem like a harmless indulgence, but those small expenses can add up quickly. Spending $5 on a latte every day translates to $1,825 a year—money that could be put towards savings or investments. Consider brewing your coffee at home or investing in a quality coffee maker to save hundreds of dollars annually. By cutting back on this daily habit, you’ll not only save money but also start your day with a financial boost.

2. Skipping Breakfast
skipping breakfast

Missing the most important meal of the day can lead to impulsive spending on snacks later. Investing in a nutritious breakfast can boost your energy and save you money in the long run. Especially if you are commuting to work, grabbing an on-the-go breakfast from home, like a breakfast bar, can save you a good amount of money. In sum, skip the Dunkin Donuts run to cut back on your spending.

3. Online Shopping Binges

online shopping

Those late-night scrolling sessions can lead to unnecessary purchases. Consider implementing a waiting period before hitting “checkout” to curb impulse buys. Shopping when you’re tired or bored can lead to impulse buys. Avoid online shopping late at night and save your purchases for when you’re more alert and focused.

4. Unplanned Grocery Trips
unplanned grocery trips

Shopping without a list can result in buying items you don’t need. Plan your meals for the week and stick to a shopping list to avoid overspending at the grocery store. Also, don’t grocery shop when you’re hungry. Everything looks good when you’re starving and can seriously alter your grocery shopping list.

5. Unused Subscriptions
subscriptions

Unused subscriptions often fly under the radar, silently draining your bank account month after month. Whether it’s a streaming service you signed up for but rarely use or a gym membership that collects dust, these subscriptions can add up to significant expenses over time. Take the time to review your subscriptions regularly and cancel any that you don’t actively utilize. By freeing up this extra cash, you can redirect it towards more meaningful expenses or savings goals.

6. Eating Out Frequently
eating out

Frequent dining out may provide convenience, but it often comes at a hefty price. The cost of restaurant meals, beverages, and tips can quickly escalate, putting a strain on your budget. By opting to cook at home more often, not only can you save money, but you also gain control over ingredients and portion sizes, leading to potentially healthier eating habits. Planning meals ahead of time and enjoying home-cooked dishes can not only benefit your wallet but also your overall well-being.

7. Ignoring Energy Efficiency
energy efficiency

Ignoring energy efficiency practices at home can lead to inflated utility bills month after month. Leaving lights on, keeping electronics plugged in, and neglecting to adjust thermostat settings can all contribute to unnecessary energy consumption. By developing simple habits such as turning off lights when leaving a room, unplugging electronics when not in use, and adjusting the thermostat to conserve energy, you can significantly reduce your utility costs over time. Taking proactive steps to improve energy efficiency not only saves money but also reduces your environmental footprint, making it a win-win situation.

8. Paying ATM Fees
ATM fees

Frequently using out-of-network ATMs can result in substantial fees that eat into your budget. These fees, often ranging from $2 to $5 per transaction, can add up quickly, especially if you make multiple withdrawals each month. Planning ahead and withdrawing cash from your bank’s ATM or opting for cashback at stores can help you avoid these unnecessary charges. Some banks also offer ATM fee reimbursement, so make sure to take advantage of this perk if offered by your bank.

9. Daily Commute Costs
daily habits commuting to work

Driving solo to work every day can drain your budget with gas and parking expenses. The average commuting expense per year in 2023 was $8,466. To cut down on costs, ask your employer for a hybrid work schedule, working from home on some days. If this isn’t possible, consider carpooling, biking, or using public transportation to save money on transportation.

10. Impulse Buying
impulse buying

Those small impulse purchases at the checkout counter can add up over time. Impulse buying is often linked to unhappiness, which motivates impulsive buying decisions. Often we believe that impulse buys will make us feel better, but that often is a fleeting feeling. Stick to your shopping list and avoid the temptation to save money and also improve your well-being.

11. Mindless Snacking
snacking

Constant snacking throughout the day can lead to overspending on convenience foods. Plan healthy snacks ahead of time to avoid impulse purchases. It may be helpful to portion out snacks or buy pre-portioned snack packs to avoid mindless snacking. This can help your whole family manage portions and ultimately save money.

12. Overusing Credit Cards
overusing credit cards

Swiping your credit card for every purchase can lead to debt accumulation due to high interest rates. Use cash or a debit card for everyday expenses to stay within your budget. If you do utilize your credit cards, make sure that you can pay off your balance at the end of the month to avoid interest fees. At the very least, make sure that you can comfortably pay the minimum balance owed to avoid unnecessary late fees.

13. Ignoring Discounts and Coupons
coupons

Failing to take advantage of discounts and coupons means missing out on potential savings. Keep an eye out for deals and promotions to stretch your dollars further. Many influencers on social media will post the best deals of the week, so you don’t have to do a lot of extra work to snag the most savings. You can also get helpful rebates on Ibotta and Fetch to help you offset the cost of groceries and everyday purchases.

14. Not Tracking Expenses
budget

Ignoring your daily spending habits can lead to financial leaks. Keep track of your expenses using budgeting apps or spreadsheets to identify areas where you can cut back. Knowledge is power when it comes to managing your finances. Many banking apps can help you set up a budget that makes sense for your financial goals.

15. Rewarding Yourself with Little Treats
treat yourself

Usually, when we’re stressed it’s easy to motivate ourselves with the thought of a little reward. This could be grabbing a drink after work, buying something you’ve been eyeing on Amazon, or getting a massage. While these treats are great for your well-being, it’s important to keep your financial goals in mind. Make sure treats don’t become daily habits that you justify by saying, “I deserve this.”, or “I don’t do this often.” Ultimately, treating yourself can have a heavy financial impact at the end of the month.

Considering Your Financial Well-Being
financial health

Being mindful of your daily habits is crucial for maintaining financial well-being and achieving long-term goals. Small changes, such as brewing your coffee at home, cooking meals instead of eating out, and turning off lights when leaving a room, can have a significant impact on your budget over time. By consistently making smart choices in your daily routine, you can save money, reduce unnecessary expenses, and allocate funds toward your financial priorities. Ultimately, practicing mindfulness in your daily habits empowers you to take control of your finances and build a more secure future.

Read More

12 Things You Should Never Do at a Casino

17 Odd Rituals People Do Behind Closed Doors

Teri Monroe
Teri Monroe
Teri Monroe started her career in communications working for local government and nonprofits. Today, she is a freelance finance and lifestyle writer and small business owner. In her spare time, she loves golfing with her husband, taking her dog Milo on long walks, and playing pickleball with friends.

Filed Under: Money and Finances Tagged With: Money Saving Tips, personal finance, Saving Money

Chill Out: 15 Ways to Slash Your Air Conditioning Costs This Summer

May 17, 2024 | Leave a Comment

air conditioning
123rf

As summer temperatures start to climb, so can our energy bills, thanks to our trusty air conditioners working overtime to keep us cool. But fear not! You don’t have to choose between staying comfortable and keeping your wallet happy. Whether you’re a savvy saver or just looking to cut costs where you can, these strategies are sure to keep your space and your savings comfortably chill all season long.

1. Embrace Smart Thermostats

thermostat
123rf

Invest in a smart thermostat—it’s like having a genie for your HVAC system. These clever devices learn your schedule and adjust temperatures accordingly, ensuring your AC only runs when you need it. You can control them from your smartphone, which means no more cooling an empty house. Users report saving up to 20% on their heating and cooling bills with this tech upgrade!

2. Seal the Deal

closing the window
123rf

Don’t let your cool air escape! Check your doors and windows for leaks and seal them up with weather-stripping or caulk. This simple fix can prevent air from leaking out and stop hot air from invading, making your AC system work less and saving you money. It’s an inexpensive project with a return that might surprise you.
3. Upgrade Your Insulation

wall insulation
123rf

Think of insulation like a thermos for your house. Upgrading your attic and wall insulation keeps your indoor temperatures stable by slowing the transfer of heat. This means your air conditioner won’t have to work overtime. Though the upfront cost can be higher, the long-term savings on your energy bills will be worth the investment.

4. Use Ceiling Fans

ceiling fan
123rf

Ceiling fans are the unsung heroes of energy efficiency. By circulating the air, fans can make a room feel up to seven degrees cooler. This allows you to set your thermostat higher without sacrificing comfort. Just remember to turn them off when you leave the room—fans cool people, not rooms.

5. Shade Your Space

window curtain
123rf

Sunlight streaming through windows can increase your indoor temperature significantly. Use curtains, blinds, or shades to block the heat during the hottest parts of the day. Consider planting trees or shrubs near sun-facing windows for a more natural—and beautiful—shade solution.

6. Maintain Your AC

aircon maintenance
123rf

An air conditioner is like a car—it needs regular check-ups to run efficiently. Ensure your AC unit is serviced annually to keep it running at peak performance. Clean or replace filters monthly during the summer to improve airflow and efficiency. This not only prolongs the life of your unit but also reduces energy consumption.

7. Cool Cooking

cooking outdoors
123rf

On hot days, avoid using the oven—grill outdoors, or opt for no-cook meals. Cooking inside can increase the temperature in your home, making your AC work harder. If you must cook inside, use a microwave or a slow cooker, which emits less heat.

8. Install Window Films

tinted window
123rf

Window films are like sunglasses for your home. They reflect solar heat away from your interior, helping to keep it cooler. These can be especially effective for homes with large, south-facing windows and can be a cost-effective alternative to double-pane windows.

9. Switch to LED Bulbs

led bulbs
123rf

Incandescent bulbs waste about 90% of their energy in the heat they emit. Switching to LED bulbs can reduce the heat output and lower your electricity consumption. As a bonus, LEDs last longer, saving money on replacements.

10. Use a Programmable Timer

aircon timer
123rf

Link your air conditioning to a programmable timer instead of running it continuously. Set it to turn on half an hour before you return home rather than leaving it running all day. This small adjustment can lead to significant savings over the course of the summer months.

11. Ventilate at Night

fan
123rf

If evenings are cooler, turn off the AC and open your windows while you sleep. This allows you to take advantage of the cooler air without cost. Just make sure to close the windows and blinds as soon as you wake up to trap the cool air inside.

12. Rethink Your Roof

roof
123rf

If it’s time to replace your roof, consider choosing a cool roofing material. These specially designed materials reflect more sunlight and absorb less heat than standard roofing, reducing your cooling needs by up to 10-15%.

13. Adjust Your Body Temperature

light clothes
123rf

Keep hydrated and wear light, loose-fitting clothes to feel cooler naturally without overly relying on your AC. Drinking cold beverages and applying a cold cloth to strong-pulsed areas like your neck and wrists can also help reduce your body temperature.

14. Zone Your Home

air vents
123rf

If you have central air, use zone systems to cool only parts of the house that are occupied. This way, you’re not wasting money cooling rooms no one is using. Smart vents can help with this by automatically adjusting airflow to different rooms.

15. Reflect Heat Away

light-colored room
123rf

Paint your home a lighter color if it’s due for a repaint. Lighter colors reflect the sun’s rays more effectively than darker ones. This can be a significant factor in reducing your cooling costs, especially if you live in a region that experiences intense sun.

Cooling Your Home Doesn’t Have to Be Pricey

a couple cooling down with an aircon
123rf

By implementing these strategies, you can enjoy a cooler home without the financial burn. Stay cool and save money this summer by giving these tips a try!

Read More

6 Super Easy Ways to Reduce Your Energy Costs This Fall

12 Reasons Why You Can’t Afford Summer Camp Anymore

Vanessa Bermudez
Vanessa Bermudez
Vanessa Bermudez is a content writer with over eight years of experience crafting compelling content across a diverse range of niches. Throughout her career, she has tackled an array of subjects, from technology and finance to entertainment and lifestyle. In her spare time, she enjoys spending time with her husband and two kids. She’s also a proud fur mom to four gentle giant dogs.

Filed Under: Money and Finances Tagged With: air conditioning, aircon, electric bills, energy consumption, summer heat

Affordable and Sensible Ways to Take Care of Your Garden Long-Term

May 16, 2024 | Leave a Comment

A garden is one of the best things that a family can have at home. In addition to being a productive hobby that enables you to spend time outdoors and be active, it also ensures that you have easy access to fresh herbs, vegetables, or even flowers. That’s why it’s best to make sure that if you have a garden, you take the best care of it so that you can get great returns for your efforts. Here are a few affordable and sensible ways in which you can take care of your garden over the long term.
Learn About Gardening Expenses

To make sure that you start off on the right foot, it’s a good idea to first learn about gardening expenses. Once you know what these are most likely to be as well as what you can expect from maintaining your garden properly, you can start to look into ways in which you can make savings. This is something that you can do by talking to other gardeners in your area and also doing some light research on the internet. You’re bound to find a lot of resources that are relevant to your area and your specific needs with your garden. This is because, according to The National Gardening Association, there were 18.3 million new gardeners this past year. Additionally, 83% of landscaping consumers searched for indigenous plant species that they could plant on their properties.

Find Out New Techniques from Other Gardeners

You can also take great care of your garden in the long term by learning about new techniques from other gardeners. This will help you take advantage of modern methods that are a lot more effective and efficient in terms of material use. While learning about emerging trends and techniques in gardening, you’ll come across facts such as that 90% of homeowners believe that it’s crucial to maintain their yard. In addition to this, two out of every three backyard owners say that they’d hire a professional tree service to help them take care of their shrubs, trees, and other woody plants, according to Harris. When you know what to do for the best results according to current trends, tools, and materials, you can keep a healthy garden a lot more easily and affordably.

Only Grow What You Need

You can also take great care of your garden sensibly and affordably by only growing what you need. To do this, you should do some research to see how much you can expect to reap from a given number of seedlings, stalks, or even a specified size of land. This way, you won’t buy more supplies than you need, and you won’t end up with more than you can use. You’re also going to save on the water that you use for your garden, noting that almost 20% of homes in America have an automatic irrigation system, according to the EPA, but not all of them are used efficiently. When you set up a manageable garden, it will be possible to keep all the systems in control and working their best.

Recycle and Reuse

Recycling and reusing can be applied to your home garden to help you take care of your garden affordably for a long time to come. One way to do this is by using the waste material when you harvest to start and maintain a compost pit. A compost pit will provide you with natural manure for your garden so that you can keep your crops healthy naturally. Find other ways to keep your garden as self-sustaining as possible, and it will be a lot better to manage.

These are a few of the most affordable and sensible ways to take proper care of your garden over the long term. With some practice and by talking to other gardeners in your area, you can learn and do better over time. Never hesitate to make changes to something that doesn’t work efficiently, since flexibility will allow you to set up a garden that will thrive.

Filed Under: Money and Finances

10 Reasons Nanny Sharing is the Ultimate Parenting Hack

May 16, 2024 | Leave a Comment

123rf

Nanny sharing has become a popular trend among parents seeking quality childcare without breaking the bank. This innovative approach involves two or more families sharing the services of a single nanny, providing numerous benefits. Here are ten reasons why nanny sharing is the ultimate parenting hack.

1. Cost Savings

123rf

One of the biggest advantages of nanny sharing is the significant cost savings. By splitting the nanny’s salary between two or more families, each family pays less than they would for a full-time nanny. This makes high-quality, personalized childcare more affordable. Additionally, families can save on other expenses, such as nanny benefits and taxes. The overall reduction in childcare costs can free up budget for other important family needs. Nanny sharing offers a financially smart solution for working parents.

2. Personalized Care

123rf

Nanny sharing provides personalized care that is often superior to daycare centers. Nannies can tailor their attention to the specific needs and preferences of the children they look after. This one-on-one interaction helps foster strong bonds and better understanding between the nanny and the children. Personalized care also allows for customized schedules and activities that suit each child’s developmental stage. Parents can have peace of mind knowing their children are receiving individualized attention. This level of care is hard to find in larger, more impersonal childcare settings.

3. Socialization Opportunities

123rf

Sharing a nanny offers excellent socialization opportunities for children. Kids benefit from interacting with their peers in a smaller, more controlled environment. This interaction helps them develop essential social skills such as sharing, communication, and empathy. Nanny sharing can mimic a sibling-like relationship, which can be beneficial for only children. Regular playdates and group activities organized by the nanny further enhance social development. These early social experiences can set a strong foundation for future relationships.

4. Flexibility in Scheduling

123rf

Nanny sharing provides greater flexibility in scheduling compared to traditional daycare centers. Parents can arrange hours that best suit their work and personal lives. This flexibility can include extended hours, weekends, and even overnight care if needed. Families can work together to create a schedule that meets everyone’s needs, reducing the stress of rigid daycare hours. Additionally, nannies can adapt to sudden changes or emergencies, offering a level of convenience that daycare centers often cannot. This adaptable approach helps parents maintain a better work-life balance.

5. Consistent Caregiver

123rf

Having a consistent caregiver is crucial for a child’s emotional development. Nanny sharing ensures that children interact with the same nanny regularly, providing stability and security. This consistent presence helps build a strong, trusting relationship between the child and the caregiver. In contrast, daycare centers often have high staff turnover, which can be unsettling for children. A consistent nanny also becomes familiar with the children’s routines, preferences, and needs, ensuring continuity of care. This stable environment supports healthy emotional and psychological growth.

6. Customizable Environment

123rf

With nanny sharing, parents can create a childcare environment that suits their values and preferences. Families can decide on the setting, whether it’s one family’s home or alternating between both homes. This control over the environment includes choosing age-appropriate toys, books, and activities. Parents can also ensure that dietary restrictions and nap schedules are adhered to. A familiar home setting can be more comfortable and less stressful for children compared to a daycare center. This customizable approach allows for a more personalized and nurturing environment.

7. Shared Parenting Insights

Dall-E

Nanny sharing offers parents the opportunity to share insights and parenting tips. Collaborating with another family can provide new perspectives and strategies for raising children. This shared knowledge can be particularly valuable for first-time parents. Parents can also support each other through challenges and milestones, creating a sense of community. Regular communication and cooperation between families can enhance the overall childcare experience. This collaborative approach benefits both the children and the parents involved.

8. Enhanced Safety and Supervision

123rf

Nanny sharing often leads to enhanced safety and supervision for children. With a lower child-to-caregiver ratio compared to daycare centers, nannies can provide more attentive care. Parents can also establish clear guidelines and expectations for safety and discipline. Regular check-ins and open communication with the nanny ensure that parents stay informed about their children’s well-being. Additionally, having another family involved provides an extra layer of accountability and oversight. This heightened supervision ensures a safer environment for children.

9. Simplified Logistics

123rf

Nanny sharing can simplify logistics for busy families. Coordinating drop-offs and pick-ups with another family can be more convenient than navigating daycare schedules. Families can alternate responsibilities, such as providing meals or hosting playdates, reducing the individual burden on each family. This collaboration can streamline daily routines and reduce stress for parents. Additionally, children benefit from a consistent routine, making transitions smoother and less disruptive. Simplified logistics help create a more manageable and efficient childcare arrangement.

10. Stronger Community Bonds

123rf

Nanny sharing can foster stronger bonds within the community. Families involved in a nanny share often develop close relationships, creating a supportive network. These connections can extend beyond childcare, offering social and emotional support. Shared experiences and mutual trust strengthen community ties. This sense of community can be particularly valuable for families new to an area or without nearby relatives. Stronger community bonds contribute to a more connected and resilient support system.

Embracing the Benefits of Nanny Sharing

123rf

Nanny sharing is an innovative solution that offers numerous benefits for modern families. From cost savings and personalized care to enhanced safety and community support, it’s no wonder that more parents are embracing this approach. By considering nanny sharing, parents can provide high-quality childcare while enjoying greater flexibility and peace of mind. This ultimate parenting hack is a game-changer for families seeking the best for their children. Embrace the advantages of nanny sharing and discover a smarter way to navigate the challenges of parenting.

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.  As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy.

Filed Under: Money and Finances Tagged With: Cost Savings, Flexibility in Scheduling, Nanny Sharing, Socialization Opportunities

16 Life Lessons from Fairy Tales We Shouldn’t Forget

May 15, 2024 | Leave a Comment

123rf

Fairy tales have been a staple of childhood for generations, offering more than just entertainment. These timeless stories are rich with wisdom and lessons that remain relevant throughout our lives. Here are sixteen life lessons from fairy tales that we should always remember.

1. Believe in Yourself (Cinderella)

123rf

Cinderella teaches us the importance of self-belief. Despite her harsh circumstances, she never loses hope or faith in herself. Her perseverance and belief in her own worth ultimately lead her to happiness. This lesson reminds us that confidence and self-belief are key to overcoming obstacles. When we believe in ourselves, we can achieve great things. Never underestimate the power of a positive mindset.

2. Kindness Matters (Beauty and the Beast)

123rf

Beauty and the Beast shows the transformative power of kindness. Belle’s kindness and empathy towards the Beast help break his curse. This tale emphasizes that true beauty comes from within and that kindness can change lives. Practicing kindness can build strong relationships and create a positive impact. Remember to treat others with compassion and understanding. Kindness is a universal language that everyone appreciates.

3. Bravery Is Essential (Jack and the Beanstalk)

DALL-E

Jack and the Beanstalk teaches the importance of bravery. Jack’s courage in facing the giant leads to his success and prosperity. This story encourages us to take risks and face our fears head-on. Bravery often leads to personal growth and unexpected rewards. Don’t let fear hold you back from pursuing your dreams. Sometimes, the biggest rewards come from the bravest actions.

4. Hard Work Pays Off (The Little Red Hen)

123rf

The Little Red Hen highlights the value of hard work and self-reliance. The hen’s diligence in planting, harvesting, and baking pays off, while those who refused to help miss out. This story underscores that effort and perseverance lead to success. It’s a reminder that laziness and entitlement don’t yield results. Hard work and dedication are crucial in achieving our goals. Always be willing to put in the effort for what you want.

5. Be Wary of Strangers (Little Red Riding Hood)

123rf

Little Red Riding Hood teaches us to be cautious and discerning. The protagonist’s encounter with the deceptive wolf highlights the dangers of trusting strangers blindly. This lesson is crucial in today’s world, where not everyone has good intentions. It’s important to stay vigilant and protect ourselves and our loved ones. Trust your instincts and be mindful of who you let into your life. Safety and awareness are paramount.

6. Use Your Wits (Hansel and Gretel)

123rf

Hansel and Gretel demonstrates the importance of cleverness and resourcefulness. The siblings use their wits to navigate danger and escape from the witch. This story reminds us that intelligence and quick thinking can save us in tough situations. Being resourceful helps us solve problems and overcome challenges. Always think on your feet and use your skills to navigate life’s difficulties. Cleverness is a valuable asset in any situation.

7. Don’t Be Greedy (King Midas)

123rf

The story of King Midas warns against the dangers of greed. Midas’s insatiable desire for wealth leads to his downfall and misery. This tale teaches us that greed can destroy our happiness and relationships. Contentment and gratitude are essential for a fulfilling life. Pursue your goals, but don’t let greed overshadow your values. Remember that true wealth comes from appreciating what you already have.

8. Stay True to Yourself (The Ugly Duckling)

123rf

The Ugly Duckling highlights the importance of self-acceptance. The protagonist’s journey from feeling out of place to discovering his true identity is inspiring. This story teaches us that embracing who we are is crucial for happiness. Everyone’s uniqueness is what makes them special. Don’t try to conform to others’ expectations; be proud of who you are. Self-acceptance is the key to a fulfilling life.

9. Perseverance Wins (The Tortoise and the Hare)

123rf

The Tortoise and the Hare shows that slow and steady wins the race. The tortoise’s perseverance and steady effort lead him to victory over the overconfident hare. This story teaches us that consistent effort and determination are more important than speed. Patience and persistence are crucial for achieving long-term goals. Don’t get discouraged by setbacks or others’ success. Keep moving forward at your own pace.

10. The Power of Love (Sleeping Beauty)

123rf

Sleeping Beauty illustrates the enduring power of love. True love’s kiss breaks the spell and awakens the princess, symbolizing love’s ability to overcome obstacles. This tale reminds us that love is a powerful force in our lives. It can heal, inspire, and transform us. Cherish and nurture your relationships, as they are a source of strength. Love has the power to bring out the best in us and others.

11. Think Before You Act (Rumpelstiltskin)

DALL-E

Rumpelstiltskin emphasizes the importance of thinking before making promises. The miller’s daughter’s hasty promise leads to trouble and stress. This story teaches us to consider the consequences of our actions and words. Making rash decisions can lead to regret and unforeseen problems. Always take a moment to think things through. Thoughtful actions are crucial for avoiding unnecessary complications.

12. Honesty Is the Best Policy (Pinocchio)

123rf

Pinocchio teaches the value of honesty and integrity. The protagonist’s lies cause him a lot of trouble and only when he learns to be truthful does he find happiness. This story underscores that honesty builds trust and strong relationships. Lies may provide temporary relief, but they eventually lead to more significant problems. Being truthful is essential for personal growth and genuine connections. Integrity is the foundation of a good character.

13. Appreciate Nature (Thumbelina)

123rf

Thumbelina highlights the beauty and importance of nature. The protagonist’s adventures in the natural world show us the wonders and serenity that nature offers. This story encourages us to appreciate and protect our environment. Spending time in nature can provide peace, inspiration, and a sense of wonder. Remember to take care of our planet for future generations. Nature is a precious gift that we must cherish.

14. Friendship Is Valuable (The Snow Queen)

123rf

The Snow Queen demonstrates the power of friendship and loyalty. Gerda’s unwavering friendship and determination to save Kai highlight the strength of true bonds. This tale teaches us that friends can provide support and help us overcome challenges. Valuing and nurturing friendships is essential for a happy life. Loyal friends are treasures that enrich our lives. Always appreciate and be there for your friends.

15. Beauty Is More Than Skin Deep (The Frog Prince)

123rf

The Frog Prince reminds us that true beauty lies within. The princess learns to see the prince’s inner qualities beyond his outward appearance. This story teaches us to look beyond physical appearances and value inner virtues. Kindness, honesty, and integrity are the true markers of beauty. Don’t judge others based on looks; get to know their character. Inner beauty creates lasting impressions.

16. Hope Is Powerful (Pandora’s Box)

123rf

Pandora’s Box teaches the importance of hope in difficult times. Even after releasing all the world’s troubles, Pandora finds hope at the bottom of the box. This story reminds us that hope can sustain us through challenges and hardships. It encourages us to stay optimistic and believe in better days. Hope is a powerful force that can inspire resilience and perseverance. Never lose hope, no matter how tough life gets.

Embracing Timeless Wisdom

123rf

Fairy tales offer timeless wisdom that continues to be relevant in our lives. By embracing these lessons, we can navigate challenges and build a better future. Remember the importance of kindness, bravery, and honesty. Stay true to yourself and appreciate the power of love and friendship. These stories remind us of the values that truly matter. Keep these life lessons close to your heart and let them guide you.

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.  As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy.

Filed Under: Money and Finances Tagged With: Hansel and Gretel, Jack and the Beanstalk, Little Red Riding Hood, The Little Red Hen

My Mom Has Dementia – 9 Steps To Protect Your Parents’ Assets During Mental Health Challenges

May 15, 2024 | Leave a Comment

Protect your parents' assetsAs our parents age and possibly face mental health challenges, their ability to manage financial affairs can diminish. This vulnerability makes them potential targets for financial abuse, fraud, and poor financial decisions that can deplete their life savings. Proactive steps are crucial to safeguard their assets, ensuring their financial security and peace of mind. This guide outlines nine essential actions to help you protect your parents’ assets during challenging times.

1. Understand Their Financial Situation

The first step to protect your parents’ assets is to fully understand their financial situation. This includes knowing the details of all their assets, such as bank accounts, investment accounts, real estate holdings, and personal property. Additionally, be aware of their liabilities, including any debts or recurring expenses. Gathering all relevant financial documents and compiling a comprehensive list will provide a clear overview of their finances and help in making informed decisions.

2. Legal Financial Planning

Consulting an attorney specialized in elder law is crucial for setting up legal mechanisms that protect your parents’ assets. This might involve setting up a durable power of attorney (POA), which lets a family member or friend manage financial affairs if your parents are unable to do so themselves. Other legal structures, such as trusts, can also be effective tools for managing and protecting assets. The attorney can also advise on the best legal structures to minimize taxes and maximize financial security.

3. Establish a Durable Power of Attorney

A durable power of attorney for finances is a legal document that grants a trusted individual the authority to handle financial decisions on behalf of your parents. Ensure this document is drafted while your parents are still capable of making decisions to avoid complications later. The appointed agent should be someone highly trustworthy and capable of handling financial responsibilities with integrity. They should also have a good understanding of your parents’ wishes and best interests.

4. Regularly Review Bank Statements

Keep an eye on your parents’ bank and credit card statements for unusual activity. Look for unauthorized withdrawals, unusual transactions, or any signs of financial exploitation. It’s also important to understand their spending habits, which can help in identifying any significant changes that might warrant further investigation. Setting up alerts for high-value transactions can also help monitor and protect their finances effectively.

5. Simplify Financial Accounts

If your parents have multiple bank accounts, investments, or credit cards, consider consolidating them. This reduces the complexity of their finances, making it easier to manage and monitor. It also reduces the risk of forgetting about certain assets or accounts. Choose institutions that offer robust security measures and fraud protection services.

6. Secure Important Documents

All critical financial documents should be stored securely in a fireproof safe, safe deposit box at a bank, or another secure location. Important documents include birth certificates, marriage certificates, social security cards, wills, deeds, and insurance policies. Proper storage prevents these documents from being lost, stolen, or damaged, which could complicate financial management and asset protection. It also ensures the documents are accessible when needed.

7. Monitor Credit Reports

Regular monitoring of your parents’ credit reports can help detect any unauthorized activities or accounts opened in their names, which are common signs of identity theft. You can obtain a free credit report from each of the three major credit reporting agencies once a year through AnnualCreditReport.com. This is a preventative measure to catch identity theft early, which can be particularly damaging to seniors. You can also encourage them to freeze their credit, which prevents creditors from accessing their credit reports and stops new accounts from being opened in their name.
8. Discuss Financial Decisions Openly

Maintain open lines of communication with your parents about their finances. Ensure they feel involved in the decision-making process as much as possible, respecting their independence. Discuss their wishes, goals, and preferences openly and make sure any financial decisions align with their long-term interests. This includes involving them in meetings with financial advisors or attorneys whenever feasible. This also includes discussing their plans with other family members to ensure everyone is informed and any actions taken are transparent.
9. Educate Them About Scams

Frequently discuss and educate your parents about potential scams, especially those targeting elderly individuals. This includes phone scams, mail fraud, and online phishing attacks. Empower them with information on how to recognize scams and stress the importance of not sharing personal information. Discussing the signs of scams and preventive measures can help them remain vigilant and protect themselves against potential fraudsters.

Ensuring Financial Integrity

To protect your parents’ assets in the face of mental health challenges is a profound responsibility that involves planning, vigilance, and a lot of heart. By implementing these steps, you help secure not just their financial resources but also their dignity and quality of life. Moving forward, continue to advocate for their needs, ensuring they are respected and protected as they navigate this phase of their lives. Remember, the goal is to manage their assets wisely and compassionately, keeping their best interests in mind.

[Read more…]

Toi Williams
Toi Williams

Toi Williams began her writing career in 2003 as a copywriter and editor and has authored hundreds of articles on numerous topics for a wide variety of companies. During her professional experience in the fields of Finance, Real Estate, and Law, she has obtained a broad understanding of these industries and brings this knowledge to her work as a writer.

Filed Under: Money and Finances Tagged With: assets, Family Finance, Finances, financial planning

10 Surprising Reasons Millennials Are Struggling to Purchases Homes

May 14, 2024 | Leave a Comment

millennials struggling to purchase homes

The dream of owning a home has long been ingrained in the American ethos, symbolizing stability, independence, and success. However, for many millennials, this dream seems increasingly elusive. According to Statista, since 2011, the median price of an existing single-family home in the United States has increased by around 50 percent. Despite being one of the largest demographic cohorts in the workforce, millennials are facing significant hurdles when it comes to purchasing homes. While factors such as student debt and rising housing costs are well-documented, there are several surprising reasons contributing to millennials struggling to purchase homes.

1. High Interest Rates

interest rates

According to Statista, in the United States, interest rates for all mortgage types started to increase in 2021. This was due to the Federal Reserve introducing a series of hikes in the federal funds rate to contain the rising inflation. In the second quarter of 2023, the 30-year fixed rate reached 6.49 percent, up from 5.24 percent in the same quarter of 2022.

High mortgage interest rates significantly impact the affordability of purchasing a home, as they directly influence monthly mortgage payments. When interest rates are high, potential homebuyers may find themselves priced out of the market or forced to settle for smaller, less desirable properties. The higher the interest rates, the more expensive borrowing becomes, reducing the purchasing power of prospective buyers and increasing the overall cost of homeownership. Ultimately, high interest rates are one of the main reasons millennials are struggling to purchase homes.

2. Limited Inventory

limited inventory

With many Boomers choosing to age in place, many homes are not being put on the housing market. Limited supply is also further driving up the price of homes, often resulting in bidding wars. Millennials who need financing are usually the ones to lose out, often outbid by buyers who can present deals that are all cash with no contingencies. This has resulted in a frustrating homebuying experience for many millennials.

3. Changing Job Market Dynamics

millennials struggling to purchase homes

The modern job market is characterized by gig economy jobs, freelance work, and contract positions. While these types of employment offer flexibility, they often lack the stability and benefits necessary to qualify for a mortgage, making it harder for millennials to secure home loans. The rise of the gig economy has led to irregular income streams for many millennials. Lenders traditionally favor steady, predictable income, making it difficult for those in gig economy roles to meet mortgage requirements.

4. Skyrocketing Cost of Healthcare

thinking about home

Healthcare costs in the United States have been steadily rising, eating into millennials’ disposable income and making it harder to save for a down payment. Many millennials don’t have enough emergency fund savings to cover unexpected medical bills. Furthermore, many millennials struggle to pay their deductibles, especially since many have high-deductible plans. Additionally, the burden of medical debt can adversely affect millennials’ credit scores, further hindering their ability to qualify for mortgages. Altogether, rising medical costs are further compounding the issues of millennials struggling to purchase homes.

5. Delaying Marriage and Children

delaying marriage

Millennials are delaying marriage and children at unprecedented rates, reshaping traditional notions of family and homeownership. Factors such as pursuing higher education, establishing careers, and prioritizing personal fulfillment have contributed to this trend. Additionally, economic uncertainty, high housing costs, and mounting student loan debt have made millennials hesitant to take on the financial responsibilities associated with starting a family. The shift towards delaying marriage and children has also impacted the housing market, as many millennials opt for rental accommodation or delay homeownership altogether.

6. Student Loan Debt Crisis

can't afford home

Roughly one in five Americans have student loan debt. Today, most students graduate with an average of $30,000 in loans. Millennials are shouldering unprecedented levels of student loan debt, which can severely limit their ability to save for a down payment and qualify for affordable mortgage rates. The weight of this debt often delays homeownership or forces millennials to settle for less desirable housing options.

7. Rising Cost of Living

rising cost of living

While wages have stagnated in many sectors, the cost of living continues to rise, particularly in housing markets with high demand. In 2023, inflation rose to over 9%, a forty-year high. At that time, it was estimated that Americans would have to spend an extra $11,434 to maintain the style of living that they enjoyed in 2021. The discrepancy between income and expenses makes it increasingly challenging for millennials to afford homes, particularly in metropolitan areas.

8. Impact of The Great Recession

impact of the Great Recession

Many millennials entered the workforce during or shortly after the Great Recession of 2008, which had a lasting impact on their financial stability. High unemployment rates and stagnant wage growth during this period delayed millennials’ ability to save for down payments and recover financially, setting them back in their quest for homeownership. As a result, many millennials feel behind in their career and finances. No generation before has been saddled with so much financial baggage.

9. Mistrust in The Housing Market

millennials struggling to purchase homes

Millennials harbor a deep-seated mistrust in the housing market, stemming from the scars of the 2008 financial crisis. Many witnessed the devastating consequences of predatory lending, subprime mortgages, and the subsequent collapse of the housing bubble, leading to widespread foreclosures and financial ruin. This traumatic experience has left a lasting impression on millennials, shaping their perceptions of homeownership and investment. As a result, millennials approach the housing market with caution, seeking transparency, stability, and fair practices from lenders and real estate professionals. The legacy of the housing crisis continues to influence millennials’ decisions, prompting them to thoroughly research and scrutinize housing options before committing to a purchase.

10. Environmental Concerns

increased housing cost

Millennials are more environmentally conscious than previous generations, leading many to prioritize eco-friendly and sustainable living options. They seek energy-efficient features such as solar panels, smart thermostats, and eco-friendly building materials to minimize their carbon footprint and reduce utility costs. Additionally, millennials gravitate towards homes located in walkable neighborhoods with access to public transportation, bike lanes, and green spaces, promoting a more sustainable lifestyle. Many are also drawn to properties with low-maintenance landscaping and water-saving fixtures, aligning with their desire for environmentally conscious living. However, homes with green features often come with a premium price tag, making them less affordable for young homebuyers with limited financial resources.

Obstacles to Homeownership

millennials struggling to purchase homes

The path to homeownership for millennials is fraught with challenges that extend beyond the well-documented issues of student debt and rising housing costs. From shifting societal preferences to structural changes in the economy, millennials face a unique set of obstacles that make purchasing a home increasingly difficult. Addressing these challenges will require innovative solutions from policymakers, lenders, and the real estate industry to ensure that homeownership remains within reach for this generation.

Read More

Are Luxury Handbags a Good Investment? 11 Bags That Have The Highest Resale Value

13 Interview Topics That Invade Privacy and How to Avoid Them

Teri Monroe
Teri Monroe
Teri Monroe started her career in communications working for local government and nonprofits. Today, she is a freelance finance and lifestyle writer and small business owner. In her spare time, she loves golfing with her husband, taking her dog Milo on long walks, and playing pickleball with friends.

Filed Under: Money and Finances Tagged With: housing market, inflation, Millennials, mortgage rates

The Kids Are Listening: 10 Things You Should Never Discuss Around Your Kids

May 14, 2024 | 4 Comments

123rf

Raising children in today’s interconnected and media-rich world means they are often more aware and exposed to various topics than previous generations. However, certain topics should still be kept away from young ears. Here are ten subjects that are best discussed out of earshot of children; to help maintain their innocence and ensure they are not burdened with adult concerns before it’s necessary.

1. Financial Worries

123rf

Kids need a secure environment to thrive, and overhearing discussions about financial instability can cause unnecessary anxiety. Whether it’s about overdue bills, loan dependencies, or the cost of living, these issues can create a sense of insecurity and fear. It’s vital to keep such conversations private, as children might feel they are to blame or may worry excessively about the future. Even if financial strain is a reality, consider discussing these matters away from your kids to avoid transferring stress onto them. Instead, teach them about money management through age-appropriate conversations that build confidence rather than concern. Let them know about budgeting and saving but spare them the weight of financial crises.

2. Marital Issues

123rf

Disagreements and conflicts are normal in any relationship, but they should not be handled in front of children. Discussing marital issues, like arguments over intimacy or disagreements on parenting, can be distressing for kids who might feel caught in the middle. It’s important to model healthy communication without exposing children to the complexities of adult relationships that they are not equipped to understand. This helps maintain a sense of normalcy and security within the home. Always aim to resolve conflicts away from young ears, or better yet, seek professional guidance to handle sensitive issues.

3. Criticizing Other Family Members

123rf

Speaking negatively about other family members can lead to confusion and conflict in a child’s mind. It can also teach them that it is acceptable to talk behind someone’s back. Preserve the integrity of family relationships by keeping adult criticisms to yourself. If you must vent or discuss behaviors of family members, do it in an environment where children are not present. Encourage a culture of openness where issues are addressed directly with the person concerned, thus fostering a positive atmosphere in the home.

4. World Crises

123rf

While it’s important to educate children about the world, detailed discussions about global crises like wars, pandemics, or natural disasters should be handled delicately. Kids can feel very small and powerless against such large-scale problems. Frame these conversations in a way that is appropriate for their age and understanding. Offer reassurance about their immediate safety and avoid delving into distressing specifics unless they are old enough to process the information constructively.

5. Your Own or Others’ Legal Issues

123rf

Legal problems, whether they’re personal or concerning someone they know, can be particularly confusing and worrying for children. They often do not understand the complexities of the law, and knowing someone they love is involved in legal proceedings can be quite distressing. Keep such discussions private, focusing instead on providing a stable environment for your children. If questions arise from what they might have overheard, answer them in a way that is reassuring and appropriate for their age.

6. Adult Health Issues

123rf

Serious health diagnoses within the family or friend circle are not easy topics for children to deal with. They can easily misinterpret what such diagnoses entail, potentially leading to unnecessary fear about their own health or that of others. Discuss these issues with discretion and not in the presence of your kids. Instead, explain health situations in a way that is honest yet considerate of their emotional well-being.

7. Sexual Content

123rf

Discussions about sexual matters should be age-appropriate and not include adult-themed content or jokes. Exposing children to adult sexual content inadvertently can lead to confusion and inappropriate behaviors. Keep adult conversations private and discuss human sexuality with your children in a way that is educational and suitable for their stage of development.

8. Substance Use

123rf

Conversations about the use of alcohol, drugs, or tobacco should be approached with caution around children. While it’s essential to educate them about the dangers of substance abuse, it’s also important not to discuss personal use or abuse in their presence. This helps prevent normalizing such behavior and encourages healthy lifestyle choices instead.

9. Overly Sophisticated Jokes or Sarcasm

123rf

Kids often take words at face value and can miss the nuance behind sarcasm or sophisticated humor. This can lead to misunderstandings or them repeating inappropriate jokes without understanding the context. Keep the comedy kid-friendly when they are within earshot.

10. Gossip

123rf

Gossip can be harmful and overhearing it can teach children unhealthy communication habits. Discussions that involve gossiping about others’ misfortunes or personal life should be avoided around children to foster a sense of respect and integrity.

Creating a Child-Friendly Conversation Space

123rf

Fostering a positive atmosphere where children feel safe and loved involves careful consideration of what is discussed around them. By maintaining a child-friendly conversation space, parents can protect their children from undue stress and anxiety, setting the stage for open, honest, and age-appropriate communication. This not only helps in nurturing well-rounded individuals but also in building a strong foundation of trust and security in their formative years.

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.  As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy.

Filed Under: Money and Finances Tagged With: Criticizing Other Family Members, Kids Are Listening, Marital Issues, World Crises

Are Luxury Handbags a Good Investment? 11 Bags That Have The Highest Resale Value

May 10, 2024 | Leave a Comment

luxury handbags

Luxury handbags have long been coveted as fashion statements, but are they also wise investments? First off, luxury bags are known for their unsurpassed quality, as well as their several thousand dollar price tag. A single bag can take an expert craftsman up to 40 hours to make.

Moreover, brands are careful to keep their handbags super exclusive, only increasing demand and piquing the interest of collectors. Luxury bags either retain or increase their value over time.

Here are 11 iconic bags renowned for their impressive resale prices.

1. Chanel Classic Flap Bag

making a leather bag

With its timeless design and prestigious brand name, the Chanel Classic Flap Bag remains a top choice for collectors and investors alike. Its enduring popularity ensures a strong resale market and consistently high prices. The Chanel Classic Flap Bag stands as an emblem of timeless elegance and sophistication in the world of luxury fashion. First introduced by Coco Chanel herself in the 1950s and later revamped by Karl Lagerfeld in the 1980s, this iconic handbag has cemented its status as a must-have accessory for fashion enthusiasts and collectors alike.

Crafted from the finest lambskin or caviar leather, the Classic Flap Bag boasts Chanel’s signature quilted pattern, a design element inspired by the cushions in Mademoiselle Chanel’s apartment. Its timeless silhouette features a sleek rectangular shape adorned with the iconic interlocking CC logo closure, symbolizing the brand’s rich heritage and enduring allure.

2. Hermès Birkin Bag

luxury handbags

Arguably the holy grail of handbags, the Hermès Birkin is synonymous with luxury and exclusivity. Its limited availability and meticulous craftsmanship contribute to its exceptional resale value, making it a coveted investment piece. Renowned for its meticulous construction and use of the finest materials, each Birkin bag is a masterpiece in its own right, crafted by skilled artisans over countless hours. Its limited availability and high demand contribute to its exceptional resale value, with certain rare or coveted versions fetching astronomical prices on the secondary market.

The Birkin’s enduring popularity among fashion connoisseurs and celebrities ensures a strong demand for both new and pre-owned bags, further driving up its resale prices. As a result, the Hermès Birkin Bag has become not only a coveted accessory but also a lucrative investment opportunity for those fortunate enough to acquire one. A Himalaya Birkin, crafted from Niloticus crocodile skin and featuring Palladium Hardware, was especially prized and sold at Sotheby’s for over $450,000.

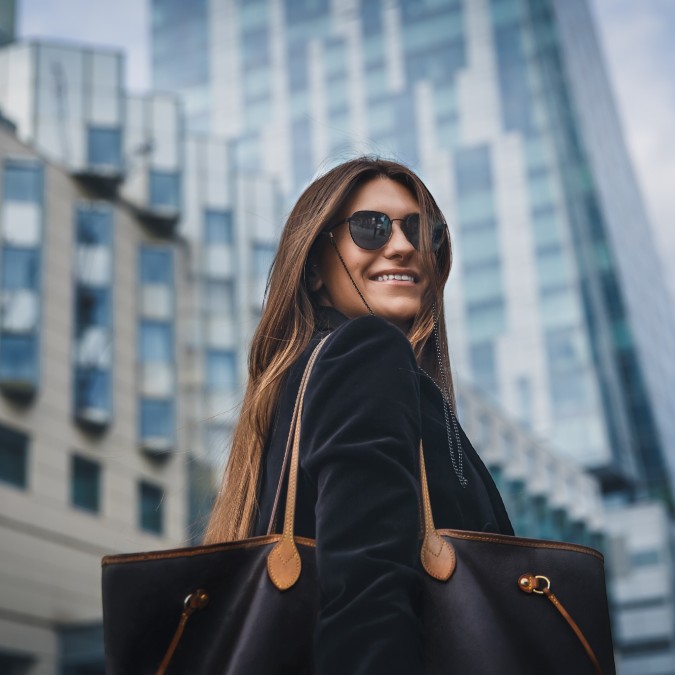
3. Louis Vuitton Neverfull

woman with tote bag

As one of Louis Vuitton’s most iconic designs, the Neverfull tote boasts both style and practicality. Its versatile appeal and enduring popularity translate to strong resale demand, particularly for well-maintained, limited-edition versions. With its spacious interior, sturdy construction, and iconic monogram canvas, it’s the perfect companion for everyday use or travel.

The bag’s versatile design features adjustable side laces that allow for customization of its shape and size, accommodating varying needs and preferences. Loved by fashion enthusiasts worldwide, the Louis Vuitton Neverfull continues to be a timeless staple in the luxury handbag market, admired for its enduring appeal and practical elegance.

4. Hermès Kelly Bag

handbags

The Hermès Kelly Bag, named after the actress and Princess of Monaco, Grace Kelly, exudes timeless elegance and sophistication. Originally designed in the 1930s, its iconic silhouette and meticulous craftsmanship have made it a symbol of luxury and status.

Crafted from the finest materials, including luxurious leathers such as Togo, Clemence, and Epsom, each Kelly bag is handcrafted by skilled artisans, resulting in impeccable quality and attention to detail. Its distinctive top handle and structured shape evoke a sense of refined glamour, making it a favorite among fashion icons and collectors worldwide. The Hermès Kelly Bag’s exclusivity and enduring appeal ensure its place as one of the most coveted and prestigious handbags in the world, with certain rare or exotic versions commanding premium prices on the resale market.

5. Chanel Boy Bag

sophisticated

The Chanel Boy Bag represents a bold departure from the brand’s classic designs, offering a modern and edgy aesthetic. Launched in 2011 under the creative direction of Karl Lagerfeld, it quickly became a symbol of contemporary luxury.

Featuring clean lines, a structured silhouette, and distinctive hardware, the Boy Bag exudes a sense of urban sophistication. Its versatility makes it a versatile accessory for both day and night, effortlessly complementing a variety of outfits. With its timeless appeal and association with the Chanel legacy, the Boy Bag continues to captivate fashion enthusiasts and collectors worldwide, solidifying its status as a coveted icon in the realm of luxury handbags. Its popularity contributes to its strong resale value, particularly for limited-edition or rare colorways.

6. Gucci Dionysus Bag

handbags in store

Named after the Greek god of fertility, Dionysus has an old-school shape and a horseshoe buckle that has captured the hearts of fashion enthusiasts. In some places, the Dionysus bag has increased by as much as 22% within just a few years. The Dionysus bag is one of the popular modern Gucci handbag styles, with the Marmont bags a close second. According to TheRealReal’s luxury retail report, Gucci was the most searched brand on their site in 2023, demonstrating the brand’s popularity.

7. Balenciaga City Bag

looking in purse

Renowned for its slouchy silhouette and distinctive hardware, the Balenciaga City Bag has maintained its status as a coveted accessory since its debut in the early 2000s. A favorite of Mary Kate and Paris Hilton alike, the City Bag retails for anywhere between $2,000-$3,000. While resale prices may vary depending on condition and rarity, well-maintained vintage pieces can still command a premium.

8. Prada Galleria Bag

sitting on bench

Praised for its understated elegance and impeccable craftsmanship, the Prada Galleria Bag embodies timeless sophistication. First released in 2007, the Galleria Bag epitomizes quiet luxury. While it may not reach the same resale heights as some other luxury brands, it remains a solid investment option due to its enduring appeal and classic design. A large Galleria bag can cost as much as $5,000 but will last a lifetime.

9. Saint Laurent Sac de Jour

designer handbag

The Saint Laurent Sac de Jour epitomizes Parisian chic with its sleek silhouette and minimalist design. Crafted from luxurious leather and adorned with subtle hardware, it exudes understated elegance and sophistication. Its structured shape and spacious interior make it ideal for both work and leisure, providing functionality without compromising on style. Loved by celebrities and fashion aficionados alike, the Sac de Jour has earned its place as a timeless classic in the world of luxury handbags. Its minimalist aesthetic and enduring popularity ensure a steady demand on the resale market, particularly for coveted colorways and limited editions.

10. Dior Lady Dior Bag

handbag

The Dior Lady Dior Bag, named in honor of Princess Diana, is a true icon of elegance and grace. Featuring soft lambskin leather and the iconic quilted pattern, it exudes timeless sophistication. Adorned with the signature ‘D.I.O.R’ charms and sturdy top handles, it exudes a sense of luxury and refinement. As a beloved accessory among celebrities and fashion enthusiasts, the Lady Dior bag continues to captivate with its timeless appeal and association with the storied heritage of the House of Dior. The Lady Dior Bag has a strong resale value, particularly for vintage or limited-edition versions.

11. Bottega Veneta The Pouch

bag outside

Launched in 2019, the Bottega Veneta Pouch quickly became a fashion sensation with its distinctive gathered silhouette and buttery soft leather. A modern, sleek design inspired many influencers and fashion aficionados. While relatively new compared to other classics, The Pouch was discontinued in 2023. Since it can now only be found on the resale market, it is commanding impressive prices.

Investing in Luxury

handbag on shelf

While luxury handbags can indeed be lucrative investments, success depends on various factors such as brand reputation, rarity, condition, and market trends. While some bags may hold their value or even appreciate over time, others may experience fluctuations or depreciation. Ultimately, investing in luxury handbags requires careful research, discernment, and a passion for both fashion and finance. If you are unsure of your luxury bag’s resale value, you can always contact a trusted luxury reseller like FarFetch, TheRealReal or Rebag to get a better idea.

Read More

Your Money Your Choice: 15 Decisions You Can Make to Kickstart Your Financial Independence

13 Secrets of Longevity: What People Living to 100 Eat Every Day

Teri Monroe
Teri Monroe
Teri Monroe started her career in communications working for local government and nonprofits. Today, she is a freelance finance and lifestyle writer and small business owner. In her spare time, she loves golfing with her husband, taking her dog Milo on long walks, and playing pickleball with friends.

Filed Under: Money and Finances Tagged With: designer handbags, luxury handbags, luxury investment, luxury resale, value retention

13 Mistakes Your Financial Advisor Should Never Make On Your Behalf

May 10, 2024 | Leave a Comment

financial advisorNavigating your financial landscape can be complex and fraught with potential pitfalls, which is why many turn to financial advisors for guidance. However, even experts can make errors. Knowing what mistakes to watch for in your financial advisor’s conduct can help you avoid unnecessary risks and protect your financial future. Here are 13 mistakes that should raise red flags if committed by your financial advisor.

1. Lack of Clear Communication

Effective communication is crucial in any advisory relationship, especially when it involves your finances. Your financial advisor should be transparent and proactive in all communications with you. They should keep you well-informed about every decision and action taken on your behalf, ensuring that you understand the implications and rationale behind each investment choice. Regular updates, clear explanations of complex financial products, and the implications of shifts in your financial strategy are essential to building trust and ensuring that you are never left guessing about the status of your finances. Miscommunications or omissions can lead to serious misunderstandings, potentially resulting in financial setbacks that could have been avoided with clearer dialogue.

2. Not Tailoring Advice to Your Financial Goals

Your financial advisor’s recommendations should be customized to align with your personal financial goals, risk tolerance, and investment horizon. It’s a significant red flag if your advisor offers generic advice that doesn’t seem to match your specific needs or if they push products that benefit them more than they benefit you. An advisor should take the time to thoroughly understand your financial situation and tailor their advice accordingly. This personalized approach ensures that the strategies implemented are suited to your long-term objectives and are flexible enough to adjust to changes in your life or financial circumstances.

3. Ignoring Risk Tolerance

Acknowledging and respecting your risk tolerance is a fundamental duty of any financial advisor. They should regularly assess how comfortable you are with risk and adjust your portfolio to reflect any changes in your risk appetite. Ignoring this can lead to investing in products that make you uncomfortable, potentially causing stress or financial loss. An advisor who continuously pushes you into investments that feel too aggressive or too conservative for your liking is not serving your best interests. Regular discussions about risk and comfort levels are important to ensure that your investment strategy remains aligned with your personal preferences.

4. Failing to Diversify Your Portfolio

Diversification is key to reducing risk in your investment portfolio. If your advisor concentrates a large portion of your investments in a single stock, sector, or asset class, it exposes you to undue risk. A well-diversified portfolio spreads out risk and can lead to more stable returns over time. Advisors who neglect to diversify your investments may lack understanding of basic investment principles or may be negligently managing your funds. Ensuring that your portfolio is diversified across various asset classes, industries, and geographies is crucial to managing potential losses and achieving long-term financial goals.

5. Overlooking Regular Portfolio Reviews

The financial markets and your personal circumstances are always changing, and your investment strategy should evolve in response. If your financial advisor is not conducting regular reviews of your portfolio, this is a major oversight. These reviews are critical to adapting to market changes, rebalancing the portfolio to maintain the original asset allocation, and making adjustments based on life changes such as marriage, having children, or retirement. An advisor who neglects these reviews is potentially jeopardizing your investments and hindering your ability to reach your financial goals.

6. Unexplained Fees or Costs

Transparency about fees is crucial in any financial advisory relationship. Your advisor should clearly explain all charges associated with your investments, including how they are compensated. Unexpected fees or costs that appear on your statements without proper explanation undermine trust and can indicate unethical behavior. Always ask for a detailed breakdown of fees and how they impact your investments’ overall performance. Understanding these fees and their justification is essential to evaluate the cost-effectiveness of the financial advice you are receiving.

7. Providing Generic Investment Advice

Receiving generic investment advice that could apply to anyone is not a service for which you should be paying a financial advisor. Your financial situation is unique, and the advice you receive should reflect your specific circumstances and goals. If it seems like your advisor is not putting effort into customizing their recommendations, it might be a sign that they are not fully engaged with managing your portfolio effectively. Advisors should spend adequate time understanding your financial situation, preferences, and future aspirations to provide tailored advice.

8. Not Being Proactive About Changes in Law or Policy

Financial advisors must stay informed about changes in tax laws, regulations, and economic conditions that can affect your investments. If your advisor is not proactive about adjusting strategies in response to these changes, it can have detrimental effects on your financial health. A good advisor anticipates shifts and advises you on necessary adjustments to safeguard your investments and capitalize on potential opportunities. Failure to do so can result in missed opportunities or unnecessary exposure to financial risks.

9. Ethical Lapses or Conflicts of Interest

Your advisor should always act with the highest ethical standards and in your best interest. Engaging in activities that benefit them at your expense, such as recommending financial products that provide them higher commissions but are not suited to your financial goals, is a serious breach of trust. Additionally, they must disclose any conflicts of interest that may affect their recommendations. An advisor’s commitment to ethics and transparency is fundamental to maintaining a successful advisory relationship.

10. Lack of Proper Credentials or Education

Ensuring that your financial advisor has the proper credentials and continues to update their education is crucial for competent financial management. Advisors should hold relevant certifications and regularly participate in ongoing professional development. This is necessary for them to stay current with financial trends and products. Lack of proper qualifications or failure to keep up with educational advancements can result in poor advice and mismanagement of your investments.

11. Misrepresenting Investment Products

Misrepresentation of investment products, whether about their risks, potential returns, or underlying costs, is unacceptable. Your advisor should provide a balanced view of all investments, including any risks associated with them. Transparency is key to your ability to make informed decisions. Any advisor who fails to provide full transparency should not be trusted with your financial portfolio.

12. Overtrading or Churning

Churning, or excessively trading securities, primarily to generate commissions, is unethical and detrimental to your financial interests. This practice can lead to significant transaction fees and tax consequences, eroding your investment returns. This activity does not align with a long-term investment strategy and should be watched carefully. Monitoring your account statements for unusual activity can help you spot and address churning if it occurs.

13. Not Planning for Your Financial Future

A competent advisor looks beyond immediate needs to consider your long-term financial objectives. This includes assisting with retirement planning, estate considerations, and insurance requirements. Neglecting to plan for these important aspects of your financial life can jeopardize your future security. Your advisor should help you develop a comprehensive plan that accounts for the various financial milestones throughout your life.

Ensuring Trustworthy Guidance

Your financial advisor plays a crucial role in shaping your financial future. Being aware of these 13 potential mistakes can help you monitor your advisor’s performance and ensure that your financial strategy remains on track. With awareness, any problems that arise can be dealt with before they become larger issues. Remember, a good advisor is transparent, communicates effectively, and is committed to your best interests.

[Read more…]

Toi Williams
Toi Williams

Toi Williams began her writing career in 2003 as a copywriter and editor and has authored hundreds of articles on numerous topics for a wide variety of companies. During her professional experience in the fields of Finance, Real Estate, and Law, she has obtained a broad understanding of these industries and brings this knowledge to her work as a writer.

Filed Under: Money and Finances Tagged With: Finances, financial planning, Personal Finances

Here are 8 Documents You Should Have in Place for Your Newborn Should You Die

May 10, 2024 | Leave a Comment

123rf

Planning for the future of your newborn in the event of your untimely demise is a daunting but necessary task. Ensuring that you have the right documents in place can provide security and clear directions for the care and support of your child. Here’s a list of essential documents you should prepare.

1. Will

123rf

A will is paramount as it outlines your desires for the distribution of your assets and the guardianship of your child. You can specify who you wish to care for your newborn and how you want your assets to be managed. This document helps prevent legal battles among relatives and ensures your wishes are honored. Without a will, the state decides who cares for your child, which might not align with your preferences. It’s advisable to consult with a lawyer to ensure the will is legally binding and comprehensive. Updating your will as circumstances change is also crucial.

2. Trust

123rf

Setting up a trust can be an effective way to manage the assets you leave for your newborn. A trust allows you to set conditions on how and when your assets are distributed. This is especially useful for ensuring financial stability and care for your child over the years. You can appoint a trustee who will manage the assets and use them according to your instructions. Trusts can also help minimize estate taxes and can be structured to avoid probate. Reviewing the trust periodically with your attorney ensures it meets your evolving family needs.

3. Guardianship Documentation

123rf

Documenting your choice of guardian is crucial if the worst were to happen. This document should be detailed, reflecting your choice of who will raise your child in your absence. Discuss this decision with the potential guardian to ensure they are willing and able to take on the responsibility. Legal documentation of guardianship helps avoid custody issues with the state or family members. It’s wise to name an alternate guardian as well, in case your first choice is unable to serve. Keeping this document updated and in sync with your will is necessary.

4. Life Insurance Policy

123rf

A life insurance policy ensures that there is financial support available for your child’s upbringing and education. Choosing the right policy involves assessing the future needs of your child and the expected costs of upbringing. The beneficiary of the policy should be a trust or a guardian you trust to use the money for the benefit of your child. Review and adjust your policy as your financial situation or family structure changes. It’s also a good idea to discuss the details of this policy with the guardian of your child. Keeping the policy information accessible and in a safe place is important.

5. Letter of Instruction

123rf

A letter of instruction is a non-legal document that provides additional details about your wishes. It can include instructions on child rearing, your values and the type of education you wish for your child. This letter can guide the guardian in making decisions in line with your parenting philosophy. It can also include practical information like account passwords and the location of important documents. Although not legally binding, it serves as a helpful guide for guardians. Regular updates to this letter ensure it remains relevant.

6. Medical Directive

123rf

A medical directive is important for making healthcare decisions if you become incapacitated before passing away. This document can also include decisions about your newborn’s health care preferences and any important health information. Ensuring that the guardian has access to this directive is crucial for the immediate care of your child. It can specify treatments you approve of and those you do not. A pediatrician can help you draft a comprehensive health care directive. Keeping this document with other vital records ensures it is easily accessible when needed.

7. Emergency Contact List

123rf

An emergency contact list is essential for the immediate aftermath of an unexpected event. It should include contact information for all individuals and entities related to your child’s care, such as relatives, potential guardians, doctors, and your attorney. This list aids the temporary caretaker in contacting the right people without delay. Make sure it is updated regularly and stored with your other important documents. Copies should be given to trusted family members or friends. This document ensures your child is never left in a care vacuum.

8. Power of Attorney

123rf

A power of attorney can authorize someone to manage your affairs if you’re unable to do so yourself. This can include financial decisions or everyday caregiving tasks for your newborn. It’s crucial to choose someone you trust implicitly for this role. The document should be specific about the powers granted and under what circumstances it can be enacted. It’s also sensible to have a backup person listed in this document. Reviewing this power of attorney periodically ensures it aligns with your current wishes.

Ensuring Your Legacy and Your Newborn’s Future

123rf

Preparing these eight essential documents ensures that your newborn’s future is secure, even in your absence. It’s a proactive approach that provides peace of mind, knowing that your child’s care and upbringing are arranged according to your wishes. Regularly reviewing and updating these documents with the help of legal and financial advisors is key to keeping your plan effective and relevant.

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.  As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy.

Filed Under: Money and Finances Tagged With: A Trust, A will, Documents, Letter of Instruction, Life Insurance Policy

Spending What You Don’t Have: 10 Ways Children Are Manipulating Their Parents to Overspend

May 6, 2024 | Leave a Comment

123rf

In the current consumer-driven era, children’s influence on family spending has never been more significant. From tech gadgets to trendy clothing brands, children are playing a major role in shaping their parents’ spending habits. This trend is often amplified by the pervasive reach of social media and peer influence, making it increasingly challenging for parents to say no. Here are ten common ways children are coaxing their parents into spending beyond their means.

1. The Brand Ambassador Effect

123rf

Children are becoming savvy brand ambassadors from a very young age. They often request specific, often expensive, brands to fit in with their peers or emulate their favorite influencers. Parents, wanting their children to feel accepted and happy, may give in to these demands, purchasing high-end products they wouldn’t normally buy. This creates a cycle where brand loyalty is built not just with the child but through the family’s spending habits.

2. The Tech Upgrade Request

123rf

Every new gadget release—be it the latest smartphone, tablet, or gaming console—comes with a fervent plea from children to upgrade. The fear of their child falling behind in technology-driven social and educational environments often leads parents to invest in expensive electronics, sometimes annually. These purchases, while seemingly essential, can significantly strain a family’s budget.

3. The Special Occasion Splurge

123rf

Birthdays, holidays, and other special occasions can become extravagant spending traps. Children may push for big-ticket items as gifts, and parents, driven by a desire to create memorable moments, may comply. This occasional splurge can quickly become a pattern, leading to overspending on every celebratory event.

4. Extracurricular Extremes

123rf

Extracurricular activities are essential for a child’s development but enrolling in too many programs or selecting high-cost options can be financially draining. Children may express a desire to join peers in arts, sports, or other activities, each carrying substantial costs for equipment, uniforms, and fees. Parents may feel pressured to provide these opportunities, often at the expense of their financial planning.

5. Peer Pressure Purchases

123rf

Children are heavily influenced by their friends and classmates, which can translate into pressure on parents to keep up with the collective spending habits of their child’s social circle. Whether it’s the latest fashion trends or the newest tech gadget, the pressure to conform can lead parents to make unplanned and costly purchases.

6. The Educational Investment

123rf

Education is arguably a necessary expense, but the way children and schools market certain opportunities can make parents stretch their wallets thin. From expensive private schooling to elite tutoring programs, parents can be manipulated into thinking that higher cost equals better education. This often results in overspending on educational products and services that may not necessarily guarantee superior outcomes.

7. Vacation Vanity

123rf

Vacations are another avenue where children might sway their parents’ spending. The desire to visit trending destinations seen on social media can prompt families to embark on costly trips. These vacations, while enjoyable, can lead to significant financial pressure, especially if they’re financed through debt.

8. The Charity Case

123rf

Children, often inspired by school activities or social media, can urge their parents to donate to various causes. While charitable giving is commendable, it needs to fit within a family’s budget. Parents might find themselves contributing more than they can afford simply to honor their child’s newfound philanthropic spirit.

9. Subscription Seduction

123rf

With the rise of digital entertainment, children are drawn to multiple streaming services and online platforms, each requiring a subscription fee. Parents might end up subscribing to several services to keep their children entertained and socially included, thereby inflating their monthly expenditures unnecessarily.

10. The Influencer Impact

123rf

Children who follow influencers might demand products or experiences promoted by these online personalities. This can lead to parents continually purchasing non-essential items that are effectively endorsed through their children’s preferred social media platforms, often without considering the long-term financial impact.

Finding a Balance

123rf

Navigating the complex world of family finances in a consumer-driven society requires a balance between fulfilling children’s desires and maintaining financial health. By recognizing the ways in which children might be unknowingly encouraging overspending, parents can set limits and educate their children about the value of money. Establishing clear financial boundaries and discussing the difference between wants and needs can help families avoid the pitfalls of consumer pressure and ensure a more sustainable financial future.

Latrice Perez

Latrice is a dedicated professional with a rich background in social work, complemented by an Associate Degree in the field. Her journey has been uniquely shaped by the rewarding experience of being a stay-at-home mom to her two children, aged 13 and 5. This role has not only been a testament to her commitment to family but has also provided her with invaluable life lessons and insights.  As a mother, Latrice has embraced the opportunity to educate her children on essential life skills, with a special focus on financial literacy.

Filed Under: Money and Finances Tagged With: Extracurricular Extremes, Peer Pressure Purchases, The Brand Ambassador Effect, The Special Occasion Splurge, The Tech Upgrade Request

« Previous Page
Next Page »
  • Facebook
  • Pinterest
  • RSS
  • Twitter
Best Parenting Blogs

Most Popular

Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Baby

9 Baby Names Inspired by Fall Without Naming Your Child Autumn

Evan Morgan
Baby

9 Baby Names That Sound Expensive Even Though Naming Your Baby Is Still Free

Evan Morgan
Baby names

Teachers Admit: These 6 Baby Names Create Instant Bias in the Classroom

Latrice Perez
6 Baby Names That Sound Cute Now but Cause Problems Later

6 Baby Names That Sound Cute Now but Cause Problems Later

Brandon Marcus

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette