• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

Your College Student Calls and Says They’re Out of Money: Now What?

August 31, 2026 | Leave a Comment

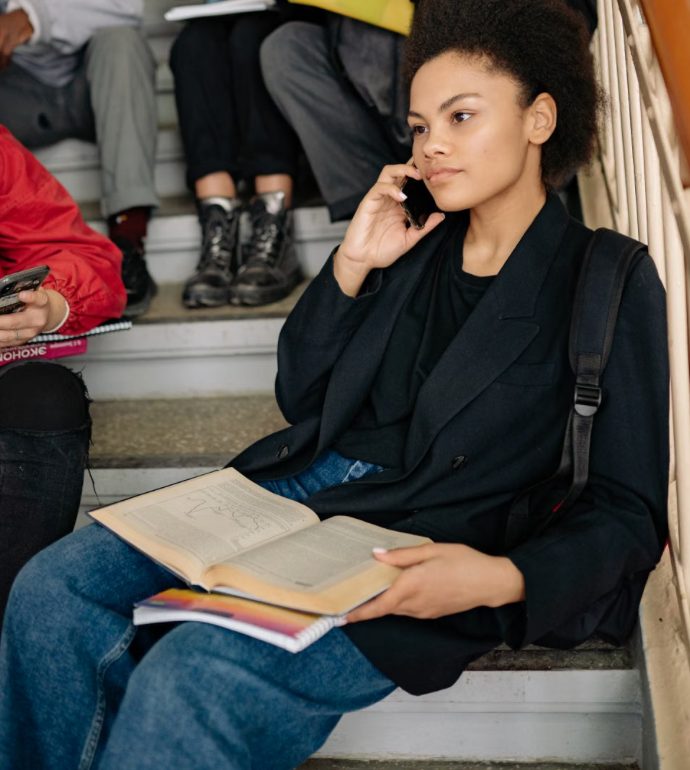
College Student On Phone
A college student reviewing expenses on a laptop can quickly discover how groceries, transportation, housing, and everyday purchases strain a semester budget. Parents can help by addressing immediate needs while creating a realistic plan for the months ahead. (Pexels).

The phone call can make any parent’s stomach drop: your college student is out of money, rent is approaching, and their bank balance is nearly zero. Your first instinct may be to open a payment app and transfer enough cash to make the problem disappear. Sometimes that’s exactly what needs to happen, particularly when food, housing, medication or another genuine necessity is at risk. But “I’m out of money” can describe everything from an unexpected $700 car repair to three months of spending $200 more than planned every week. Before deciding how much to send, figure out whether you’re dealing with an emergency, a budget problem or both.

First, Find Out What “Out of Money” Actually Means

Start with a question more specific than “What happened?” and ask your student exactly how much money they have, what bills are due before their next income arrives and what expenses they can’t currently cover. Someone with $18 left and no groceries has a different problem from a student who paid all of the month’s necessities but has nothing available for restaurants and entertainment. Ask them to pull up checking, credit-card and payment-app transactions so you’re working with actual numbers rather than memory. The goal isn’t to conduct a parental audit or shame them for every $9 coffee; it’s to identify whether the shortfall came from a one-time event or a pattern. You can’t fix the right problem until you know which one you’re dealing with.

College Students Running Out of Money Isn’t Unusual

A depleted bank account doesn’t automatically mean your student has been wildly irresponsible. The Hope Center for Student Basic Needs reported in July 2026 that 65% of students in the Trellis Student Financial Wellness Survey said they’d run out of money at least once since the start of the year. Even more concerning, 54% said they couldn’t readily access $500 in cash or credit during an emergency. The same research found 42% had experienced food insecurity during the previous 30 days and 35% experienced housing insecurity during the prior year. Those numbers don’t excuse uncontrolled spending, but they do show why parents should investigate the problem before assuming that an empty account means a student simply needs to “budget better.”

Decide Whether You Need to Send Money Today

Once you know what happened, separate urgent needs from problems that can wait. Food, necessary medication, housing, utilities and transportation required to get to class or work generally deserve attention before entertainment, shopping, restaurant meals or spring-break plans. If your student needs $150 to buy groceries and fill the gas tank until Friday’s paycheck arrives, that may call for a very different response than discovering they’re $1,200 short on rent because discretionary spending repeatedly exceeded the budget. You can address an immediate essential expense without simultaneously promising to refill the entire account. Sometimes the best first response is, “I’ll make sure you can eat and get to class this week, and tonight we’re going to figure out what happened.”

Look for the Difference Between a Shock and a Leak

One of the most useful questions is whether the student would still be out of money if one unusual expense hadn’t occurred. Suppose your daughter budgeted reasonably all semester but needed $800 for an emergency car repair after her transmission failed; that’s primarily a financial shock. Now imagine she came up $800 short after spending an average of $100 more than budgeted every week for eight weeks; that’s a recurring leak. The first situation may require emergency assistance and a plan for rebuilding savings, while the second requires changing ongoing spending before another transfer will accomplish much. Looking at the previous 30 to 60 days of transactions can usually reveal which situation you’re dealing with.

Check the Credit Cards Before Sending a Bailout

A nearly empty checking account may not show the entire financial problem. Ask whether your student has been putting groceries, gas or other expenses on a credit card and whether they’re carrying a balance. The Hope Center reported that 55% of surveyed students used a credit card during the year, and among those students, 88% said they’d used their cards to pay for basic needs. Among credit-card users attending two-year colleges, 47% carried a balance from month to month. If your student has $40 in checking but has quietly accumulated $2,500 on a credit card, sending $500 without discussing the debt may only address the most visible part of the problem.

Ask the College What Help Is Available

Parents shouldn’t automatically assume that the only possible emergency fund is their own savings account. Colleges may have emergency grants, food pantries, basic-needs centers, transportation assistance, payment plans or other resources, although what’s available varies considerably by institution. The Hope Center reports that more than two-thirds of enrolled students in nationally representative federal data didn’t know whether their institution offered emergency aid, even as student financial hardship remained widespread. Students whose family finances have changed significantly may also want to contact the financial aid office about whether an aid adjustment is possible. Federal Student Aid says schools can consider a professional-judgment adjustment for certain special financial circumstances, such as a loss of employment, pay cut or substantial uninsured medical expenses.

Don’t Underestimate What College Actually Costs Beyond Tuition

Sometimes the original budget failed because the family planned carefully for tuition but underestimated everything required to live through the academic year. The College Board’s 2025 Trends in College Pricing report estimated the average 2025–26 student budget for an in-state student at a public four-year college at $30,990. Only $11,950 of that amount represented published tuition and fees; the budget also included $13,900 for housing and food, $1,330 for books and supplies, $2,430 for transportation and $1,380 for other expenses. Those are national averages rather than a prediction of what your child should spend, but they demonstrate how easily families can focus on the tuition bill while underestimating transportation, food and ordinary living expenses. If the budget was unrealistic from the beginning, telling a student to “stick to it” won’t solve the underlying math.

College Families Are Spending More Than They Did a Year Ago

The financial pressure isn’t imaginary. Sallie’s 2026 How America Pays for College study found that families reported spending an average of $34,019 on college during the 2025–26 academic year, up 10% from $30,837 the previous year. Parent income and savings alone covered an average $13,087, or 39% of total college costs, while student income and savings covered another 10%. Nearly half of college families—47%—reported borrowing some money to pay for college. That doesn’t mean parents should automatically cover every student shortfall, but it provides useful context for why even families that planned ahead can discover that the actual cost of the year exceeded expectations.

Rebuild the Budget by Weeks Remaining, Not Months

Once the immediate crisis is under control, forget about what the budget was supposed to look like in August and build one around the money and time that remain. Add up dependable income the student expects to receive through the end of the semester, along with any family contribution or other resources that are genuinely available. Next, subtract unavoidable expenses such as rent, utilities, basic groceries, transportation, medications and necessary school costs. If $1,200 remains after essentials and there are eight weeks left in the semester, the student’s discretionary ceiling is about $150 per week. Giving the remaining money a weekly limit makes the situation much easier to manage than simply saying, “You have $1,200 left, so be careful.”

If You Send Money, Decide Whether It’s a Gift, Loan or Rescue

Ambiguity can create problems when parents help adult children financially. If you’re sending $600, decide whether you’re giving your student the money, expecting repayment or covering a specific emergency expense with no expectation that it will happen again. If it’s a loan, establish when repayment begins and what happens if the student can’t make the payment rather than vaguely saying, “Just pay me back whenever.” If it’s emergency help, you might pay the mechanic, landlord or utility directly instead of simply depositing another $1,000 into the student’s checking account. The purpose isn’t to control an adult child’s every dollar; it’s to make sure both sides understand what the financial assistance actually represents.

Don’t Automatically Replace Every Dollar They Overspent

Parents don’t have to choose between abandoning their student and restoring their bank balance to where it would have been if the mistake never happened. Suppose your son overspent by $900 but needs $300 immediately for groceries and transportation through his next paycheck. You might cover the $300 in necessities while requiring him to absorb the remaining consequences through reduced discretionary spending, additional work hours if practical or another adjustment. That preserves the lesson that spending decisions have consequences without allowing those consequences to threaten food, housing or academic progress. An unlimited bailout can teach a student that running out of money triggers a transfer; a targeted rescue can teach them how to recover.

Make a Plan for the Next Financial Phone Call Now

Before ending the conversation, decide what happens if the student starts running low again. You might agree that they should call when their balance reaches $300 rather than waiting until it reaches $3, or schedule a 15-minute budget check every two weeks for the rest of the semester. Another option is helping them build a small emergency buffer—perhaps $500 initially—that isn’t supposed to pay for restaurants, entertainment or routine shopping. The goal is to move the conversation earlier, when there are still several possible solutions, instead of waiting until rent is due tomorrow. Financial independence isn’t never needing help; part of it is learning to recognize trouble early enough to respond before it becomes a crisis.

The Goal Isn’t Just Getting Them Through Friday

When your college student says they’re broke, sending money may be necessary—but it shouldn’t automatically be the end of the conversation. First determine whether essentials are at risk, then identify whether the shortfall came from an unexpected shock, an unrealistic original budget or recurring overspending. Check for hidden credit-card debt, investigate campus assistance and rebuild the remaining semester around the money that’s actually available now. If you provide financial help, define exactly what you’re covering and what needs to change before another bailout occurs. Getting them through this week’s crisis matters, but teaching them how to avoid making the same desperate phone call next month may be the more valuable form of help.

If your college student called today and said their bank account was empty, would you send money immediately or ask to see what happened first? Share how you’d handle it in the comments.

What to Read Next

Should Parents Pay for College If Their Child Isn’t Taking It Seriously?

Parents Can’t Borrow Unlimited Amounts for College Anymore — What Families Need to Know

Your Kid Wants to Drop Out of College — What Happens to the Money You Already Paid?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: budgeting, college costs, college expenses, college financial planning, college student budget, college students, emergency expenses, family finances, parents of college students, student money problems

Should Parents Pay for College If Their Child Isn’t Taking It Seriously?

August 30, 2026 | Leave a Comment

Group of young adults toasting with red cups at a house party
With families spending an average of $34,019 on college in 2025–26, parents have good reason to expect students to take their education seriously. Clear expectations can help families balance financial support with student responsibility. (Pexels).

Paying for college can be one of the biggest financial commitments parents make for an adult child, so watching that child skip classes or ignore assignments can be especially frustrating. The stakes are higher than ever: families reported spending an average of $34,019 on college during the 2025–26 academic year, according to Sallie’s latest national study. That kind of money can represent years of savings, current income, or debt that follows a family long after graduation. Still, immediately cutting off support may create more problems than it solves. Parents may get better results by figuring out why their student is struggling and attaching reasonable expectations to continued financial help.

Paying For College Should Come With Expectations

Parents who are paying for college have every right to expect their child to make a genuine effort, even if straight A’s are not realistic. Expectations might include attending classes, completing assignments, maintaining an agreed-upon GPA, and meeting regularly with an academic adviser when problems arise. The goal should not be to control every grade but to establish that financial support comes with responsibility. For example, a parent covering $15,000 annually might reasonably require a student to remain in good academic standing and communicate honestly about setbacks. Putting those expectations in writing before the semester begins can prevent emotional arguments later.

Define What “Not Taking It Seriously” Actually Means

A disappointing grade is not automatically evidence that a student is wasting a parent’s money. College students can struggle academically because they chose the wrong major, underestimated the workload, work too many hours, or are having difficulty adjusting to independent living. Parents should look for patterns such as repeatedly skipping classes, refusing academic help, dropping courses without discussion, or prioritizing social activities over basic responsibilities. A student earning a C in a difficult chemistry course despite attending tutoring is in a very different situation from someone regularly missing the course altogether. Before changing plans for paying for college, parents need to distinguish between genuine struggle and persistent lack of effort.

Understand How Poor Progress Can Affect Financial Aid

Academic problems can eventually create consequences beyond a tense conversation at home. Students generally must meet their college’s satisfactory academic progress standards to remain eligible for federal financial aid, with schools typically considering GPA, completed credits, and progress toward a degree. NerdWallet notes that students commonly need at least a C average and must remain on pace to finish within 150% of their program’s expected length, although individual school policies vary. Losing aid could suddenly leave parents and students responsible for thousands of additional dollars. Families concerned about grades should therefore contact the college financial aid office early rather than waiting until financial assistance is suspended.

Consider The Cost Before Writing Another Check

The numbers make a casual approach to college difficult to justify. College Board reports that average published tuition and fees for 2025–26 are $11,950 for in-state students at public four-year colleges and $45,000 at private nonprofit four-year institutions, before grants and scholarships are considered. Sallie’s 2026 research also found that 47% of college families borrowed money to cover education costs. Parents who are borrowing, postponing retirement contributions, or draining emergency savings should be particularly cautious about financing semesters with little academic progress. Paying for college should fit into the family’s broader financial health rather than become an unlimited commitment regardless of results.

A Financial Reset Can Be Better Than Cutting Off Support

Parents do not have to choose between paying every bill and providing nothing. One compromise is requiring the student to contribute through summer earnings, part-time work, scholarships, or responsibility for books and personal expenses. Another option could involve paying for a less expensive community college while the student rebuilds academic habits before returning to a four-year school. National Student Clearinghouse data shows that 29.8% of students who began college in fall 2019 were no longer enrolled six years later, illustrating that completing college is far from automatic. A temporary change in the arrangement for paying for college can create accountability without permanently closing the door on education.

The Goal Is Progress, Not A Blank Check

Parents can support their children without agreeing to finance college indefinitely under any circumstances. With families spending tens of thousands of dollars and many relying on borrowing, paying for college deserves the same thoughtful planning as any other major financial decision. A student who is struggling but actively seeking help deserves a different response from one repeatedly refusing to participate in their education. Clear expectations, regular conversations, and reasonable financial boundaries can protect both the family’s money and the student’s opportunity to mature.

If your child stopped taking college seriously, would you keep paying, change the financial arrangement, or stop paying altogether—and why? Share your perspective in the comments.

What to Read Next

Your Kid Wants to Drop Out of College — What Happens to the Money You Already Paid?

Free College-Prep Services Eligible Teenagers Can Get Through TRIO

College Child Care Resources Student Parents May Not Know Exist

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: college costs, college students, college tuition, family finances, financial aid, parents and college, paying for college, student responsibility

Helping Your College Student Adjust to Life Away from Home

March 11, 2014 | Leave a Comment

College StudentsJust because your children don’t wear diapers anymore doesn’t mean you won’t stop thinking of them as “your babies.” This is why, for many parents, the experience of having their teenage kids move out of the house and into the dorms can be a source of anxiety. After all, you won’t be there to make sure they have access to nutritious foods, get plenty of rest and stay away from those “bad influences” every parent fears.

For easy transition, we’ve put together a shortlist of ways parents can use to assist the students adjust to college life away from the nest.

Send a Little Love & Care

Being a short drive away from your student’s campus is a luxury not all parents have. Luckily, sending a little slice of home is an easy way to remind your child that you’re thinking of them. Homemade baked-goods, clothes, knick-knacks or homely keepsakes are all great options to include in your student’s care package. If you’re not a master baker or maybe bogged down with work, have no fear! Companies that sell dorm stuff, like OCM, can send your student care package—and you can even include a handwritten note.

Set a Skype Date

Keeping an open line of communication is pivotal with college students. Text messages are good for short messages, but an even better option would be video chatting through Skype. This way, you not only get the chance to have in-depth conversations better than texts, emails, or regular phone calls.

Fund School Activities

Campus-based school activities is a great way for students to blow off steam, get their mind off of classes for a few hours, and meet new friends. Encouraging your student to find an activity and financially support their choice is an ideal way to make sure they are taking steps to settling into their new life. This will provide them with a sense of closeness and community right off the bat, something that is especially valuable when attending a school that has thousands upon thousands of students.

Plan Visits

Physically checking up on your children and spending time with them is an even better way to help them adapt to their life as a college student. While everyone likes surprises, surprise visits won’t always be met with the enthusiasm you may have been expecting. It’s in everyone’s best interest to make sure the visits are planned at least a week in advance. This way, your budding adults will have time to prioritize their school work and weekend activities (maybe even clean up their dorm room if you’re lucky).

Students may feel homesick, especially if it is the first time they have been away from home. Giving the students their freedom and letting them feel that they are trusted in making the right decisions is the best approach to take.

Photo Credit: Stuart Miles

How did you help your college aged kids adjust to life away from home?

Brian
Brian

Brian is the founder of Kids Ain’t Cheap and is now sharing his journey through parenthood.

 
Email • Google + • Facebook • Twitter

Filed Under: Growing Up Tagged With: college students, growing up, Kids

  • Facebook
  • Pinterest
  • RSS
  • Twitter

Basic Principles Of Good Parenting

Here some basic principles for good parenting:

  1. What You Do Matters: Your kids are watching you. So, be purposeful about what you want to accomplish.
  2. You Can’t be Too Loving: Don’t replace love with material possessions, lowered expectations or leniency.
  3. Be Involved Your Kids Life: Arrange your priorities to focus on what your kid’s needs. Be there mentally and physically.
  4. Adapt Your Parenting: Children grow quickly, so keep pace with your child’s development.
  5. Establish and Set Rules: The rules you set for children will establish the rules they set for themselves later.  Avoid harsh discipline and be consistent.
  6. Explain Your Decisions: What is obvious to you may not be evident to your child. They don’t have the experience you do.
  7. Be Respectful To Your Child: How you treat your child is how they will treat others.  Be polite, respectful and make an effort to pay attention.
Best Parenting Blogs

Most Popular

Baby Girl

12 “Grandma” Baby Names That Are Suddenly Cool Again

Evan Morgan
Baby

9 Baby Names That Sound Rare Without Being Hard to Spell

Evan Morgan
Target Store

Choking Incident Prompts Recall of 49,000 Target Gigglescape “Under the Sea” Popping Toys

Evan Morgan
Frustrated Girl

Why Some Students on the Spectrum Are Labeled With ODD

Evan Morgan
Coke Bottles

12 Things Kids Took to School in the ’70s That Would Never Be Allowed Today

Evan Morgan

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette