• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

Giving a Teen a Debit Card? Set These Rules Before the First Swipe

September 27, 2026 | Leave a Comment

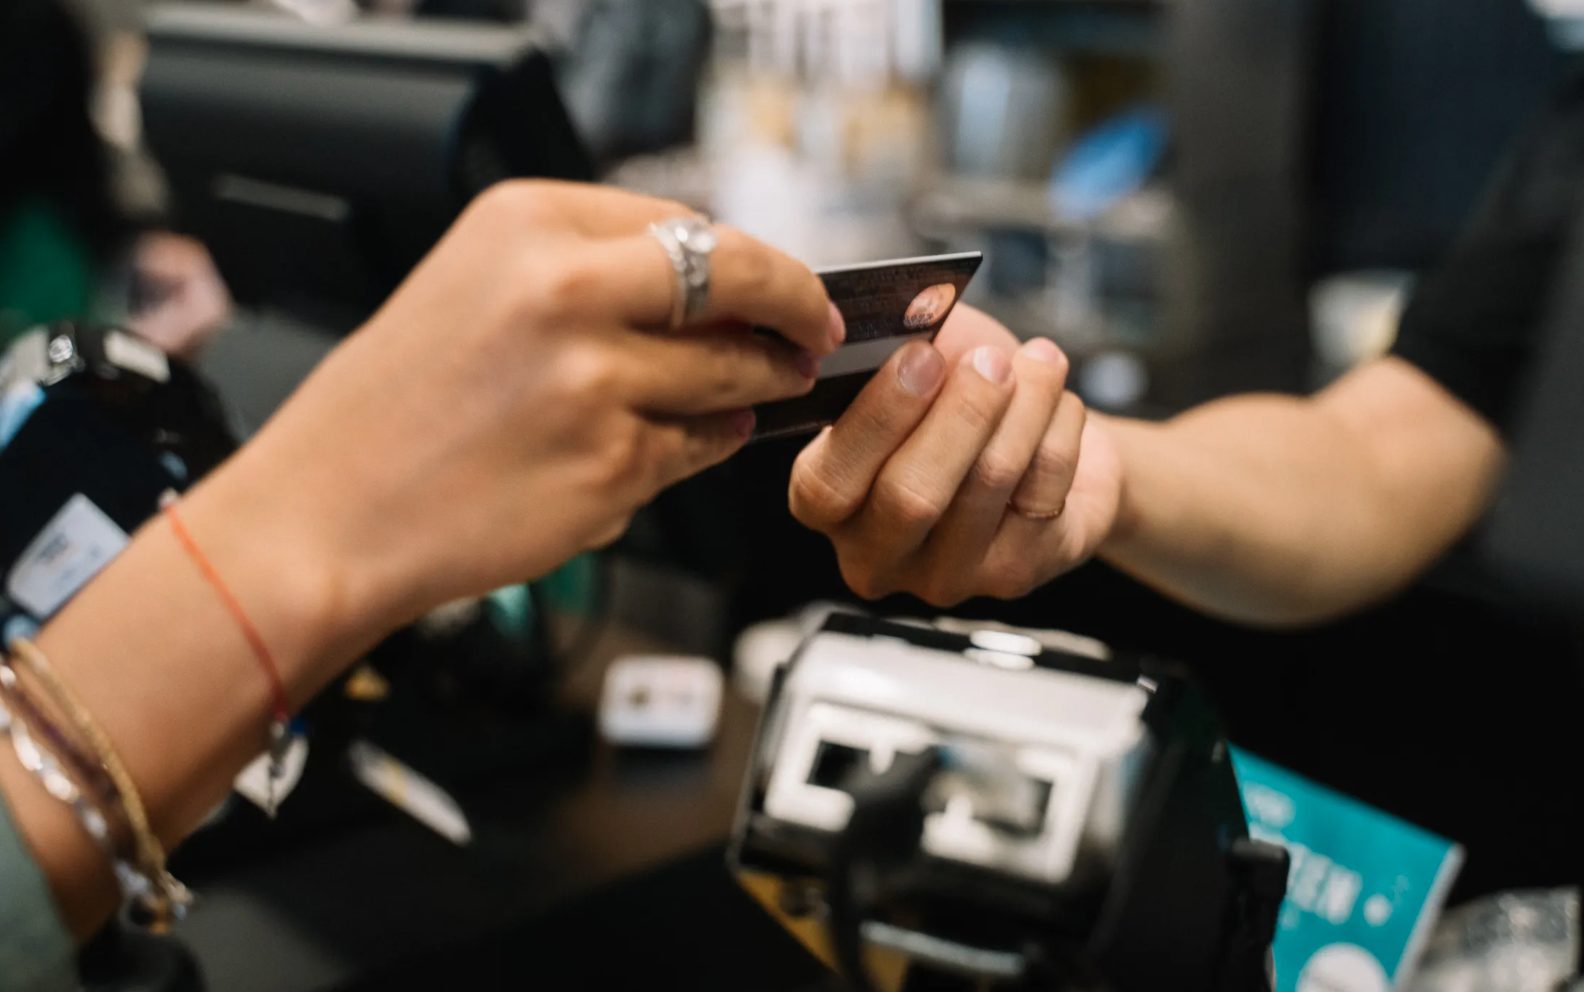
Customer paying with a debit card at a store checkout terminal
A teen debit card can provide valuable financial independence, but parents should establish spending limits, security rules, and savings expectations before the first purchase. Small mistakes today can become practical money lessons before the financial stakes get much higher. (Pexels).

Handing your teenager a debit card can feel like a small step, but it changes how quickly money can disappear. A teen debit card gives young people independence while giving parents an opportunity to teach budgeting, fraud awareness, and responsible spending before larger financial decisions arrive. Those lessons matter in an increasingly cash-light world, where tapping a phone or card can make a $20 purchase feel less tangible than handing over a $20 bill. Before activating the card, families should agree on rules that make everyday purchases teachable rather than stressful.

Decide What The Card Can Actually Pay For

Start by defining which expenses your teen owns and which remain the parents’ responsibility. Lunch with friends, gaming purchases, gas, clothing, and school expenses can quickly blur together unless everyone understands the boundaries. A practical rule might be that parents cover necessary school supplies while entertainment and restaurant purchases come from the teen’s personal balance. That distinction matters because Greenlight’s 2025 Family Trends Report found that 92% of surveyed kids said they regretted impulse purchases, showing that buyer’s remorse can become a useful financial lesson. A teen debit card works best when running out of spending money has a predictable consequence rather than automatically triggering a parental bailout.

Create A Spending Limit Before Money Hits The Account

Giving a teenager access to $300 does not necessarily mean allowing $300 of discretionary spending. Consider dividing incoming money among spending, short-term savings, and a longer-term goal, with percentages adjusted to your family’s circumstances. For example, a teen earning $200 from a weekend job might put $50 toward a car fund, $30 into emergency savings, and have $120 available for current spending. Schwab’s 2026 Teen Investing Survey found that 65% of parents and 50% of teens ranked money management or financial education among the three most important subjects to learn in school. A teen debit card can turn that education into real practice because each purchase forces a choice between spending today and keeping money for tomorrow.

Make Balance Checks Part Of The Routine

One of the easiest mistakes is assuming the number shown in an account always represents money available for guilt-free spending. Pending restaurant tips, subscriptions, and other transactions can complicate the picture, so teens should learn to review recent activity rather than rely solely on memory. NerdWallet recommends looking for teen accounts with reasonable spending controls and notes that some accounts let parents restrict ATM withdrawals, transfers, or debit-card spending. Consider requiring a quick balance check before purchases above an agreed amount, such as $25 or $50. That simple habit can make a teen debit card a budgeting tool instead of merely a more convenient way to spend.

Know What Happens When The Balance Hits Zero

Parents should understand an account’s overdraft rules before their teenager learns about them through an unpleasant surprise. Some institutions decline debit purchases when there is insufficient money, while account structures and overdraft options vary, making the fine print worth reading. Parents should ask whether the account can become overdrawn, whether another account is linked as backup, and whether any fees can be charged. Also check monthly charges and ATM costs because seemingly small recurring fees can eat into a teenager’s limited balance; Fidelity, for example, currently advertises its Youth Account for ages 13–17 with no subscription fees, account fees, or opening minimum. A declined $12 purchase can be a far cheaper lesson than repeatedly covering overspending without discussing what happened.

Establish Security Rules Before The Card Goes Missing

Teenagers need to know immediately what to do if their card disappears or an unfamiliar charge appears. Set a rule that a missing card gets reported to a parent and locked through the banking app as soon as possible, rather than waiting several days hoping it turns up. Teach teens never to share a PIN, send card information through messages, or approve unexpected requests for account credentials or verification codes. Parents should also activate transaction and low-balance alerts when available so suspicious purchases or rapid spending are easier to spot. Experian notes that most debit-card activity is not reported to the major credit bureaus, so parents should also explain that responsible use builds money-management skills but generally does not build a teen’s credit history.

The Bigger Goal Is Independence, Not Perfect Spending

A teen debit card should provide enough freedom for a teenager to make decisions, including an occasional inexpensive mistake, without putting significant family money at risk. Greenlight reported that its young users transferred $66 million among kids and friends in 2025, illustrating how routine digital money movement has become for many young consumers using its platform. Parents can use monthly account reviews to discuss unexpected purchases, subscriptions, savings progress, and what the teen would do differently next month rather than scrutinizing every snack purchase. The goal is not to raise a teenager who never wastes $15; it is to raise a young adult who understands why that $15 mattered and can make a better choice next time.

What debit-card rule would you insist on before giving your teenager financial freedom, and which mistakes should teens be allowed to learn from themselves? Share your thoughts in the comments.

What to Read Next

Your Teen’s First Job Could Change More Than Their Spending Money

Your Teen Works 15 Hours a Week: What Expenses Should Become Their Responsibility?

6 Money Rules Every Family Should Set Before a Teen Starts Driving

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: budgeting for teens, debit cards, family finances, Financial Education, financial literacy, money management, parenting teens, Saving Money, teen debit card, teens and money

The Babysitter Wants $25 an Hour: Is That Really the Going Rate Now?

September 27, 2026 | Leave a Comment

Little girl whispering in a smiling teen babysitter's ear on a couch
Babysitting rates in 2026 commonly reach the $20-to-$30-an-hour range, depending on location, experience and responsibilities. At $25 an hour, even a four-hour date night means $100 in childcare before parents spend anything else. (Pexels).

A few years ago, paying a babysitter $15 or $18 an hour might have seemed perfectly reasonable, but many parents are now hearing a much bigger number: $25. That can turn an ordinary date night into a surprisingly expensive outing before dinner, tickets, or transportation enter the picture. Yet current babysitter rate data shows that $25 an hour is no longer unusual, particularly in expensive metropolitan areas or when a sitter has substantial experience. The confusing part is that national averages vary significantly depending on which childcare marketplace you check and how its data is collected. Before deciding that $25 is excessive—or automatically agreeing to it—parents should understand what they are actually paying for.

$25 An Hour Is Becoming Less Unusual

Current babysitter rate figures show just how much the market can vary: Sittercity reported a national typical rate of $23 an hour in May 2026, while UrbanSitter put its national average at $26.24 for one child based on booking data. Meanwhile, Care.com data cited a national average starting cost of $20.61 an hour as of September 2026, illustrating why parents should not treat any single national figure as the universal going rate. The differences largely reflect methodology: some numbers come from caregiver listings, others from family job postings or completed bookings. Geography matters just as much, with Sittercity reporting 2026 babysitting rates of $30.50 in San Francisco, $28 in Seattle, $25 in Austin and $21 in San Antonio. In other words, a $25 babysitter rate can be above average in one community and completely ordinary in another.

What Parents Are Actually Paying For

The hourly babysitter rate is not determined only by the number of hours someone spends inside your house, because the difficulty and responsibilities of the job matter. A caregiver watching one self-sufficient 10-year-old for three hours has a very different assignment from someone feeding an infant, changing diapers and putting a toddler to bed while supervising an older sibling. Care.com notes that location, experience, children’s ages, number of children and responsibilities can all influence what a sitter charges. CPR and first-aid training, experience with infants or children requiring specialized care, driving duties, meal preparation and late-night availability may also justify higher compensation. Parents comparing babysitter rates should therefore compare similar jobs rather than assuming that a neighbor paying less is buying exactly the same service.

The Four-Hour Date Night Adds Up Fast

Suppose a couple hires a sitter from 6 p.m. until 10 p.m. at a babysitter rate of $25 an hour, making the childcare bill $100 before they leave home. Add a $90 dinner, $30 for movie tickets and $20 for parking or transportation, and their four-hour night out has suddenly reached $240. Extend the evening until midnight and babysitting alone becomes $150, pushing the same outing to $290. That math helps explain why childcare expenses are changing how families socialize, and Care.com’s 2026 Cost of Care Report found that 34% of surveyed parents reduced entertainment or leisure spending because of care costs. One practical response is to compare several local sitters, shorten outings, swap childcare with trusted friends or relatives, or schedule activities when family help is available rather than simply abandoning nights out altogether.

Ask These Questions Before Agreeing To The Rate

Rather than asking only whether $25 sounds expensive, parents can ask a sitter what the babysitter rate includes and whether extra children, transportation, meals, late hours or holidays cost more. Ask about childcare experience, references, CPR or first-aid training, comfort with your children’s ages, emergency procedures and whether the sitter expects reimbursement for mileage or other expenses. Parents should also establish whether they are paying for every minute worked, how cancellations are handled and what happens when they arrive home later than planned. Checking multiple local listings can provide a much more useful benchmark than relying on a national average, especially because 2026 marketplace estimates differ by several dollars per hour. Saving money matters, but choosing solely on the lowest hourly price can be a false economy when reliability, safety, experience and the ability to handle an emergency are part of what families are purchasing.

The Real Question Is What Fair Childcare Costs In Your Area

A $25 babysitter rate is not automatically unreasonable in 2026, but neither is it automatically the correct price for every family, sitter or location. National figures currently span roughly the low-to-mid-$20s depending on the marketplace and methodology, while rates in individual cities can fall below $20 or climb past $30. Parents can make a better decision by checking local rates, defining responsibilities clearly and calculating the entire cost of an outing before making childcare a recurring expense. The overlooked lesson is that frequency matters too: occasional babysitting can become thousands of dollars in annual household spending surprisingly quickly and may create additional tax considerations for regular arrangements.

Would you willingly pay $25 an hour for a reliable, experienced babysitter, or has the cost of childcare reached the point where you would simply stay home? Tell us what babysitters charge in your area in the comments.

What to Read Next

6 Babysitter Habits That Can Actually Cause Long-Term Damage

Should Parents Be Required to Disclose Their Kids’ Diagnoses to Babysitters?

Beyond The Babysitter: 10 Legal Papers You Need For Child Care Before An Emergency

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: babysitter rate, babysitter rates, babysitting, Childcare, childcare costs, Cost of Living, family finances, household budget, Parenting, Saving Money

Bought Kids’ Toys From SHEIN or Amazon? Check These New Recalls Before Playtime

September 26, 2026 | Leave a Comment

Amazon Prime delivery vans parked on a street
Several September 2026 toy recalls involve products sold through Amazon and SHEIN, including magnetic figures, busy boards and teething toys. Parents should check product names, SKUs and past online orders before letting children continue playing with potentially affected items. (Pexels).

A toy that looked harmless when it arrived on your doorstep may deserve another look before your child plays with it. Several new toy recalls announced in September involve products sold through SHEIN, Amazon and other retailers, with hazards ranging from detachable magnets to choking risks and expanding water beads. Some affected products were inexpensive impulse buys, while others were sold for years before being recalled. That makes checking old order histories just as important as inspecting something purchased last week. Parents should pay particular attention to the following toy recalls, especially if younger children or siblings have access to the products.

Amazon-Sold Magnetic Figures Led To Two Hospitalizations

One of the most serious recent toy recalls involves approximately 38,507 Jerify Magnetic Humanoid Toy Sets sold on Amazon from October 2022 through May 2026 for about $21. According to PEOPLE, two children removed and swallowed magnets from the figures, and both were hospitalized. The 30-piece sets contain colorful human-shaped figures with magnets in their hands and feet, and the recalled package carries the Jerify name and number X003ADA3TD. High-powered magnets are especially dangerous when more than one is swallowed because they can attract across intestinal tissue, potentially causing blockage, perforation or other life-threatening injuries. Families with this set should stop using it immediately and follow the recall instructions for obtaining a full refund rather than simply putting it on a higher shelf.

A Popular Amazon Busy Board Has A Choking Hazard

Another major Amazon-related recall covers about 276,000 Esjay Toddler Busy Board Montessori Toys, making it one of the largest of these recent toy recalls. The blue felt boards, sold from March 2023 through July 2026 for $18 to $30, have five pages, and red knobs on the second page can detach and become a choking hazard for children under 3, according to Total Preschool. The good news is that no injuries were reported when the September 17 recall was announced, and owners do not necessarily have to discard the entire board. Esjay instructs consumers to remove the affected page, mark it “RECALLED,” dispose of it and submit a photo to receive a replacement page. A parent who paid $30 for the board therefore should not automatically spend another $30 on a replacement toy before checking whether the free repair remedy applies.

SHEIN Teething And Spiral Toys Are Also Recalled

SHEIN shoppers have multiple toy recalls to check, including roughly 644 Pull & Chew Montessori Teething Toys recalled September 17 because their silicone strings can extend far enough into a child’s mouth to create a choking risk. The affected teethers were sold for about $10 from December 2025 through April 2026, and the recall is also documented by the nonprofit toy-safety organization W.A.T.C.H. Earlier in September, SHEIN recalled approximately 963 Spiral Toys sold for $6 to $16 because small yellow balls included with the toys violate requirements intended to protect children under 3 from choking. Neither SHEIN recall had reported injuries when announced, but the absence of reported injuries does not make continued use advisable. Parents should compare the product name, packaging and SKU with recall information rather than assuming a similar-looking toy is automatically included.

Small Decorative Magnets Deserve Attention Too

Not every child safety risk comes from something explicitly marketed as a toy, which is an important limitation parents should remember when checking toy recalls. On September 10, SHEIN recalled about 4,640 bear-shaped decorative refrigerator magnets sold between May 2025 and February 2026 for just $3 to $4 because the loose magnets can create an ingestion hazard. The colorful magnets were available in packages of 10, 20 or 30 and carry SKU sh2403211731230106, making that number more reliable than appearance alone when identifying them. The danger is easy to overlook because parents may place refrigerator decorations within reach without thinking of them as playthings, while young children may see the bear shapes differently. This is why families should include novelty items, decorations and older online purchases when conducting a quick safety sweep.

Squishy Toys With Water Beads Are Another Warning Sign

Parents should also inspect squishy toys containing water beads, particularly dumpling- or bun-shaped products that have become popular online. NBC Chicago reported on a September 17 recall of 276 green Rainbow Mystery Squishy Bun Toys because their internal water beads can expand beyond permitted limits and create ingestion, choking and intestinal-obstruction hazards. That followed September 3 recalls involving about 7,200 pink Rainbow Mystery Squishy Bun Toys and about 8,000 GIHNJSI Squeezy Dumplings, the latter sold on Amazon for roughly $20. As the Houston Chronicle reported, the two earlier recalls alone covered more than 15,000 squeeze toys containing water beads. If a squishy toy breaks or leaks, parents should keep its contents away from children rather than assuming the tiny beads are harmless stuffing.

Check The Order History Before The Toy Box

The bigger lesson from these toy recalls is that price, popularity and an online marketplace listing are not substitutes for checking current safety information. Search your Amazon and SHEIN purchase histories for product names, then compare model numbers, SKUs, packaging and purchase dates with the recall notice before throwing anything away. Follow the stated remedy carefully because some companies require a photo showing that a product or component was marked or destroyed before issuing a refund or replacement. It is also worth checking toys handed down by relatives, stored for younger siblings or purchased months ago, since several newly recalled products were sold long before September 2026.

Have you ever discovered that a toy in your home had been recalled months after you bought it, and do you regularly check your online purchase history for recalls? Share your experience and safety tips in the comments.

What to Read Next

Choking Incident Prompts Recall of 49,000 Target Gigglescape “Under the Sea” Popping Toys

CVS Medicated Wipes Recalled Over Child-Poisoning Risk

Online Safety Experts Urge Parents to Check These Apps Before Summer Begins

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Amazon recalls, Amazon toys, child safety, Parenting, product recalls, recalled toys, SHEIN recalls, SHEIN toys, toy recalls, toy safety

10 Baby Names With Meanings That Are Better Than the Names Themselves

September 25, 2026 | Leave a Comment

Smiling baby sitting inside a cardboard box
A baby’s name can carry a story that lasts a lifetime. These 10 choices have meanings tied to freedom, happiness, grace, good fortune, beauty, and new beginnings. (Pexels).

Choosing a baby name can feel like an impossible assignment: find something meaningful, pronounceable, distinctive, and unlikely to embarrass your child at age 30. Sometimes, however, the story behind a name is far more appealing than its actual sound. The latest U.S. naming data show how quickly tastes can shift, making baby name meanings another useful way to judge a choice beyond popularity. According to the Associated Press, Olivia and Liam remained America’s most popular names for babies born in 2025 for the seventh consecutive year, while Charlotte climbed to No. 2 for girls and Eliana entered the top 10. Here are 10 names whose meanings might win you over even when the names themselves do not.

1. Calliope — “Beautiful Voice”

Calliope looks elegant on paper, but many Americans may hesitate over its pronunciation. Its meaning, however, is difficult to dislike: “beautiful voice,” according to Behind the Name. In Greek mythology, Calliope was the Muse associated with epic poetry and eloquence. That gives the name an artistic history extending far beyond modern baby-naming trends. For parents researching baby name meanings, this one practically comes with its own origin story.

2. Evangeline — “Good News”

Evangeline is romantic and dramatic, but four syllables can feel like a lot for everyday life. Its meaning may change your mind because the name comes from Greek elements meaning “good” and “news” or “message.” Behind the Name’s Evangeline history also traces its literary use to Henry Wadsworth Longfellow’s 1847 poem. Parents could easily shorten it to Eva, Evie, or Lina. That flexibility makes its uplifting meaning surprisingly practical.

3. Saoirse — “Freedom”

Saoirse can stop unfamiliar readers in their tracks because its Irish spelling does not follow English pronunciation rules. Yet its meaning is beautifully simple: “freedom” in Irish Gaelic, according to Behind the Name. The site notes that it began being used as a given name in the 20th century. The tradeoff is that a child in the U.S. may spend years explaining the spelling and pronunciation. Still, among baby name meanings, “freedom” carries unusual strength.

4. Amara — “Grace”

Amara sounds modern, although its roots run much deeper. In Igbo usage, Amara means “grace,” making the meaning wonderfully concise. The important detail is that identical-looking names can develop independently in different languages, so parents should not assume every Amara has the same linguistic origin. That is a good reminder to investigate cultural context instead of trusting a random baby-name graphic online. A beautiful meaning deserves an accurate explanation.

5. Felix — “Lucky” Or “Successful”

Felix can still remind some people of the famous cartoon cat, which may be an immediate deal-breaker. Its Latin history is considerably more impressive, with the name meaning “lucky” or “successful,” according to Behind the Name’s Felix entry. It was used in ancient Rome and later by numerous early Christian saints. That gives Felix considerably more history than its pop-culture associations suggest. Imagine telling your son that his name essentially wishes him good fortune throughout life.

6. Zora — “Dawn”

Zora is short, punchy, and uncommon enough to surprise people. Its South Slavic meaning is “dawn” or “aurora,” creating imagery of light and new beginnings. That symbolism feels particularly appropriate for a newborn entering a family’s life. The name also has a major American literary association through writer Zora Neale Hurston. Parents considering it should weigh both the cultural history and the appealing meaning rather than simply chasing uniqueness.

7. Beatrix — “Voyager” With A Happy Twist

Beatrix has an unmistakably vintage sound that will not appeal to everyone. Its history is more complicated and interesting than many quick baby-name lists suggest. The name probably developed from Viatrix, connected with the Latin word for “voyager” or “traveler,” while its spelling was later influenced by Latin beatus, meaning “blessed” or “happy.” That combination gives Beatrix an adventurous and optimistic backstory. It is a great example of why researching baby name meanings beyond a one-word definition matters.

8. Asher — “Happy” Or “Blessed”

Asher has become familiar enough that it no longer sounds especially unusual. The Hebrew name means “happy” or “blessed,” giving parents an appealing sentiment without choosing an obvious virtue name. Its biblical roots also give it a long history rather than making it a recent invention. Parents should still consider whether the nickname Ash and the name’s religious associations fit their family. Meaning matters, but so does how a name will function every day.

9. Esmé — “Esteemed” Or “Loved”

Esmé sounds sophisticated, though the accent and pronunciation may create occasional confusion. Its Old French meaning is generally given as “esteemed” or “loved.” Few baby name meanings could deliver a warmer message from parent to child. It also demonstrates why spelling matters, since related forms and similar-looking names can have different histories. Before settling on an unusual spelling, check whether it changes the name’s documented origin.

10. Felicity — “Happiness”

Felicity sounds almost too cheerful to be real, yet that optimism is exactly the point. The English word ultimately traces to Latin felicitas, associated with happiness and good fortune. As a virtue-style name, it communicates its meaning more openly than most names on this list. Its four syllables may feel formal, but nicknames such as Flick or Lissy can make it more casual. If baby name meanings matter more than trendiness, “happiness” is a difficult message to beat.

A Great Meaning Still Has To Survive Real Life

The best baby name is not simply the one with the prettiest definition. Say the full name aloud, test possible initials, consider obvious nicknames, and imagine a teacher or employer encountering it without guidance. Current trends also show why popularity deserves consideration: 2025 brought Charlotte up to No. 2 for girls, Eliana into the top 10, and fast-rising boy name Kasai up 1,108 ranking positions. Meanings can add emotional weight, but pronunciation, cultural context, family significance, and everyday usability matter too.

Which of these names has a meaning strong enough to make you reconsider the name itself, and what surprisingly meaningful baby name would you add to the list? Share your pick in the comments.

What to Read Next

9 Baby Names That Sound Rare Without Being Hard to Spell

10 Baby Names That Almost Disappeared but Could Be Ready for a Comeback

9 Baby Names That Work Whether Your Child Becomes an Artist, Athlete, or Accountant

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: baby name meanings, baby names, meaningful baby names, Newborns, Parenting, popular baby names, Pregnancy, unique baby names

Would You Tell Your Child You Can Afford Something but Simply Don’t Want to Buy It?

September 25, 2026 | Leave a Comment

Mom And Daughter Shopping
Saying “we can afford it” does not mean every purchase fits the family’s priorities. Honest conversations about wants, savings, and tradeoffs can help children understand how real-world money decisions work. (Pexels).

Most parents have heard some version of, “But you have the money, so why can’t I have it?” Maybe it happens over a $12 toy, a $90 pair of sneakers, or the newest phone that costs hundreds of dollars more than a perfectly functional model. Saying “we can’t afford it” may end the conversation quickly, but what if that is not actually true? Telling a child, “We can afford it, but that isn’t how I want to spend our money,” can open a much more valuable conversation about priorities. In fact, teaching kids about money may sometimes require admitting that having enough cash and choosing to spend it are two very different things.

“We Can Afford It” Does Not Mean “We Should Buy It”

Affordability is not simply a question of whether enough money happens to be sitting in a checking account. A family with $5,000 available could technically buy a $1,000 phone, but that same $1,000 might be earmarked for an emergency fund, summer camp, debt repayment, or a future vacation. The American Psychological Association recommends being more direct with children instead of automatically saying something is unaffordable, suggesting language that explains the purchase is not how the family chooses to spend its money. That distinction is important when teaching kids about money because it introduces the idea of opportunity cost: spending on one thing means giving up another. Parents do not need to reveal their salary, bank balance, or every household expense to explain that money has competing jobs.

Parents Are Already Under Pressure To Spend

Saying no can be harder when children see friends receiving expensive clothes, electronics, trips, and other extras. A 2026 LendingTree survey found that 61% of parents with children under 18 felt pressure to overspend on their kids to keep up with other families, while 82% said raising children had become more expensive during the previous year. More than half, 55%, reported spending at least $1,000 a month on child-related expenses, and 64% said they had gone into debt at some point to cover child-related costs. Those numbers show why “yes” can carry a hidden cost even for parents who can cover a purchase today. Teaching kids about money includes showing them that another family’s spending habits are not a useful guide for deciding what belongs in your own budget.

A $250 Purchase Can Become A Real Money Lesson

Suppose your 13-year-old wants $250 sneakers and you could pay cash without missing a bill. Instead of simply buying them or claiming you cannot afford them, explain that your normal shoe budget is $100 and the additional $150 represents a choice, then offer alternatives such as saving allowance or gift money toward the difference. This approach gives children experience making tradeoffs while keeping the parent responsible for appropriate necessities. Research involving 1,247 teenagers, published in Young Consumers via ScienceDirect, found that parent-child financial discussions were an important influence on financial knowledge, attitudes, and behavior. Teaching kids about money works better when money becomes something families can discuss rather than a mysterious resource that is either “there” or “gone.”

Protecting Savings Is Also A Form Of Spending Discipline

Parents may feel guilty declining a nonessential purchase when they know there is money in savings, but savings are not necessarily spare cash. A Bankrate survey found that only 46% of U.S. adults had enough emergency savings to cover at least three months of expenses in 2025, while 24% had no emergency savings at all. That makes preserving savings for a broken transmission, medical expense, job loss, or home repair a legitimate financial priority rather than unnecessary stinginess. Parents can explain that money in an account may already have a purpose even when it has not been spent yet. A child who learns this distinction may begin understanding why a healthy bank balance is not permission to buy everything within reach.

Children Can Learn That Money Reflects Priorities

One overlooked benefit of saying “I don’t want to spend money on that” is that it allows parents to explain what they do value. The 2025 Charles Schwab Modern Wealth Survey found that Americans surveyed associated wealth with factors including health, relationships, experiences, accomplishments, and free time, not simply net worth and possessions. A family might therefore decide that $600 is better spent on a weekend experience together than another electronic device, while another family may make the opposite choice. Teaching kids about money does not mean convincing children that spending is bad; it means demonstrating that spending should match priorities. Asking “What would you be willing to give up for this?” can turn a request into a surprisingly useful budgeting exercise.

The Bigger Lesson Is Learning To Choose

Children eventually need to manage money without a parent standing beside them, which makes everyday purchasing decisions useful practice. Being truthful about the difference between “cannot afford” and “choose not to buy” teaches that financial security depends partly on the purchases people decline, not merely the income they earn. Parents can set clear limits, invite older children into age-appropriate budget conversations, and let them save toward selected wants rather than automatically supplying them. That approach makes teaching kids about money less about lectures and more about decisions children can see and experience.

Would you tell your child that you could afford something but simply decided it was not worth buying, or would you rather keep the family’s financial reasoning private? Share your approach in the comments.

What to Read Next

12 Reasons Why You Can’t Afford Summer Camp Anymore

7 “Cheap” Kids’ Activities That Can Become Surprisingly Expensive

Would You Let Your Child Add Whatever They Want to Your Online Shopping Cart?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: budgeting, children and money, family finances, financial literacy, Parenting, personal finance, Saving Money, teaching kids about money

9 Baby Names That Sound Rare Without Being Hard to Spell

September 24, 2026 | Leave a Comment

Laughing baby sitting on a bed with gray pillows
Rare baby names such as Maren, Alma, Stellan, Orla and Elowen offer parents something distinctive without resorting to complicated spelling. Checking current popularity trends can also reveal whether an uncommon favorite is starting to climb. (Pexels).

Choosing a baby name can turn into a balancing act: you want something memorable, but perhaps not something your child will have to spell three times at every appointment. That is where rare baby names with recognizable sounds and straightforward spellings can shine. Naming choices are remarkably broad; BabyNames.io reports that 17,248 names were given to fewer than 25 U.S. babies in 2025. At the same time, familiar classics continue to dominate the upper reaches of the charts, making less-common choices feel even more distinctive. These nine names offer individuality without requiring a complicated collection of letters.

1. Maren Feels Familiar Without Feeling Overused

Maren has the comfortable rhythm of Karen or Lauren while sounding noticeably fresher. According to Behind the Name, Maren is used in Danish and Norwegian and can be a diminutive of Marina or Maria. Current U.S. data places the name around the middle of the girls’ top 1,000, meaning it is established without being everywhere. Its five letters also make it refreshingly uncomplicated on forms, invitations, and school rosters. Parents considering Maren should simply decide which pronunciation they prefer, since regional variations exist.

2. Callan Offers An Alternative To Callum

Callan has the advantage of sounding recognizable even if you have never personally met one. The name reached No. 190 among U.S. boys in 2025, according to current data reported by Nameberry, making it increasingly familiar but far from a top-10 staple. Its six-letter spelling is intuitive, and the nickname Cal practically suggests itself. That makes Callan particularly practical for parents searching for rare baby names without venturing into elaborate spellings. The tradeoff is its rise in popularity, so parents wanting extreme rarity may prefer another option.

3. Alma Packs Plenty Into Four Letters

Alma is short, vintage and remarkably easy to put on a birth announcement. The Bump places Alma at No. 449 among U.S. girls for 2025, giving parents a concrete idea of how often they might encounter another one. The name also has a long history rather than being a newly invented spelling designed to look different. Four letters make it simple for a child learning to write a name and convenient for adults hearing it over the phone. If Ava and Emma appeal to you but feel too familiar, Alma occupies an interesting middle ground.

4. Stellan Has Scandinavian Style

Stellan sounds distinctive, but there is little mystery about how to write it once you hear it. The Swedish name ranked No. 1,140 among boys in 2025, with 186 recorded births, according to Nameberry. That puts Stellan outside the top 1,000 and makes it genuinely uncommon compared with many names marketed as unique. Parents should remember, however, that easy spelling does not automatically mean everyone will pronounce a name identically. Trying the name aloud with your surname is a smart test before putting Stellan on the final list

5. Livia Makes A Small Change With A Big Effect

Livia resembles Olivia closely enough to feel immediately familiar without simply being another spelling of it. That missing first letter makes the name shorter and gives it its own identity rather than relying on unusual punctuation or extra vowels. This approach highlights a useful strategy when researching rare baby names: look for established names adjacent to popular favorites rather than deliberately misspelling the favorite. You may occasionally have to clarify that the name is Livia rather than Olivia, which is the main practical drawback. Test it by saying, “Her name is Livia,” to see whether that correction would bother you over time.

6. Zora Is Short And Memorable

Zora manages to feel striking while requiring just four letters. Its simple construction is particularly useful when you consider how often a name eventually appears on medical forms, school paperwork, email addresses and job applications. The name’s uncommon status also provides individuality without depending on a complicated spelling to manufacture uniqueness. A short name is not automatically mistake-proof, of course, and someone could still mishear Zora as Nora. Even so, Zora demonstrates why some of the most effective rare baby names are also among the simplest.

7. Cassian Is A Name To Watch

Cassian combines an old-world sound with growing modern visibility. Mallowby reports that 633 U.S. boys were named Cassian in 2025, placing it at No. 479 and marking its highest position yet. That is important because an uncommon name chosen today may not remain equally uncommon throughout your child’s school years. Cassian is relatively straightforward to spell, although parents may encounter different pronunciations, including CASS-ee-an and CASH-an. If rarity is your priority, checking several years of popularity data is more useful than looking only at today’s ranking.

8. Orla Proves Rare Can Still Be Simple

Orla is an established Irish name that manages to pack considerable personality into four letters. Unlike names made unusual by creative spelling, Orla looks clean and uncluttered when written down. Its brevity also reduces the chances of spelling becoming a daily chore, although an unfamiliar listener may occasionally ask you to repeat it. That is an important distinction: rare baby names can be unfamiliar without actually being difficult. For parents who want a name that stands apart quickly, Orla is worth putting on the shortlist.

9. Elowen Sounds Whimsical But Reads Naturally

Elowen may sound like a storybook discovery, but its seven letters follow a fairly intuitive pattern. The Cornish name meaning “elm” reached No. 798 among U.S. girls in 2025, with 341 births, according to Nameberry. That was up from No. 898 in 2024, so Elowen is another example of an uncommon name showing upward movement. The bigger complication is the existence of alternate spellings such as Elowyn, which could lead to occasional corrections. Parents who value simplicity may prefer sticking with the established Elowen spelling rather than modifying it further.

The Best Test Happens Outside The Baby-Name List

The best rare baby names are not necessarily the ones nobody has heard before; they are often the ones people understand after hearing them once. Before deciding, say the first and last name aloud, write the initials, imagine calling it across a playground, and ask someone else to spell it after hearing it. Also check current rankings because The Bump’s 2026 baby-name tracker notes that its latest U.S. popularity information is based on 2025 births, while its separate 2026 lists track current site trends. A name that feels obscure in your neighborhood may already be climbing nationally, which is a detail parents can easily miss when choosing based only on personal experience.

Which of these names hits the sweet spot for you, and what uncommon but easy-to-spell name deserves a place on this list? Share your choice in the comments.

What to Read Next

10 Baby Names That Almost Disappeared but Could Be Ready for a Comeback

9 Baby Names That Work Whether Your Child Becomes an Artist, Athlete, or Accountant

10 Baby Names Inspired by Places Without Sounding Like Vacation Destinations

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: baby name ideas, baby names, boy names, girl names, Parenting, Pregnancy, rare baby names, uncommon baby names, unique baby names

Are Parents Buying Too Many Clothes Before Kids Actually Need Them?

September 23, 2026 | Leave a Comment

Mother helping her daughter get dressed in a bright bedroom
Buying children’s clothes months before they are needed can backfire when growth spurts, changing preferences or seasonal timing make those bargains unwearable. Buying fewer future-size pieces and filling wardrobe gaps as they appear can help families avoid wasted spending. (Pexels).

Buying the next size up can feel like smart parenting, especially when a clearance rack makes next season’s clothes look too cheap to pass up. But children do not always grow on a predictable schedule, and that bargain winter coat or stack of jeans may be the wrong size when the weather finally changes. For families trying to control a clothing budget, buying too far ahead can quietly turn savings into wasted money. The problem becomes especially relevant as clothing remains a significant part of back-to-school spending. A better strategy may be buying fewer items now and keeping more money available for what children actually need later.

Families Are Already Spending Hundreds On Clothes

The latest National Retail Federation back-to-school survey found that families with children in kindergarten through 12th grade planned to spend an average of $863.86 on back-to-school purchases in 2026. Of that amount, $250.29 was earmarked specifically for clothing and accessories, while another $174.01 was expected to go toward shoes. Those numbers help explain why seemingly small purchases can quickly strain a kids clothing budget, particularly in households with multiple children. Interestingly, 47% of shoppers said they planned to buy only the essentials for the beginning of school and replenish supplies as needed. That approach can work for clothing too, because waiting provides parents with better information about fit, weather, school activities and what their child will actually wear.

Growth Does Not Follow Your Shopping Calendar

One overlooked risk of stockpiling clothes is that children grow at different rates rather than neatly moving into a new size every six months. The American Academy of Pediatrics’ HealthyChildren.org explains that children tend to grow in spurts, with some growing as much as three times faster during certain seasons than during slower periods. That means buying size 8 shorts nine months early because they are 60% off does not guarantee they will fit when summer arrives. Shoes can be even trickier because an uncomfortable or undersized pair cannot simply be rolled at the cuffs like pants. Parents protecting a clothing budget may therefore be better off keeping only a small reserve of basics in the next size rather than building an entire future wardrobe.

A Sale Is Only A Deal If It Gets Worn

Imagine a parent finds four shirts for $8 each, two pairs of pants for $15 each and a $30 jacket during an end-of-season sale, spending $92 on clothes for next year. If the child skips that size, dislikes half the shirts or needs a different jacket by then, even $40 of unused merchandise wipes out much of the expected savings. This matters because NRF’s 2026 research on back-to-school prices found that 78% of shoppers expected higher prices on back-to-school merchandise, which can make buying early feel especially tempting. Instead of asking only, “How much am I saving today?” parents can ask, “How certain am I that my child will wear this?” That simple question shifts a clothing budget away from chasing discounts and toward calculating the actual value of each purchase.

Secondhand Clothing Changes The Math

Waiting does not necessarily mean paying full retail price later, especially as resale becomes a mainstream alternative to buying new clothes. ThredUp’s 2026 Resale Report, based partly on a survey of 3,268 U.S. consumers, projects the global secondhand apparel market will reach $393 billion by 2030 and says the U.S. secondhand market grew nearly four times faster than the broader retail clothing market in 2025. Research published in Sustainability on secondhand school uniforms also found affordability was the leading motivation for choosing used uniforms among surveyed parents, although availability, sizing and quality remained barriers. Families can check consignment stores, resale platforms, school uniform exchanges and neighborhood groups when an actual need appears instead of buying every future size in advance. Hand-me-downs can stretch a clothing budget even further, particularly for coats, special-occasion outfits and other pieces children may wear relatively few times.

Buy For The Child You Have Today

Buying ahead is not automatically wasteful, especially for predictable necessities such as socks, pajamas or a favorite brand whose sizing a parent already understands. The bigger financial risk comes from confusing a low price with guaranteed savings and filling closets with clothes based on guesses about future growth, weather and preferences. A practical compromise is to keep a limited number of next-size basics, review children’s wardrobes every few months and postpone specialized or expensive purchases until they are genuinely needed. That approach leaves room in the household budget for an unexpected growth spurt without forcing parents to ignore worthwhile sales altogether.

Do you buy your children’s clothes months ahead to catch sales, or have you learned that waiting saves more money in the long run? What strategies help you avoid buying clothes your kids never wear? Share your experiences and money-saving tips in the comments below.

What to Read Next

Here Are the Best Online Shopping Sites for Affordable Kids Clothes

Money-Saving Hacks for Parents Shopping Clearance Clothes After the Holidays

Clothes From Shein and Temu Could Be Hazardous To Your Child’s Health

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Back To School Shopping, children, clothing, Family Budget, family finances, kids clothing, Parenting, Saving Money, secondhand clothing, smart shopping

10 Baby Names That Almost Disappeared but Could Be Ready for a Comeback

September 22, 2026 | Leave a Comment

Smiling toddler resting his head on a gray pillow
Once-popular names such as Dorothy, Joan, Betty, and Harold became uncommon as generations changed. Current naming data shows why some forgotten classics may be worth watching for a comeback. (Pexels).

Baby names have a funny way of traveling through time. A name that sounds hopelessly old-fashioned to one generation can suddenly feel distinctive to the next. That cycle is helping vintage baby names attract parents who want something familiar without choosing the same names heard throughout every preschool. In fact, Nameberry found that 430 names returned to U.S. records in 2024 after disappearing for at least a decade, showing just how dramatically tastes can change.

1. Dorothy Is Already Showing Signs Of Revival

Dorothy may be one of the clearest examples of vintage baby names finding new life. The name ranked No. 421 in the U.S. in 2025, with 743 baby girls receiving it, according to Nameberry’s Dorothy data. That compares with just 385 births in 2014, meaning usage nearly doubled in 11 years. Nicknames such as Dot, Dottie, and Dolly also give parents several modern-sounding options. Dorothy demonstrates that a grandmother-era name can return without losing its history.

2. Joan Is Quietly Climbing Again

Joan once sounded firmly connected to an earlier generation, but the numbers are changing. Nameberry’s U.S. popularity data shows 222 girls received the name in 2025, up from only 75 in 2014. That is nearly three times as many babies in just over a decade. Its short spelling also fits alongside streamlined names such as Jane and June. Parents searching for vintage baby names might want to watch Joan closely.

3. Agnes Could Be Approaching A Turning Point

Agnes has the unmistakable sound of another era, which may now work in its favor. U.S. usage increased from 191 births in 2014 to 246 in 2025, according to Nameberry. The name also has international appeal, ranking particularly highly in Denmark and Sweden. That matters because American naming trends increasingly draw inspiration from well beyond U.S. borders. Agnes could appeal to families wanting something recognizable yet still genuinely uncommon.

4. Betty Has Retro Charm Without Feeling Complicated

Betty spent decades associated with an older generation, but its simplicity may give it another chance. It was given to 212 American girls in 2025 after reaching 253 births in 2024, Nameberry data shows. The name is traditionally a diminutive of Elizabeth, giving families an easy connection to a longer classic. It also fits the growing enthusiasm for cheerful, nickname-style names. Among vintage baby names, Betty feels especially easy to pronounce and spell.

5. Cecil Is Rare But Far From Gone

Cecil was once much more familiar, peaking at No. 65 for American boys in 1902. Today it is unusual: 119 boys received the name in 2025, according to Nameberry’s popularity records. That rarity could actually become an advantage for parents tired of today’s heavily used choices. Cecil also has the polished, old-school quality found in revived names such as Theodore. The tradeoff is that some families may still hear it as distinctly antique.

6. Mildred Has A Ready-Made Modern Nickname

Mildred might sound like a difficult comeback candidate until you consider Millie. The full name was given to only 98 American girls in 2025, Nameberry reports. That makes Mildred unusual while providing parents with a much lighter everyday nickname. Its traditional meaning, “gentle strength,” may add another point of appeal. For parents exploring vintage baby names, nicknames can make an older choice feel surprisingly current.

7. Harold Is Hanging On

Harold has never completely disappeared, although it now sits near the edge of the U.S. Top 1,000. There were 230 boys named Harold in 2025, placing it at No. 993, according to Nameberry. The nickname Harry gives families a familiar alternative for everyday use. That combination of formal full name and approachable nickname has helped other classics remain relevant. Harold could benefit if parents continue digging deeper into early-20th-century choices.

8. Shirley Could Eventually Feel Fresh Again

Shirley offers a reminder that yesterday’s wildly popular name can become tomorrow’s rarity. It peaked at No. 2 for American girls in 1935 but was given to only 133 girls in 2025, Nameberry reports. That dramatic shift shows how completely naming fashions can turn over. Parents has highlighted the cyclical nature of older names, including once-common choices that have become endangered. Shirley may need more time, but rarity is no longer its problem.

9. Clement Has The Ingredients For Rediscovery

Clement has history, a recognizable sound, and the friendly nickname Clem. Yet only 62 American boys received the name in 2025, according to Nameberry. That makes it a genuinely uncommon alternative to more established classics. The broader appetite for vintage baby names could eventually bring choices like Clement back into consideration. Parents should still say any unusual name aloud with their surname before committing.

10. Susan May Be Ready For Reconsideration

Susan was once so familiar that imagining it as unusual may seem strange. Yet only 222 American girls received the name in 2025, compared with 327 in 2014, according to Nameberry. That puts Susan far outside today’s most common choices. Names often need distance from their peak generation before younger parents rediscover them. Susan’s simple spelling and familiar pronunciation could eventually help it complete that cycle.

Yesterday’s Names Could Be Tomorrow’s Favorites

Nobody can guarantee which vintage baby names will become fashionable again. Still, the revival of older choices is well established: The Bump’s vintage-name guide points to renewed interest in names ranging from Daisy to Fitzgerald. Parents should consider pronunciation, initials, nicknames, family significance, and how a name may sound on an adult before deciding. A rare name today can also become unexpectedly fashionable years later, so choosing solely for uniqueness carries a risk.

Which nearly forgotten name would you bring back, and which should stay in the past? Share your pick in the comments.

What to Read Next

9 Baby Names That Work Whether Your Child Becomes an Artist, Athlete, or Accountant

10 Baby Names Inspired by Places Without Sounding Like Vacation Destinations

9 Baby Names That Sound Like Nicknames but Work Surprisingly Well on Adults

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: baby name trends, baby names, Family, old-fashioned baby names, Parenting, Pregnancy, unique baby names, vintage baby names

Your Teen’s First Job Could Change More Than Their Spending Money

September 22, 2026 | Leave a Comment

Smiling teen girl in an apron opening a shop door
A teenager’s first paycheck can become a hands-on lesson in budgeting, saving, taxes, and financial independence. Parents can provide guardrails while giving teens room to make manageable money decisions. (Pexels).

A teen first job may look like a simple exchange: a few shifts each week in return for spending money. But that first paycheck can introduce lessons about taxes, saving, workplace expectations, and the surprisingly difficult question of what to do when a manager asks you to stay late. The experience matters at a time when finding work is not necessarily easy for young people; U.S. teenagers ages 16 to 19 had a 14.1% unemployment rate in August 2026, compared with 4.1% for the overall workforce, according to federal labor data reported in the latest employment figures. For parents, that makes a first job an opportunity to teach skills that can last much longer than the job itself.

A Paycheck Makes Money Decisions Real

A teen first job turns abstract money lessons into decisions involving money your child actually earned. Instead of simply explaining budgeting, parents can help a teen divide a $200 paycheck into, for example, $120 for spending, $60 for longer-term savings, and $20 for giving or another personal goal. The exact percentages matter less than developing a repeatable habit and allowing teens to see the tradeoff between buying something today and saving for something larger. That lesson appears relevant: a Junior Achievement USA survey found that 80% of teens said knowing more about money management would positively affect how they feel about money, while 73% said they would likely take a money-management course if given the opportunity. Parents can reinforce the lesson by asking one simple question every payday: “What do you want this money to accomplish?”

Work Can Teach Skills School Cannot Replicate

Showing up for a Saturday morning shift teaches something different from completing an assignment by Friday. Teens learn that coworkers depend on them, customers can be impatient, supervisors give feedback, and being five minutes late can affect someone besides themselves. The American Psychological Association notes that part-time work can help adolescents learn how workplaces operate, manage time and money, set goals, and take pride in their accomplishments. Those experiences may become increasingly useful as teens prepare for a changing labor market; a 2026 Junior Achievement USA and Ipsos survey found that 71% of teens believed their future career would provide enough income to cover their living expenses. A teen first job gives them an early opportunity to test expectations about work against reality.

More Hours Are Not Always Better

The hidden tradeoff is that earning more money can come at the expense of sleep, schoolwork, extracurricular activities, and downtime. In August 2026, employed 16- to 17-year-olds who were at work averaged 19.5 hours during the survey reference week, while 18- to 19-year-olds averaged 29.1 hours, according to federal labor statistics. Research summarized by the American Psychological Association has associated working 20 or more hours a week during the school year with risks including insufficient sleep and lower educational attainment, although outcomes can vary among teens and circumstances. Parents therefore should not assume that accepting every available shift automatically builds a stronger work ethic. Ask whether grades, sleep, sports, family responsibilities, or college preparation are beginning to suffer, and adjust hours before the paycheck becomes more important than the purpose of the job.

That First Paycheck Can Start Decades Of Saving

One easily overlooked advantage of a teen first job is that earned income can make a teenager eligible for a custodial Roth IRA. According to Fidelity, a minor with qualifying earned income can contribute up to 100% of that income, subject to the $7,500 IRA contribution limit for 2026. A teen earning $3,000, for example, could spend $2,500 while a parent or grandparent contributes $500 to the Roth on the teen’s behalf, provided total contributions do not exceed the teen’s eligible earned income. That $500 invested at age 16 and hypothetically earning an average 7% annually would grow to roughly $16,000 by age 66 without another contribution, although investment returns are never guaranteed. Parents should verify eligibility and tax rules before contributing, especially when a teen earns money through babysitting, lawn care, or other work that may not generate a traditional W-2.

The Bigger Payoff Comes Later

The real value of a teen first job may not be measured by how much money remains in the bank when summer ends. A good first-job experience can introduce budgeting, saving, taxes, workplace communication, time management, and the reality that every dollar represents time spent earning it. Parents can help by discussing pay stubs, encouraging automatic saving, setting reasonable limits on school-year hours, and allowing manageable mistakes rather than taking complete control. The goal is not to turn a 16-year-old into a retirement expert or demand that every paycheck be saved, but to use real earnings as a practical financial education.

What did your first job teach you that you still use today, and what do you hope your teenager learns from theirs? Share your experience in the comments.

What to Read Next

6 Common Money Mistakes Kids Make When They Get Their First Job

10 Ways to Get Your Child Their First Paying Job This Summer

How Much Should a Teen Contribute Toward Their First Car?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: financial literacy, first paycheck, Parenting, parenting teens, Roth IRA, Saving Money, teen employment, teen first job, teen money management, teenagers

7 “Cheap” Kids’ Activities That Can Become Surprisingly Expensive

September 21, 2026 | 1 Comment

Two boys playing basketball on an outdoor court
Activities that look inexpensive at signup can become costly once families add equipment, supplies, travel, costumes, and recurring fees. Asking for the full annual cost upfront can help parents avoid budget surprises. (Pexels).

Parents are always looking for cheap kids’ activities that keep children busy without wrecking the household budget. The problem is that an activity advertised as free, inexpensive, or just a few dollars can carry costs that do not appear until later. Equipment, uniforms, transportation, supplies, tickets, and upgrades can transform an affordable pastime into a recurring expense. A $20 registration fee matters less than what a family ultimately spends over six or nine months. Before signing up, parents should calculate the full-season cost rather than focusing only on the advertised price.

1. Recreational Sports Can Become A Four-Figure Commitment

A neighborhood soccer or basketball league may look inexpensive until equipment, uniforms, tournaments, camps, and travel enter the picture. The Aspen Institute’s Project Play research found that families spent an average of $1,016 on a child’s primary sport in 2024, up 46% from 2019. Spending on that child’s additional sports averaged another $475, pushing total annual spending close to $1,500. A $125 league registration can therefore be a poor estimate of what the season will actually cost. Ask coaches about required equipment, tournaments, travel, private instruction, and future team fees before registering.

2. Dance Lessons Have Costs Beyond Tuition

Dance is another classic example of activities becoming more expensive as children progress. One real-world example comes from Generation Dance Company’s 2025–2026 pricing, where one weekly class costs $50 per month during its nine-month season. However, the studio also lists a $70 costume fee per class and recital tickets costing roughly $17 to $20 each. Add dance shoes, tights, leotards, photos, and transportation, and a family can easily spend hundreds beyond the advertised tuition. Parents should request an all-in estimate that includes costumes and performances before committing to a season.

3. Music Lessons May Lead To An Instrument Upgrade

Learning guitar, piano, or drums can start simply, especially when a child borrows or rents an instrument. But ongoing instruction can quickly become the biggest expense, with School of Rock Arlington listing 30-minute lessons at $220 per month. A child who sticks with music may eventually need a better instrument, replacement strings, reeds, books, accessories, repairs, or performance fees. At $220 monthly, nine months of lessons alone would total $1,980 before buying any equipment. Before purchasing an expensive instrument, ask whether rentals, used equipment, group lessons, or shorter trial programs are available.

4. “Free” Craft Projects Still Require Supplies

Crafting sounds like one of the safest cheap activities because families can often find free tutorials and classes. Yet free instruction does not necessarily mean free participation, particularly when every project requires another set of materials. For example, a Michaels Kids Club class is listed as free online, but the page lists seven suggested supply items totaling $66.93. Families who already own beads, glue, pipe cleaners, and other materials would spend much less, which makes checking the supply list important. Build a reusable craft box, substitute materials already at home, and avoid treating every project as a shopping trip.

5. Summer Day Camp Adds Up By The Week

A reasonably priced day camp can sound like a bargain when compared with overnight camp or full-time child care. According to Care.com’s updated 2026 camp cost guide, average U.S. day-camp fees run approximately $73 to $87 per day, based on American Camp Association figures. At $80 per day, five days cost $400, while six weeks would reach $2,400 before transportation, extended care, lunches, or activity fees. That makes camp one of those cheap kids’ activities where the length of participation matters as much as the daily price. Compare weekly rates, sibling discounts, financial aid, cancellation policies, and before or after-care charges before reserving multiple weeks.

6. Zoo Trips Can Encourage Extra Spending

A zoo outing may begin with admission, but food, souvenirs, parking, special attractions, and repeat visits can change the math. The Houston Zoo’s current membership page lists its family membership at $239 per year for two adults and up to three children and says membership can pay for itself in as few as two visits. That does not automatically make a membership worthwhile because separately ticketed events and discretionary purchases may still cost extra. Families should compare the membership price with what they realistically expect to spend on individual visits rather than assuming unlimited admission guarantees savings. Bringing permitted essentials and setting a souvenir budget can also prevent a modest outing from becoming an expensive day.

7. Scouting Can Carry Costs Beyond Registration

Scouting can provide outdoor activities, skill-building, and social experiences for what initially appears to be a manageable enrollment fee. However, local dues, uniforms, camping gear, trips, and activity charges can raise the actual annual cost. One Houston-area Scouting America Cub Scout pack listing currently shows a $91 cost to join plus $100 in unit dues, while noting that fundraising helps cover expenses. That means the listed starting cost is already $191 before considering camping equipment or other activities. Ask specifically what families typically spend during an entire year and whether used uniforms, shared gear, scholarships, or fundraising credits are available.

The Cheapest Price Is Not Always The Real Price

The common thread behind these activities is that the headline price rarely tells the whole financial story. Parents can protect their budgets by asking for a written list of mandatory and optional expenses before their child becomes committed to an activity. For example, three activities that appear to cost $50 each could eventually consume $1,000 or more once equipment, performances, transportation, and recurring fees accumulate. Setting an annual activities budget also makes it easier to decide which extras genuinely add value for the child.

Which supposedly inexpensive kids’ activity has surprised you most with hidden costs, and what would you warn other parents about? Share your experience in the comments.

What to Read Next

Youth Sports Cost Families $1,016 a Year on Average — 8 Expenses New Parents Don’t Expect

The New Pay-to-Play Rules in Youth Sports That Are Ruining the Game

8 After-School Activities That Can Cost Far More Than Parents Expect

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: cheap kids activities, dance lessons, Family Budget, family finances, kids activities, Parenting, Saving Money, Summer Camp, youth sports

Should Parents Pay Kids for Chores They’re Expected to Do Anyway?

September 21, 2026 | Leave a Comment

Young boy in yellow gloves scrubbing a stone wall
Paying children for chores can teach earning and money management, but experts also emphasize the developmental value of contributing to the household. Some families split the difference by keeping everyday chores unpaid while offering money for extra jobs. (Pexels).

Parents have debated allowance for generations: Should children get paid for making beds, unloading the dishwasher, or cleaning rooms when those jobs are simply part of family life? Paying can turn an ordinary Saturday chore into an early lesson about earning, budgeting, and saving, but it can also create an expectation that every contribution deserves cash. The latest data show families are already putting meaningful money behind these decisions. The better question, then, may not be whether parents should pay for chores, but which responsibilities deserve money and which should simply come with being part of a household.

Chores Have Value Even Without A Paycheck

Before attaching a price to every task, parents should remember that chores themselves can teach useful skills without any financial reward. The American Academy of Pediatrics’ HealthyChildren guidance on chores says age-appropriate household responsibilities can teach life skills, cooperation, organization, and responsibility. Research involving 9,971 children also found that frequently doing chores in kindergarten was associated with stronger self-reported social, academic, and life-satisfaction competencies by third grade, although an association does not prove chores caused those outcomes. That gives parents a reason to treat basics such as putting dirty clothes in a hamper or clearing a dinner plate as normal responsibilities. Paying for every small contribution could blur an important message: everyone who lives in a home has some responsibility for maintaining it.

Allowance Can Still Teach Real Money Skills

Allowance becomes more valuable when children actually have decisions to make after receiving it rather than automatically spending every dollar. A Journal of Consumer Affairs research review published by Wiley found that experience-based learning, financial socialization, and age-appropriate financial skills can contribute to the foundations of later financial well-being. Current Greenlight figures show how much real-world practice families may be providing: its 2025 averages were $6.44 per week for 6-year-olds and $15.26 for 15-year-olds. Instead of focusing only on earning, parents can ask children how much they plan to spend now, save for later, or set aside for a larger goal. That conversation transforms kids allowance from pocket money into hands-on financial practice.

The Hidden Problem With Paying For Everything

There is a tradeoff parents may overlook: tying every dollar directly to routine chores does not automatically produce stronger financial literacy. The OECD’s PISA 2022 financial-literacy analysis found that receiving allowance or pocket money for regularly doing chores was associated with lower financial-literacy performance in 10 participating countries and economies after accounting for several student characteristics and money experiences. That finding does not establish that chore payments cause weaker skills, but it challenges the assumption that simply paying a child automatically teaches good money habits. Parents still need to discuss saving, spending limits, tradeoffs, comparison shopping, and what happens when the money runs out. In other words, the lesson surrounding allowance may matter at least as much as the payment itself.

A Hybrid System Can Separate Responsibility From Earning

For many households, a practical compromise is creating two categories: expected family responsibilities and optional paid jobs. A 12-year-old might be expected to make the bed, put away laundry, load dishes, and keep a bedroom reasonably tidy without receiving individual payments. Bigger jobs such as washing the family car, raking a large yard, organizing the garage, or doing extra cleaning could earn money because they go beyond everyday expectations. This approach mirrors the middle-ground option described in Greenlight’s current guide to paying children for chores, which notes that some families keep routine responsibilities unpaid while compensating children for additional work. It also helps prevent a frustrating negotiation in which a child asks, “How much will you pay me?” every time a trash bag needs to go outside.

Set An Amount Your Family Can Actually Sustain

Parents do not need to match another family’s allowance, especially when household budgets and expectations differ dramatically. Suppose parents give two children $10 each every week: that seemingly modest system costs $1,040 per year, before payments for extra jobs, birthdays, or other spending money. Families should therefore decide what the allowance is supposed to cover, whether missed responsibilities reduce it, and whether children are expected to save part of it before announcing a dollar amount. Research published by ScienceDirect’s Journal of Economic Psychology found longstanding parental support for clear rules around when allowance is received and what happens when children run out of money. Consistency matters because an allowance system that changes whenever parents are busy, frustrated, or short on cash can make the lesson harder for children to understand.

The Best Pay System Teaches More Than Chore Completion

There is no universal allowance formula that works for every household, and parents do not need to turn their kitchens into miniature payroll departments. A clear system can preserve unpaid responsibilities while giving children opportunities to earn extra money and practice making financial choices with relatively small stakes. Parents should ask themselves what behavior they want to teach, what amount fits the family budget, which chores are nonnegotiable, and what children are expected to do with the money they receive. The goal is bigger than getting a bedroom cleaned today; it is helping children understand responsibility, effort, limits, and the choices attached to money.

Would you pay your kids for everyday chores, reserve payment for extra work, or keep chores and allowance completely separate—and why? Share your approach in the comments.

What to Read Next

Cheap and Engaging Ways to Teach Kids Chores That Start Paying Off Now

7 Common Chores That May Be Too Dangerous for Young Children

8 Chores Your Child Should Master By The Age of 12

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: allowance for chores, chores for kids, family finances, financial literacy, kids allowance, Parenting, Saving Money, teaching kids about money

The Cheapest Kid in the Friend Group May Actually Be Learning the Best Money Lessons

September 20, 2026 | Leave a Comment

Four teenage friends sitting together on a brick ledge
A child choosing to save instead of matching friends’ spending may be practicing budgeting, delayed gratification, and resistance to peer pressure. Small financial choices can become valuable preparation for managing money as an adult. (Pexels).

The kid who skips the $8 smoothie, waits for a sale, or says, “I don’t want to spend my money on that,” may get teased for being cheap. Yet that child could be practicing financial skills that many adults struggle to master: setting priorities, resisting social pressure, and accepting that money is limited. In a world where tapping a phone can make spending almost invisible, financial literacy for kids increasingly requires hands-on experience with real choices. Being careful with money does not necessarily mean being deprived; sometimes it means a child is learning that every dollar spent is a dollar unavailable for something else.

Spending Less Can Teach Kids About Tradeoffs

Children learn something important when they have enough money to buy some things, but not everything they want. Suppose a 13-year-old receives $12 a week and wants $60 sneakers while friends regularly spend their money on snacks after school. Saving $10 weekly means waiting six weeks for the shoes, while spending $6 each week with friends doubles the wait to 12 weeks. That simple decision teaches opportunity cost far more vividly than a lecture about budgeting. It is one reason financial literacy for kids can be strengthened when children control a limited amount of their own money rather than having parents routinely cover discretionary purchases.

Allowances Work Better When Money Has Limits

Allowances are common, but simply handing over cash does not automatically teach good financial habits. A 2025 Wells Fargo study found that 71% of parents with children ages 5 to 17 gave allowances, averaging $37 per week, while 65% said it was difficult to stand back and allow children to make their own financial mistakes. Greenlight’s 2025 data, drawn from families using its platform, found a much lower average of $13.15 per week for ages 5 to 19, showing how allowance estimates can vary substantially by sample. The important lesson is not whether a child receives $10 or $30, but whether the amount has boundaries and requires choices. Constantly replacing money after it is spent can undermine financial literacy for kids because running out never carries a meaningful consequence.

Being The “Cheap” Friend Can Build Resistance To Pressure

Peer spending can become surprisingly expensive once children reach their teen years and social activities become more independent. Piper Sandler’s Fall 2025 Teen Survey, which included 10,969 U.S. teens with an average age of 15.7, found self-reported annual spending averaged $2,213, despite being down 6% from the previous year. Meanwhile, a 2026 Bank of America study found 75% of Gen Z respondents looked for ways to save money when going out, suggesting cost-conscious socializing is hardly unusual. A teenager who suggests eating before the movies, buying a cheaper ticket, or skipping one outing is practicing how to participate socially without automatically matching everyone else’s spending. Parents can reinforce that skill by treating “I can’t afford that right now” as responsible decision-making rather than something embarrassing.

Small Money Mistakes Can Be Valuable

One hidden downside of tightly controlling every purchase is that children never experience buyer’s remorse while the stakes are small. NerdWallet’s 2025 survey found 93% of parents with children under 18 had taken some action to teach them about saving, including 45% who encouraged savings goals and 41% who opened savings accounts for their children. Yet learning to save should be paired with opportunities to make imperfect spending decisions. If a child blows $25 on a trendy item and regrets it three days later, resisting the urge to immediately replace the money creates a memorable lesson about impulse buying. Financial literacy for kids includes learning how a bad purchase feels before the mistakes involve credit cards, car loans, or hundreds of dollars.

Digital Spending Creates A New Problem For Parents

Today’s children can spend money without ever physically watching it leave their hands, which changes the teaching challenge considerably. A 2025 Achieve survey of 2,000 parents found 31% had caught their children making unauthorized online purchases, with those incidents costing parents an average of $170. The same survey found 44% of parents believed teaching financial lessons had become harder with digital money than with physical cash. Parents do not have to ban apps or debit cards, but they can require children to check balances before purchases, review transactions weekly, and distinguish subscriptions from one-time charges. Those routines make financial literacy for kids relevant to the cashless environment they will actually navigate as adults.

The Kid Who Says No May Be Practicing For Adulthood

Parents understandably want children to enjoy themselves, and being relentlessly restrictive can create its own unhealthy relationship with money. The better goal is balance: give children some money they can control, establish reasonable boundaries, let small mistakes happen, and discuss what they learned afterward. A child who occasionally declines an expensive outing is practicing a skill adults eventually need when friends earn more, lifestyles diverge, or financial priorities change. Financial literacy for kids becomes most useful when children understand that spending should reflect their own resources and goals rather than someone else’s lifestyle.

Is the most financially prepared kid in the group sometimes the one willing to say, “That’s too expensive for me”? Share your thoughts and experiences in the comments.

What to Read Next

Why Teaching Kids to Donate After the Holidays Can Save Money and Build Gratitude

Are You Accidentally Teaching Your Kids Money Doesn’t Matter?

The Truth About Teen Finances: 10 Money Habits Parents Are Teaching Kids That Keep Them Poor

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.

Filed Under: Parenting Tagged With: Allowance, budgeting, family finances, Financial Education, financial literacy for kids, kids and money, Parenting, parenting tips, Saving Money, teenagers

« Previous Page
Next Page »
  • Facebook
  • Pinterest
  • RSS
  • Twitter
Best Parenting Blogs

Most Popular

Baby

9 Baby Names That Sound Rare Without Being Hard to Spell

Evan Morgan
Baby

9 Unusual Baby Names That Sound Like They Belong to Future CEOs

Evan Morgan
Target Store

Choking Incident Prompts Recall of 49,000 Target Gigglescape “Under the Sea” Popping Toys

Evan Morgan
Frustrated Girl

Why Some Students on the Spectrum Are Labeled With ODD

Evan Morgan
Coke Bottles

12 Things Kids Took to School in the ’70s That Would Never Be Allowed Today

Evan Morgan

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette