• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

How Much Does Having a Second Child Really Add to the Family Budget?

September 30, 2026 | Leave a Comment

Young Sisters
Child care can make the cost of a second child climb quickly, especially when siblings need paid care at the same time. Reusing baby gear helps, but families should also prepare for food, insurance, medical, and everyday expenses. (Pexels).

Parents expecting baby number two already know some expenses should be easier the second time around: the crib may still be usable, the stroller is in the garage, and boxes of baby clothes may be waiting in a closet. But second child costs can still deliver a serious financial surprise, particularly when two children need paid care at the same time. The important question for growing families isn’t whether another child costs money, but which expenses actually double and which barely move.

Child Care Can Become The Budget Breaker

Child care is often where second child costs become most noticeable because families cannot simply reuse last year’s daycare spot the way they can reuse a crib. Care.com’s 2026 Cost of Care Report found average posted daycare costs of $332 a week for an infant, while daycare for two children averaged $585 weekly in its toddler-care data. That two-child figure works out to roughly $30,420 over 52 weeks, showing how quickly overlapping daycare years can reshape a household budget. Child Care Aware of America separately calculated a national average annual child-care price of $13,184 in 2025, up from $13,128 in 2024. Before trying for another baby, parents should ask local providers about sibling discounts, infant waiting lists, registration fees, annual increases, and when an older child qualifies for a less expensive classroom.

Not Every Expense Doubles With Baby Number Two

Fortunately, second child costs do not mean buying everything twice, and that distinction can make headline estimates seem less frightening. Families may reuse bassinets, high chairs, toys, books, and clothing, provided products remain safe, appropriate, and have not been recalled or expired. Housing is trickier because two young siblings may comfortably share a bedroom, but eventually needing another bedroom can turn a relatively small monthly increase into thousands of dollars annually. Transportation works similarly because an existing family vehicle might accommodate another car seat, while a cramped sedan could suddenly make a larger vehicle tempting. The smartest approach is to separate genuinely incremental expenses from purchases the household would have made anyway instead of assuming every existing family expense will double.

Food, Health Insurance And Daily Spending Still Climb

Food becomes a larger part of second child costs as children grow, even though an infant’s grocery impact may initially be limited, particularly when a family does not regularly purchase formula. LendingTree’s 2026 analysis estimates food adds $4,208 annually to the cost of raising one child in its national model, illustrating how routine expenses accumulate over time. Health coverage deserves its own calculation because adding another dependent may cost little under some family plans but substantially more under plans with different dependent-coverage tiers. KFF’s 2025 Employer Health Benefits Survey found employer-sponsored family coverage averaged $26,993 in total annual premiums, with workers contributing $6,850 on average. Diapers, wipes, medications, school supplies, activities, and birthday expenses may look manageable individually, but families should create a monthly miscellaneous-child category instead of treating these predictable purchases as financial surprises.

The Hidden Cost May Be Lost Income

The biggest overlooked expense may not appear on a receipt at all: changing how much a parent works because two child-care bills make employment less financially attractive. Before one parent quits a job or reduces hours, however, families should compare child-care expenses against lost wages plus retirement contributions, employer health benefits, Social Security earnings, and potential future raises. Parents can also test their future budget by automatically transferring their estimated second-child expense into savings for several months before the baby arrives. That exercise exposes a shortfall while there is still time to reduce debt, build emergency savings, investigate less expensive care, or adjust discretionary spending.

The Second Child Changes Some Costs More Than Others

Second child costs are rarely a simple doubling of what parents already spend because reusable gear and shared housing create savings while overlapping child care can add five figures in a single year. The most useful family budget therefore starts with local daycare quotes, the employer’s actual insurance premiums, and realistic food, medical, and transportation estimates rather than relying exclusively on national averages. Parents should also leave room for expenses they cannot predict, from unexpected pediatric bills to replacing a vehicle sooner than planned. Planning around the expensive early years can make the transition easier, particularly because full-time child-care expenses may decline substantially once children enter school.

How much would a second child change your family’s monthly budget, and which expense would concern you most? Share your experience and thoughts in the comments.

What to Read Next

Free Library Benefits That Replace Costly Children’s Activities

Childcare Costs More Than the Mortgage for Some Families — When Does Working Still Pay?

One Parent Cuts Back Work to Care for a Child: What Does That Really Cost the Family?

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Personal Finance Tagged With: baby budget, child care costs, cost of raising children, daycare costs, Family Budget, family finances, parenting expenses, second child costs

Are Family Photo Days Becoming Another Expensive Parenting Obligation?

September 17, 2026 | Leave a Comment

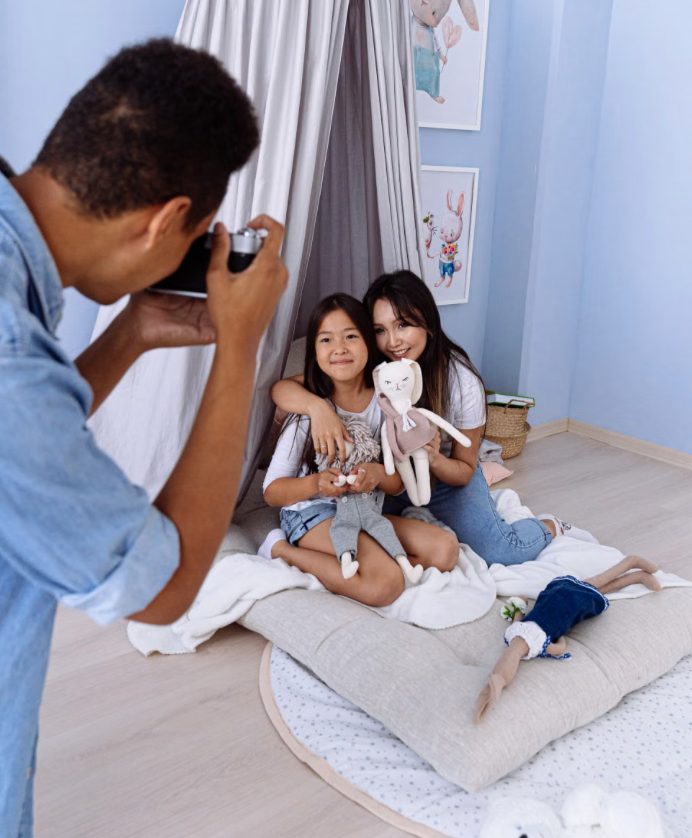
Photographer Taking Family Photo
</strong> Professional family photo sessions can cost several hundred dollars before parents add outfits, prints, styling, and other extras. Setting a budget before booking can keep a meaningful tradition from becoming a financial obligation. (Pexels).

Family photo day can start with a simple goal: get one good picture of everyone together before the kids grow another six inches. Then comes the photographer deposit. Someone needs a new shirt. Another child needs shoes. Maybe there’s a haircut, holiday cards, prints for grandparents, and the irresistible temptation to buy extra digital images once the gallery arrives.

Suddenly, preserving a family memory has become a several-hundred-dollar event. Professional photography can absolutely be worth the money. But as family portraits become more elaborate—and more visible on social media—parents may want to separate the pictures they genuinely value from another parenting expense they feel obligated to pay.

Family Photography Really Can Cost Several Hundred Dollars

The price isn’t entirely in parents’ imaginations. The Bureau of Labor Statistics reported that prices in its photographers and photo-processing category were 3.8% higher in August 2026 than a year earlier. Actual family-photography prices vary enormously based on location, photographer experience, session length, and what’s included.

For example, one current Raleigh-area photographer lists a one-hour family session at $600. That includes 25 retouched digital files, while a 20-minute mini session costs $400 and includes seven files. Another photographer in the same market charges $375 for a family session lasting up to an hour but includes only five digital images. A 20-minute seasonal mini costs $300 and includes three images.

That illustrates why asking only, “How much is the session?” can give parents the wrong answer.

The $375 Session Might Not Really Cost $375

Imagine booking that $375 session because it fits your budget. You receive the gallery and discover five photographs are included—but you love 15. That photographer currently charges $225 for 15 digital images or $300 for the entire gallery, meaning the final photography bill could be substantially higher depending on what you select.

Other photographers structure packages differently. Some include dozens of files or the complete gallery from the beginning.

Before paying a deposit, ask exactly what you’re getting: session length, number of people allowed, number of edited images, additional-image prices, print costs, travel fees, taxes, and any required minimum purchase. Otherwise, you’re comparing advertised prices rather than actual family-photo costs.

Mini Sessions Can Save Money, But Read the Details

A mini session can be a good compromise for families who mainly want an updated portrait for the wall or holiday card. Current examples show just how different those packages can be.

One Raleigh-area photographer charges $300 for a 20-minute seasonal family mini with three digital images, while another lists a 20-minute mini at $400 with seven retouched digital files. That doesn’t mean either price is unreasonable. It means the word “mini” describes the session format, not necessarily a bargain price.

Ask how many images are included, whether you’ll be able to purchase extras and how much those additional files cost. Also consider your children. Fifteen or 20 minutes may be plenty for older kids who cooperate easily, but paying for a tightly scheduled mini can be frustrating if your toddler needs 15 minutes just to stop hiding behind your leg.

The Photographer May Be Only Half the Photo-Day Budget

Now add the expenses that don’t appear on the photographer’s website. Suppose a family books a $375 session and buys $60 worth of clothing for each parent and two children. The family has already reached $615 before buying a single print. Add $35 for a child’s haircut, $50 for holiday cards, and $40 for framed prints for grandparents, and photo day reaches $740.

That’s an illustrative example rather than a national average, but it’s exactly why families should calculate the entire event instead of looking only at the session fee.

You don’t need new outfits, professional hair and makeup, restaurant reservations afterward or an elaborate coordinated wardrobe to take meaningful family photographs. Building everyone’s outfit around clothing already in the closet can eliminate one of the easiest photo-day expenses.

Social Media Can Make Optional Spending Feel Normal

There’s another reason family photos can start feeling less optional: we see everyone else’s. Research suggests social comparison really can influence how parents perceive expectations.

A 2026 study published in Family Relations involving 909 parents found that upward comparisons with other parents on social media were associated with parental anxiety and overprotective parenting behaviors. That study wasn’t specifically about professional photography, so it doesn’t prove Instagram causes parents to book expensive portrait sessions. But it does provide useful context for a familiar experience: repeatedly seeing polished examples of other families can affect perceptions of what “normal” parenting looks like.

Earlier Pew Research Center research found that 24% of parents who used social media said they at least sometimes felt pressure to post things that made them look like a good parent. A beautiful annual family portrait can be a tradition you love without becoming evidence that you’re doing parenting correctly.

Understand What “Digital Images Included” Actually Means

Parents should also understand what they’re buying when a photographer promises digital files. The U.S. Copyright Office explains that photographers generally own copyright in the original photographs they create from the moment the images are made. Receiving a digital image therefore doesn’t automatically mean you’ve purchased the copyright.

Many family photographers instead provide clients with a personal-use or print release allowing them to download, share, and print selected photographs. For example, several current photographers explicitly include high-resolution digital files and print releases in their family packages.

Before booking, ask whether you receive high-resolution files, whether you can print them yourself, whether social-media sharing is permitted, and whether downloaded images contain watermarks. Those questions are especially important if your main goal is making your own holiday cards or inexpensive prints.

Try a Family Photo Budget Before You Book

Instead of deciding whether professional photography is “too expensive,” decide what family photos are worth to your family. Suppose you set a $400 annual photography budget. You might spend all $400 on one professional session, book a $200 mini and keep the remainder for prints and cards, or skip professional photographs this year and put the money toward a larger milestone session next year. Another option is alternating years.

A family that spends $500 on professional portraits every other year instead of annually reduces the average cost to $250 per year while still documenting how everyone changes over time. That approach can be particularly useful when you’d rather save professional photography for newborn pictures, graduations, milestone birthdays, or extended-family gatherings.

Some of the Best Family Pictures Cost Almost Nothing

Professional photographers bring skill, equipment, editing experience, and an ability to get good photographs from children who seem determined not to cooperate. But they’re not the only people capable of documenting your family. Modern smartphones, inexpensive tripods and camera timers make it possible to take surprisingly good family pictures at home, at a park or during a vacation you’re already taking.

You can also trade photo-taking duties with another family: take their pictures for 10 minutes, then have them take yours. The result may not belong in a professional photography portfolio, but twenty years from now you may care considerably more about who’s in the photograph than whether everyone wore perfectly coordinated shades of beige.

Make Family Photos a Choice, Not Another Parenting Bill

There’s nothing frivolous about paying for professional family photography when you can afford it and genuinely value the results. The problem begins when an optional tradition quietly becomes another annual bill parents believe they’re supposed to pay. Before booking, calculate the all-in cost: photographer, extra images, clothes, grooming, travel, prints, and cards. Then compare that amount with what else the same money could do for your family. Maybe you happily decide the photographs are worth every dollar. Or maybe this is the year you put the phone on a tripod, tell everyone to squeeze together, and accept that one child will probably make a ridiculous face. Either way, your family still gets the memory.

How much would you comfortably spend on family photos, and do you think social media has made professional photo sessions feel more obligatory for parents?

What to Read Next

Why Your Happy Family Photos Can Trigger Envy and Anxiety

Great Family Photos Don’t Have to Be Expensive

8 Ways Kids Can Quietly Blow the Family Budget Once School Starts

Evan Morgan

Evan Morgan has been a full-time freelance writer and editor for 10+ years. When not working, he enjoys catching the latest true crime documentary or getting lost in a good book.
Filed Under: Parenting Tagged With: Family Budget, family photo sessions, family photos, holiday photos, parenting costs, parenting expenses, photography costs, Saving Money

7 Parenting Expenses That Quietly Drain Budgets After the Holidays

January 27, 2026 | Leave a Comment

These Are 7 Parenting Expenses That Quietly Drain Budgets After the Holidays
Image Source: Shutterstock.com

In Fayetteville, GA, a quiet rollout just rewired family budgets. In Volusia County, Florida, school administrators executed the same shift under a different name. Parents missed it because the change hid behind routine post-holiday paperwork and a legal loophole timed for the 2025–2026 season.

This exists because the hidden costs of kids escalated without a press conference. Districts framed it as modernization. Vendors framed it as safety. Families now face an unprecedented squeeze that starts local and bleeds national.

Post-Holiday Costs For Your Family

Statehouses set the tone. Georgia HB 268 expanded behavioral monitoring standards tied to school-issued devices. HB 340 tightened “distraction” compliance and pushed enforcement costs downstream. Florida Statute 39 sharpened reporting triggers tied to digital conduct. Together, they created seven budget drains for your family that only activate after the holidays, when parents already run thin.

Silent Fee #1: device compliance insurance. Districts require protection plans to meet 2026 school policy standards. Families pay monthly or risk confiscation.

Silent Fee #2: monitoring subscriptions. HB 268 compliance pushes software licenses onto households when students use devices at home.

Silent Fee #3: tutoring by mandate. HB 340 discipline escalations trigger “corrective services.” Parents pay for approved tutors to avoid suspensions.

Silent Fee #4: transportation penalties. Attendance enforcement tightens. Missed buses rack up ride-share costs or paid aftercare.

Silent Fee #5: legal consults. Florida Statute 39 reporting thresholds push cautious parents to attorneys after algorithmic flags.

Silent Fee #6: extracurricular tolls. Eligibility rules now hinge on compliance metrics, not grades. Families pay club fees to preserve transcripts.

Silent Fee #7: data recovery and replacement. Confiscations and resets erase work. Parents fund recovery or replacement to meet deadlines.

Districts cite safety. Vendors cite efficiency. The bill lands on kitchen tables and it makes the beginning of the new year, already stressful, even worse.

The Bottom Line For Your Bottom Line

High-stakes parenting now taxes money, privacy, and future access. Ignore these drains, and parents lose more than cash. Monitoring subscriptions siphon bank accounts and crater credit utilization through monthly churn. Legal consults drain emergency funds. Eligibility rules burn social capital when kids exit teams and networks.

Privacy erodes first; opportunity follows. Parents who delay absorb higher costs later because compliance penalties stack fast and publicly. Fayetteville parenting forums now document the same pattern Volusia parenting groups flagged last semester. Loss aversion rules here. Pay early, or pay reputational interest forever.

These Are 7 Parenting Expenses That Quietly Drain Budgets After the Holidays
Image Source: Shutterstock.com

What’s Best For Your Budget?

Choose now. Safety with surveillance or liberty with risk—which value earns your signature for the 2026 school policy era? Comment and pick a side.

You May Also Like…

9 January Budget Hacks Parents Use to Recover From Holiday Spending

Why Meal-Planning During the Holidays Can Save You More Than Just Money

7 Old-School Parenting Habits That Still Save Families Money

Money-Saving Hacks for Parents Shopping Clearance Clothes After the Holidays

How to Stretch Your Holiday Gift Budget Without Sacrificing Fun for Kids

Brandon Marcus
Brandon Marcus
Brandon Marcus is a writer who has been sharing the written word since a very young age. His interests include sports, history, pop culture, and so much more. When he isn’t writing, he spends his time jogging, drinking coffee, or attempting to read a long book he may never complete.

Filed Under: Parenting Tagged With: Family, family spending, holiday expenses, holiday spending, Holidays, Parenting, parenting expenses, Spending

Childcare Costs Are Crippling Families: The Economic Crisis No One Is Talking About

October 31, 2025 | Leave a Comment

Childcare Costs Are Crippling Families: The Economic Crisis No One Is Talking About
Image source: shutterstock.com

For many families, childcare costs have become the single biggest financial obstacle standing between stability and survival. What was once a manageable expense has now grown into an economic burden rivaling rent or mortgage payments. Parents are working longer hours, taking on side jobs, or delaying major life goals just to afford safe, reliable care for their children. Yet, despite the growing strain, the national conversation rarely focuses on the crushing financial pressure parents face. Understanding the true impact of the cost of childcare reveals just how deeply this crisis affects families, workplaces, and the economy as a whole.

The Soaring Price of Childcare

The skyrocketing childcare costs are leaving families with impossible choices. In many cities, full-time daycare for one child now costs as much as in-state college tuition. Even dual-income households struggle to balance these expenses alongside rising housing, healthcare, and food prices. Single parents face an even steeper challenge, often spending a third or more of their income on care. The result is a growing number of families forced to choose between quality care and financial security, a decision no parent should have to make.

How Childcare Costs Affect Workforce Participation

The economic ripple effects of the high cost of childcare extend far beyond individual families. Many parents, particularly mothers, are scaling back their work hours or leaving the workforce entirely because the cost of care outweighs their earnings. This loss of labor not only impacts household income but also limits career advancement and long-term financial stability. Employers, in turn, face reduced productivity and talent shortages as skilled workers step away. The nation’s overall economic growth suffers when parents are priced out of participation in the labor market.

Regional Disparities in Childcare Costs

While the cost of childcare is a national issue, they vary dramatically depending on where families live. Urban areas tend to have higher fees due to increased operational expenses and limited facility space. Rural families, on the other hand, often face a shortage of licensed providers, forcing long commutes or reliance on unregulated care. States with stronger childcare subsidies or tax credits offer some relief, but access and funding remain inconsistent. These regional disparities highlight how geography can determine a family’s financial future and ability to thrive.

The Hidden Toll on Family Well-Being

Beyond the financial strain, the cost of childcare take a heavy emotional toll on parents and children alike. Constant budget stress can lead to anxiety, sleep loss, and family conflict. Parents often experience guilt over leaving their child in less-than-ideal arrangements because higher-quality care is unaffordable. Children in unstable care environments may experience inconsistent routines and limited developmental support. The economic crisis of childcare costs is also a mental health crisis, quietly affecting millions of households across the country.

Childcare Providers Are Struggling Too

Ironically, the rising childcare costs haven’t translated into big profits for the people providing care. Many childcare workers earn near-minimum wage despite performing one of society’s most critical jobs. Facilities face rising rent, insurance, and staffing expenses, which force them to raise tuition just to stay open. The sector is also struggling with staff turnover as workers seek higher-paying opportunities in other industries. This imbalance—high prices for families but low pay for workers—underscores how unsustainable the current childcare system truly is.

The Long-Term Economic Impact

The economic consequences of the soaring cost of childcare reach far into the future. When parents can’t afford care, fewer children participate in early education programs, which affects school readiness and long-term achievement. Families that reduce work hours or leave jobs lose income, benefits, and retirement savings, leading to financial insecurity later in life. Economists estimate that the U.S. loses billions annually due to childcare-related workforce disruptions. Without systemic reform, these losses will continue to erode both family wealth and national productivity.

Government Efforts and Policy Gaps

While policymakers acknowledge the childcare crisis, progress toward lasting solutions has been slow. Federal and state programs like the Child Care and Development Block Grant and tax credits help, but funding is limited and eligibility varies widely. Some states have introduced universal pre-K or employer-sponsored care incentives, but access remains uneven. The lack of cohesive national policy means families are left to navigate a patchwork of options with no guaranteed relief. Until childcare is treated as essential infrastructure, families will continue to shoulder unsustainable costs.

Practical Steps Families Can Take

While there’s no quick fix for the rising cost of childcare, families can explore creative ways to reduce the burden. Some parents form childcare co-ops, rotating responsibilities with trusted friends or neighbors. Others use employer childcare assistance programs or flexible spending accounts to offset expenses. Families can also look into local nonprofits that offer sliding-scale tuition or subsidies based on income. Sharing resources, advocating for workplace flexibility, and supporting public policy reform are all practical ways to make childcare more accessible.

Why Addressing Childcare Costs Benefits Everyone

Fixing the childcare crisis is not just a parenting issue—it’s an economic imperative. When childcare becomes affordable and reliable, more parents can work, businesses retain skilled employees, and children receive the early education they need to succeed. Societies that invest in childcare infrastructure see stronger economies and healthier families. Addressing childcare costs creates a foundation for long-term growth, equality, and stability. The time for conversation has passed; meaningful action is what families truly need.

How has the cost of childcare affected your family’s financial choices or career plans? Share your story in the comments below.

What to Read Next…

8 Items Daycares Often Ban Without Explaining Why

Daycare Shock: 10 Truths About Daycare Costs That Break Your Budget

8 Subsidy Traps That Cause Families to Lose Childcare Aid

You’re Overpaying: 8 Hidden Fees In Daycare Contracts That Surprise You

Top 10 States Where Childcare Costs Now Exceed Rent

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Money and Finances Tagged With: childcare costs, early education, economic crisis, family finances, financial planning, parenting expenses, public policy, working parents

The Unexpected Cost: 11 Unexpected Medical Bills That Bankrupt New Parents

July 31, 2025 | Leave a Comment

The Unexpected Cost 11 Unexpected Medical Bills That Bankrupt New Parents
Image source: 123rf.com

Becoming a parent is a life-changing moment filled with joy, exhaustion, and—for many—financial shock. Even with insurance, new parents often find themselves buried under unexpected medical bills they never saw coming. From delivery room fees to postnatal surprises, these costs add up fast and can tip families into serious debt. The reality is, it’s not just the baby gear or daycare that drains your bank account—it’s the hidden charges buried in medical fine print. Here are 11 unexpected medical bills that have blindsided new parents and how you can avoid getting caught off guard.

1. Surprise Delivery Room Charges

Even if you plan for a hospital birth, don’t assume everything is covered by your insurance. Unexpected medical bills often begin with delivery room fees for things like anesthesia, fetal monitoring, or extra hours in labor. If the doctor uses special equipment or techniques, those costs may be itemized separately. You might even get billed for nurses you didn’t know were out-of-network. Always request an itemized bill and clarify what’s included in your hospital’s labor and delivery package.

2. NICU Stays You Didn’t Plan For

If your baby ends up in the Neonatal Intensive Care Unit—even for a short stay—the cost can be staggering. A day in the NICU can run into thousands of dollars, especially if your newborn needs respiratory support, IVs, or constant monitoring. These unexpected medical bills often hit hardest when insurance only partially covers certain treatments or specialists. Even families with good plans find themselves footing huge out-of-pocket expenses. Ask about NICU coverage when reviewing your prenatal benefits so you’re not surprised later.

3. Pediatrician Visits in the Hospital

You may assume the in-hospital pediatrician visit is included with your baby’s birth. But if the doctor is out-of-network, you’ll get a separate bill—and it won’t be cheap. Many hospitals have rotating pediatricians who check newborns before discharge, and you don’t get to choose. These unexpected medical bills often show up weeks after you’ve gone home. Ask ahead if you can request an in-network pediatrician or at least get a cost estimate.

4. Hearing and Newborn Screenings

Many states require newborn hearing tests and metabolic screenings, but that doesn’t mean they’re free. Some hospitals charge separate lab or technician fees for these tests, even though they’re standard care. Parents often assume these screenings are part of the bundled hospital cost, only to receive bills later. These unexpected medical bills are usually small but still frustrating when they come unannounced. Check with your provider about how these screenings are billed.

5. Lactation Consultations

If breastfeeding is difficult, your hospital may send a lactation consultant to help—but they rarely tell you it comes with a price tag. These consultations can cost hundreds of dollars if they’re not covered by your insurance. Even short sessions during your stay or after discharge may be billed separately. Since breastfeeding support is crucial, this becomes one of the most emotionally stressful unexpected medical bills. Verify whether lactation support is covered under your plan before delivery.

6. Ambulance Rides During Labor

In some cases, labor doesn’t go as planned and an ambulance transfer between facilities becomes necessary. Even with insurance, ambulance rides can leave parents with hundreds or even thousands of dollars in unexpected medical bills. Coverage often depends on whether the transport was deemed “medically necessary” by insurance providers. The fine print can make the difference between a covered service and a big debt. If you have a high-risk pregnancy, talk to your provider about emergency transport coverage.

7. Epidural Charges Not Fully Covered

An epidural might be a standard part of your birth plan, but the billing for it can be anything but standard. Anesthesiologists may not be in-network, and additional fees can apply based on how long the medication is administered. New parents are often shocked to receive a separate bill from the anesthesiology department. These unexpected medical bills are especially common in large hospitals with multiple providers. If pain management is part of your plan, double-check network status and coverage.

8. Outpatient Follow-Up Appointments for Baby

After discharge, your newborn may need weight checks, jaundice evaluations, or feeding assessments. Some of these follow-ups may not be covered as part of a routine wellness visit, depending on your plan. That means you could be charged full price for labs or procedures that seem minor. These unexpected medical bills tend to sneak in one appointment at a time. Make sure you understand your baby’s post-discharge care schedule and ask what’s covered.

9. Mental Health Support for Moms

Postpartum depression is real, and getting professional help should never be a luxury. Unfortunately, therapy, support groups, and even medication management often come with high out-of-pocket costs. Mental health coverage varies wildly by plan, and not all providers are in-network. These unexpected medical bills hit when families are already stretched emotionally and financially. Before birth, check your mental health coverage and search for in-network therapists who specialize in postpartum care.

10. Lab Work and Blood Tests

If you or your baby need additional lab work, don’t assume it’s automatically included in your hospital bill. Many hospitals use third-party labs, which can mean unexpected medical bills from companies you’ve never heard of. Even routine bloodwork can lead to surprise charges if the lab is out-of-network. Always ask which labs your hospital uses and whether your insurance works with them. Reviewing your Explanation of Benefits (EOB) can also help you catch problems early.

11. Out-of-Network Specialists Without Your Knowledge

During childbirth or postpartum recovery, multiple specialists may pop in and out of your hospital room. You might not even remember who they were, but you’ll remember the bills. Anesthesiologists, pediatricians, or surgeons may not be covered even if the hospital is. These are some of the most frustrating unexpected medical bills because they’re completely out of your control. Consider calling your insurance provider before your due date to ask how to avoid out-of-network surprises.

What You Don’t Know Can Hurt Your Wallet

Being a new parent is hard enough without the weight of unexpected medical bills threatening your financial stability. These charges often appear without warning and pile up fast, leaving many families reeling. The best way to protect yourself is to plan ahead—review your insurance carefully, ask questions early, and keep records of every bill. While you can’t predict every cost, you can prepare to navigate the system with confidence. Your financial health matters just as much as your family’s physical health.

Have you faced any unexpected medical bills as a new parent? Share your experience or tips for others in the comments below!

Read More:

11 Medical Bills After A New Baby That Shock Parents

8 Hidden Fees In Daycare Contracts That Surprise You

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Money and Finances Tagged With: financial planning, hospital costs, insurance for families, medical billing tips, new parent finances, newborn care costs, parenting expenses, unexpected medical bills

Unexpected Bills: 11 Medical Bills After A New Baby That Shock Parents

July 29, 2025 | Leave a Comment

Unexpected Bills 11 Medical Bills After A New Baby That Shock Parents
Image source: 123rf.com

There’s nothing quite like holding your newborn for the first time—until the hospital bills start arriving. For many new parents, the financial surprises come not in the form of diapers or formula, but from charges they never expected. Even with insurance, the range of expenses related to labor, delivery, and postpartum care can be eye-opening. From routine procedures to surprise fees buried in the fine print, those first weeks home can bring a wave of invoices that threaten to overshadow the joy. Let’s break down the most common medical bills after a new baby that catch parents off guard so you can be better prepared.

1. The “Extra” Delivery Room Charges

Many parents are stunned to find out that not all aspects of the delivery room experience are covered under standard maternity coverage. Charges can include everything from fetal monitoring to use of the birthing tub—even if it wasn’t used. Some hospitals also bill separately for a labor and delivery room versus a postpartum recovery room. These costs add up quickly, especially if labor is long or complications arise. Always ask in advance for a breakdown of what’s included in your hospital’s delivery package.

2. Epidural Anesthesia Fees

Getting an epidural for pain management is common, but few realize it often comes with a separate anesthesiologist bill. Even when administered in a hospital, the anesthesia team may bill independently from the hospital itself. Parents are frequently shocked to learn their insurance only covers part of this cost, depending on the provider’s network status. The bill for an epidural alone can reach several thousand dollars. Always check whether your anesthesiologist is in-network before giving the go-ahead.

3. NICU Charges for the Newborn

If your baby requires even a brief stay in the Neonatal Intensive Care Unit (NICU), the cost can be staggering. Charges often include daily room fees, specialized care, and constant monitoring—even for minor issues. Some parents mistakenly believe their newborn’s care is automatically rolled into their maternity coverage. In reality, your baby needs to be added to your insurance within 30 days for coverage to kick in. A short NICU stay can generate bills topping $10,000 without proper coverage.

4. Out-of-Network Pediatricians at Delivery

Many parents are surprised to learn the pediatrician who first examines their newborn may not be in their insurance network. Even if you’re delivering at an in-network hospital, individual doctors working there may bill separately. That newborn exam could cost hundreds, especially if it’s performed by a specialist or at odd hours. You usually don’t get to choose the pediatrician on call. Call ahead to the hospital to ask how they assign pediatricians and whether they accept your insurance.

5. Unexpected Lab Work and Newborn Screenings

Hospitals often run multiple tests on newborns in the first 24–48 hours. These include hearing tests, blood screenings, and genetic disorder panels, which aren’t always fully covered. Some of these tests are mandated by state law, while others are optional and billed separately. Parents frequently receive lab bills weeks later, wondering what the tests were even for. Always ask what’s included in newborn care and review any consent forms for optional tests.

6. Postpartum Mom’s Follow-Up Appointments

Postpartum care doesn’t end when you leave the hospital. You’ll likely have at least one follow-up appointment, and if complications arise, there may be several. While routine checkups may be included in maternity coverage, many insurance plans treat additional visits as general health care. These appointments can include wound checks, mental health screenings, and lactation consultations. It’s worth clarifying with your provider which postpartum services are considered preventive.

7. Lactation Consultant Visits

Lactation support can be a huge help, but it also comes with a cost. While the Affordable Care Act requires most plans to cover breastfeeding support, the reality is more complicated. Not all consultants are in-network, and not all plans cover unlimited visits. Some parents pay out of pocket for multiple sessions, especially if they struggle with latch issues or milk supply. Ask your pediatrician or OB for referrals to consultants that accept your insurance.

8. Circumcision Fees

If you choose to have your baby circumcised, be prepared—it’s often not included in standard newborn care. Many insurance plans treat it as elective, even if it’s done in the hospital. The cost may range from a few hundred to over a thousand dollars depending on the provider and setting. Some pediatricians don’t perform the procedure at all, requiring a referral to a specialist. Always ask beforehand about costs and insurance coverage.

9. Hospital “Boarding” Fees for Baby

Yes, your baby can be charged for staying in your hospital room. Some hospitals bill separately for what they consider “nursery services,” even if your baby never leaves your side. These charges can include bedding, nursing care, or even monitoring. Many parents assume it’s all part of their stay, only to be surprised by an itemized bill later. Be sure to ask what charges you might see for your newborn’s stay in your room.

10. Hearing Screenings Not Covered

Newborn hearing tests are required in most states, but that doesn’t mean they’re free. If the test is done by an outside contractor, it could be billed separately and not covered fully by insurance. Some parents report receiving bills months after discharge with no prior notice. You can ask the hospital who conducts the screening and how it will be billed. This can help prevent a surprise from showing up in your mailbox later.

11. Delayed Insurance Enrollment Penalties

The moment your baby is born, they need to be enrolled in your insurance plan—but not everyone realizes how urgent this is. If you delay, your insurance may not retroactively cover any of the baby’s hospital care. That means you could be on the hook for thousands in medical bills after a new baby if they aren’t added in time. Most insurers give a 30-day window but earlier is always better. Add your baby to your plan the same week they’re born to avoid costly missteps.

Prepare Now to Avoid Being Blindsided Later

The birth of a child should be filled with love and excitement; not stress over invoices you didn’t see coming. Understanding the kinds of medical bills after a new baby that commonly shock new parents can help you plan ahead and ask the right questions. A quick conversation with your insurer or provider can often save you from a hefty financial hit. No one can predict every outcome, but a little awareness goes a long way. Stay informed, and you’ll feel more in control of your growing family’s financial future.

Have you encountered any surprise bills after your baby was born? Share your story in the comments—we’d love to hear what caught you off guard.

Read More:

11 Medical Bills That Bankrupt New Parents

8 Hidden Fees In Daycare Contracts That Surprise You

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Money and Finances Tagged With: baby hospital bills, first-time parents, maternity insurance, newborn costs, NICU charges, parenting expenses, postpartum care, surprise medical bills

The Unexpected Expense: 11 Tax Breaks For Parents You Didn’t Know Existed

July 25, 2025 | Leave a Comment

The Unexpected Expense 11 Tax Breaks For Parents You Didn't Know Existed
Image source: 123rf.com

Raising kids is expensive, and sometimes it feels like the bills never end. Between school supplies, medical expenses, and never-ending grocery trips, your bank account can take a serious hit. But what if you could put some of that money back in your pocket—legally? While most parents know about the Child Tax Credit, there are several lesser-known tax breaks for parents that often go unused. If you’re looking for ways to ease the financial burden of parenting, these 11 tax benefits could give your budget the boost it needs.

1. Child and Dependent Care Credit

If you pay for childcare while you work or look for work, you may be eligible for the Child and Dependent Care Credit. This includes daycare, preschool, summer camps, and even babysitters in certain cases. The amount of credit depends on your income and how much you spend on care, but it can be up to 35% of your qualifying expenses. Make sure your provider gives you a receipt with their tax ID number to claim it. Many parents miss this opportunity because they assume it only applies to daycare centers.

2. Earned Income Tax Credit (EITC)

The Earned Income Tax Credit is one of the most valuable tax breaks for parents, yet it often goes unclaimed. Designed to help low- to moderate-income families, this credit can reduce your tax bill or even result in a refund. The more children you have, the higher the credit. Income thresholds change each year, so it’s worth checking eligibility even if you didn’t qualify previously. Filing taxes with a software that screens for credits can help you avoid missing it.

3. Adoption Tax Credit

Adopting a child is a big emotional and financial commitment, but the government offers some relief through the Adoption Tax Credit. This credit covers up to a set amount of qualified adoption expenses, including court costs, attorney fees, and travel. Even adoptions through foster care may qualify. It’s not refundable, but it can be carried forward for up to five years if you don’t use the full credit in one year. It’s one of the more overlooked tax breaks for parents navigating adoption.

4. American Opportunity Tax Credit (AOTC)

If you have older kids in college, the AOTC can cover up to $2,500 per student for tuition, books, and other school-related expenses. The credit applies to the first four years of higher education and is partially refundable. That means you could get money back even if you owe zero taxes. Just make sure your student is enrolled at least half-time in a degree program. Keep those tuition and supply receipts organized for tax time.

5. Lifetime Learning Credit

Not just for your kids—if you or your spouse are taking college courses, you could qualify for the Lifetime Learning Credit. It’s worth up to $2,000 per return and applies to nearly all post-secondary education. There’s no limit to how many years you can claim it, unlike the AOTC. You don’t need to pursue a degree either—just take qualified courses from an eligible institution. If you’re furthering your education while parenting, this tax break can help offset the cost.

6. Student Loan Interest Deduction

Paying off student loans while raising kids? You may be able to deduct up to $2,500 in interest paid on qualified student loans each year. This deduction is available even if you don’t itemize your deductions. It phases out at higher income levels, so double-check your eligibility based on your adjusted gross income. It’s a small win, but every little bit helps when juggling education and parenting expenses.

7. Flexible Spending Accounts (FSAs)

FSAs aren’t a credit or deduction, but they are one of the most useful tax breaks for parents. By contributing pre-tax dollars to a dependent care FSA through your employer, you can set aside up to $5,000 per year for childcare expenses. This reduces your taxable income, which can lower your overall tax bill. Just be careful—FSAs are use-it-or-lose-it accounts, so plan your yearly contributions wisely. Check with your HR department during open enrollment to see if it’s available to you.

8. Head of Household Filing Status

If you’re a single parent, filing as Head of Household instead of Single gives you a higher standard deduction and more favorable tax brackets. To qualify, you must pay more than half the cost of maintaining your home and have a qualifying child who lives with you more than half the year. This status can significantly reduce what you owe. It’s one of the easiest ways to maximize your return as a single parent. Yet many eligible filers don’t take advantage simply because they don’t realize they qualify.

9. Child’s Investment Income

If your child earns investment income, you may need to report it on your tax return under the “kiddie tax” rules. However, you can also use IRS Form 8814 to include their interest and dividends with your own return, potentially simplifying the process. While this won’t reduce your tax bill, it’s helpful to know how to avoid penalties and report the income correctly. It’s also a good opportunity to teach older kids about taxes. Understanding this rule can keep you compliant while minimizing stress.

10. State-Specific Credits and Deductions

Many states offer their own tax breaks for parents, from back-to-school tax holidays to credits for private school tuition or dependent care. These vary widely, so be sure to check your state’s Department of Revenue website. Some states mirror federal credits, while others provide additional benefits. Even renters or foster parents may qualify in certain locations. Don’t overlook what your state may be offering just because it’s not on your federal return.

11. Saver’s Credit

If you’re contributing to a retirement account while earning a modest income, you could qualify for the Saver’s Credit. This credit rewards you for saving money—something many parents put off during the child-rearing years. You can claim up to 50% of your contributions to an IRA or 401(k), depending on your income. It’s not just about the future—it helps now, too. It’s one of those long-game tax breaks for parents that builds toward financial stability.

Take What You’re Owed Without Leaving Money Behind

Parenting is expensive enough without missing out on savings that are legally yours. These lesser-known tax breaks for parents can add up to hundreds or even thousands of dollars each year, if you know where to look. A little research, a few smart questions at tax time, and the right paperwork could make your refund a lot more satisfying. Don’t assume you’ve claimed everything just because you checked the basic boxes. The IRS may not remind you—but your wallet will thank you.

Which of these tax breaks for parents were you most surprised to learn about? Have you used any of them already? Let us know in the comments!

Read More:

10 Financial Habits Keeping Parents Stressed

9 Money Mistakes That Cost New Parents Fortunes

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Money and Finances Tagged With: budgeting for families, child tax credit, Family Finance, hidden tax benefits, IRS credits, money-saving tips, parenting expenses, tax breaks for parents, tax tips

Tax Shock: 11 Unexpected Taxes for New Parents

July 4, 2025 | Leave a Comment

Tax Shock 11 Unexpected Taxes for New Parents
123rf.com

Welcoming a new baby into your family is an exciting time filled with love, learning—and yes, lots of spending. But what many families don’t anticipate are the unexpected taxes for new parents that can show up in surprising ways. From hospital bills with hidden surcharges to overlooked tax liabilities related to childcare, the fine print can hit hard when you’re already stretching your budget. While some tax breaks do exist for parents, they’re not always enough to offset the extra costs that sneak up after bringing a baby home. Here’s a closer look at 11 taxes and fees new parents should keep an eye on.

1. Hospital and Delivery Fees with Taxable Add-ons

Even with good insurance, many new parents are shocked to learn that some hospital items—like take-home supplies, private rooms, or pain medications—may be taxed depending on your state. These extras, while necessary, aren’t always categorized as tax-exempt medical care. Go over your itemized bill to look for non-covered services that include sales tax. The delivery may be done, but the charges often keep coming. Knowing what’s taxable can help you plan better for your birth-related costs.

2. Diapers and Baby Supplies

In many states, diapers are not considered a tax-exempt essential item. That means you’ll pay sales tax every time you restock. The same goes for wipes, bottles, and formula in certain locations. These expenses add up fast, especially in the first year when you’re going through several diapers a day. Check if your state offers exemptions on baby products and stock up during tax-free weekends when possible.

3. Out-of-State Online Purchases

Ordering baby gear online? If you buy from a seller in a different state, you might owe use tax, which is similar to sales tax but often overlooked. Many people don’t realize this applies to cribs, strollers, and other big-ticket baby items ordered online. Some states now enforce it more aggressively through income tax filings. That bargain deal could come with a tax surprise if you’re not careful. Always keep receipts and double-check your state’s rules.

4. Childcare Services

While you may be able to deduct some childcare costs using the Child and Dependent Care Credit, the services themselves are not tax-free. Most daycare centers must collect sales tax on registration fees, supply fees, and even tuition in some states. And if you hire a nanny directly, you could become a household employer responsible for employment taxes. Understanding these hidden costs can prevent you from misclassifying your caregiver and getting penalized later.

5. Breast Pumps and Lactation Products

Not all breastfeeding supplies qualify for tax-free medical use. If you buy a breast pump without a prescription or through a non-medical retailer, you may pay sales tax. Storage bags, nursing pads, and accessories are often taxed as personal items unless bundled with a qualifying medical device. The IRS considers some items deductible with an FSA or HSA, but not everything is covered. It’s worth knowing which products are considered medical necessities under your plan.

6. Baby Furniture and Safety Gear

Car seats are often tax-exempt thanks to federal safety programs, but other items like cribs, highchairs, and baby monitors usually are not. You’ll pay standard sales tax on most of your nursery purchases. And if you’re importing products from another country or shipping to a different state, you may face import duties or extra shipping taxes. These one-time purchases can pack a big financial punch when you’re not expecting the added cost.

7. Children’s Clothing

While some states do exempt children’s clothing from sales tax, others do not, or they set caps that don’t apply to higher-end or seasonal items like coats and shoes. Hand-me-downs help, but babies grow quickly and need frequent replacements. Seasonal shopping sprees can catch you off guard if you haven’t accounted for taxes. Watch for state-specific exemptions or sales tax holidays to stretch your clothing budget.

8. Baby Shower Gifts with Added Tax

If you’re registering for baby gifts and friends or family buy items online or from a store that ships across state lines, those items may be taxed differently depending on where they’re sent. This might not impact your wallet directly, but it can affect your registry value. Some online stores charge higher tax rates depending on shipping address. Always compare checkout totals and look for stores offering free tax days or incentives.

9. Social Security and Medicare Taxes on Paid Help

If you pay someone more than a certain threshold annually to watch your child, you may be required to withhold Social Security and Medicare taxes. This includes babysitters, nannies, or even relatives if the arrangement is formal. The IRS treats this as a household employee situation, and skipping the paperwork could result in penalties. This is one of the most overlooked unexpected taxes for new parents who hire in-home help.

10. Petty Travel and Hotel Taxes

Planning a getaway with your new baby? You’ll quickly notice that hotels charge occupancy, tourism, and other local taxes—sometimes adding 10% or more to your bill. That affordable “baby’s first beach trip” can rack up extra costs if you’re not paying attention to local tax policies. Always review total booking fees and check whether children’s items like cribs or rollaway beds come with additional charges.

11. Lost Deductions from Filing Errors

One of the biggest, unexpected taxes for new parents isn’t a fee—it’s a missed opportunity. If you forget to claim your child as a dependent, fail to update your filing status, or overlook credits like the Child Tax Credit, you could lose thousands in refunds. Filing correctly and promptly is essential. Consider using a tax preparer or software with family-focused features to avoid missing out.

Tax Time with a Twist

Having a baby comes with a whole new set of responsibilities—and taxes might not be the first thing on your mind. But those unexpected taxes for new parents can creep in quickly if you’re not watching for them. A little awareness now can save you money, reduce stress, and make sure your growing family stays financially healthy. When in doubt, ask questions and stay proactive with your planning.

Have you been surprised by a tax or fee you didn’t expect after becoming a parent? Share your experience in the comments to help other families avoid the same surprises!

Read More:

How Does Child Support Affect Tax Return?

Overwhelmed? 12 Essential Apps Every New Parent Needs Today

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Parenting Tagged With: baby budget tips, childcare costs, family tax planning, financial advice for parents, parenting expenses, parenting surprises, unexpected taxes for new parents

Here’s Why School Supplies Continue to Cost More and More Every Year

May 28, 2025 | Leave a Comment

Heres Why School Supplies Continue to Cost More and More Every Year

Every year, parents brace for the back-to-school season—not just for the new routines, but for the rising cost of everything from pencils to backpacks. What used to be a quick \$20 run to the store has ballooned into a triple-digit shopping spree for many families. The truth is, school supplies continue to cost more every year, and it’s not just inflation. A mix of economic shifts, changing classroom expectations, and marketing trends has turned basic supplies into big business. If you’ve been wondering why your back-to-school bill keeps growing, here’s what’s really driving the increase.

1. Inflation Hits Every Industry—Including Education

One of the most obvious reasons school supplies continue to cost more is general inflation. Just like groceries, gas, and rent, the price of manufacturing and distributing goods is going up. Companies that produce notebooks, markers, and glue sticks are passing those higher costs on to consumers. Shipping delays and rising labor costs only add to the problem. While inflation affects everything, parents feel it sharply during back-to-school season when multiple purchases stack up quickly.

2. Teachers Rely More on Parent-Supplied Materials

School budgets are tighter than ever, and many teachers are forced to ask families to supply more of what classrooms used to provide. From cleaning wipes to paper towels to printer paper, school supply lists have expanded beyond the basics. As schools shift more responsibility onto parents, the demand—and cost—goes up. It’s not uncommon for parents to purchase classroom materials that serve 20 students, not just their own child. The more that’s added to the list, the more school supplies continue to cost more.

3. Trendy and Branded Items Drive Prices Higher

That sparkly pencil pouch with a popular cartoon character? It costs significantly more than the generic version. Retailers know how to market to kids, and children often influence purchasing decisions. While basic supplies haven’t changed much in function, branding and design can double or triple the price. When kids beg for trending items and parents want to avoid a meltdown, budgets can quickly balloon. Even simple items like folders and lunchboxes are often more about style than substance.

4. Supply Chain Disruptions Are Still Rippling Through

Global supply chain issues that started during the pandemic haven’t fully recovered. Shortages of materials like plastic and paper, combined with slowdowns at shipping ports, have driven up prices for everyday goods. School supplies continue to cost more in part because it’s harder and more expensive to produce and transport them. When fewer items are available, prices naturally climb due to higher demand. These disruptions are often invisible to consumers but deeply impact what ends up on shelves.

5. More Tech Means More Expenses

Today’s school supply lists often include earbuds, USB drives, or even tablets, especially in districts that expect students to engage in digital learning. As classrooms become more tech-focused, the financial burden shifts to families to provide those tools. Tech accessories aren’t just more expensive—they often need to be replaced more frequently. As schools integrate more online learning, traditional supply lists grow to include items that stretch the budget even further. This digital shift is a key reason school supplies continue to cost more year after year.

6. Bulk Buying Isn’t Always the Best Deal

Buying in bulk seems like a smart money-saving move, but it can backfire. Some teachers request very specific brands or types of items, meaning that value packs go unused or aren’t acceptable. Additionally, warehouse stores often carry larger quantities than needed, which may cost more upfront even if the per-item price is lower. It’s not uncommon for families to overbuy, leading to waste rather than savings. Even when trying to save, many parents end up spending more than planned.

7. Uniform Policies and Dress Codes Add Up

While not technically “supplies,” clothing expenses tied to school are often included in families’ back-to-school budgeting. Many schools have strict dress codes or uniform requirements, forcing parents to purchase specific styles or brands. These items can be surprisingly pricey, especially if you have to buy multiple outfits, shoes, or accessories. When combined with traditional supplies, these expenses help explain why school supplies continue to cost more each year. It’s a hidden cost that often gets overlooked in average price estimates.

8. More Grade Levels, More Specialized Needs

As kids grow, so do their school supply needs. Older students may require scientific calculators, graph paper, art supplies, or more advanced writing tools. These specialty items often come with higher price tags and aren’t reusable year to year. Parents of multiple children in different grades feel this impact even more. It’s not just the quantity of supplies—it’s the complexity that causes school supplies to continue to cost more as students move through the system.

Why the Back-to-School Budget Feels Heavier Every Year

What once felt like a manageable seasonal task has turned into a full-blown financial event. From inflation to branded trends to shifting school policies, there’s no single reason school supplies continue to cost more—it’s the combined weight of many small changes over time. While some of these factors are out of your hands, being a savvy shopper, avoiding brand traps, and coordinating with teachers can help lighten the load. When families and schools work together, it’s easier to keep costs in check and focus on what really matters: giving kids the tools they need to learn and succeed.

Have you noticed your back-to-school costs rising? What tips have helped you manage the growing expense? Share your thoughts in the comments!

Read More:

12 Reasons Why Your Kids are Behind Academically

10 Surprising Facts About How Much School Uniforms Really Cost

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Finances Tagged With: Back To School Shopping, education costs, family finances, parenting expenses, rising prices, school budgeting, school supply costs, student supplies

Skip These 7 Expenses Most Parents Regret By Kindergarten

May 24, 2025 | Leave a Comment

Skip These 7 Expenses Most Parents Regret By Kindergarten

When you’re deep in the baby and toddler years, it’s easy to get swept up in the excitement—and pressure—of buying all the “must-haves.” But by the time your child hits kindergarten, many parents look back and realize some of those early purchases were more hype than help. Between clever marketing and social media comparisons, it’s easy to overspend on things that quickly gather dust or outlive their usefulness. If you’re looking for ways to save without missing out, knowing what to skip can be just as valuable as knowing what to buy. These common purchases often end up on the regret list once real-life parenting sets in.

1. Fancy Infant Shoes

Tiny baby sneakers are undeniably adorable, but they’re also completely unnecessary. Infants don’t walk, and these shoes serve no functional purpose aside from a photo op. They often fall off, get lost, or end up tossed aside after one wear. Soft socks or footed pajamas do the trick for warmth and comfort during the first year. When parents reflect on their early baby gear spending, designer shoes almost always top the regret list.

2. The Expensive High-Tech Monitor

Smart monitors that track breathing, movement, temperature, and more seem like a peace-of-mind essential. But many parents find themselves overwhelmed by false alarms, unnecessary data, or simply not using all the features after the first few weeks. A basic video or audio monitor often covers the real-world needs of everyday parenting. You’ll likely spend more time listening for real-time cues than analyzing sleep graphs at 2 a.m. As a baby grows, this pricey gadget often ends up unused in a drawer.

3. Matching Nursery Furniture Sets

Those Instagram-perfect nursery setups come with a hefty price tag, and many of the pieces aren’t built to last. Matching cribs, dressers, and changing tables often lack long-term function and don’t transition well as your child grows. By kindergarten, most kids are using completely different furniture, leaving that themed set behind. Parents often realize they could have mixed and matched more practical, budget-friendly options with the same result. Focus on function and flexibility, not showroom style.

4. Designer Diaper Bags

It might seem like a good idea to splurge on a designer diaper bag that doubles as a purse, but these often don’t hold up under real-life parenting mess. Spills, crumbs, leaky bottles, and mystery stickiness don’t care about price tags. Many parents switch to a more practical (and washable) bag within the first year. The emotional draw of having something “nice” for yourself fades quickly when you’re fishing out wipes with one hand while holding a squirmy toddler in the other. Save your splurge for something you won’t stain with puréed carrots.

5. Too Many Baby Clothes in One Size

It’s easy to fall into the trap of buying mountains of adorable baby outfits—especially in newborn and 0-3-month sizes. But babies grow fast, and many outfits barely get worn before they’re outgrown. On top of that, parents tend to reach for the same comfy, easy-to-change pieces anyway. Many clothes end up unworn, tags still on, or barely used before hitting the donation pile. A smaller, more practical wardrobe saves money and space.

6. Big Ticket Toys for Toddlers

That oversized play kitchen, luxury ride-on car, or elaborate climbing structure might seem like a solid investment. But these toys are often outgrown or collecting dust by the time kindergarten rolls around. Many parents find that their kids prefer cardboard boxes, open-ended toys, or active play outdoors anyway. The cost-per-use of these trendy big-ticket items is often disappointingly low. If you’re going to spend, make sure it’s something your child will grow with, not outgrow in a flash.

7. Monthly Subscription Boxes

Curated activity boxes for babies and toddlers can be fun, but they add up quickly, and not all are worth the recurring cost. Some boxes come with items you already have or activities your child loses interest in after five minutes. Many parents realize they could create similar DIY versions at home with cheaper materials and Pinterest. While one or two boxes might be a fun gift, signing up for a long-term subscription often leads to wasted money and forgotten boxes. Evaluate carefully before committing long-term.

Prioritizing Long-Term Value Over Short-Term Buzz

By the time kindergarten hits, many parents wish they had focused more on value and less on aesthetics or hype. The early years are filled with pressure to buy, but kids need far less than we’re led to believe. Choosing fewer, more functional items allows for more flexibility and less clutter and guilt later. Every dollar saved on regret purchases can be redirected toward experiences, education, or future needs. When in doubt, ask yourself: Will this still be useful in a year?

What baby or toddler purchase did you regret most by the time your child hit kindergarten? Share your stories in the comments and help other parents save smarter.

Read More:

8 Expenses for Children That No Parent Should Be Paying

7 Unexpected Expenses as Your Kids Get Older

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Budgeting Tagged With: baby budget tips, financial advice for parents, parenting expenses, saving money with kids, toddler gear regrets

6 Financial Traps Parents Fall Into Before Their Child Turns 5

May 23, 2025 | Leave a Comment

6 Financial Traps Parents Fall Into Before Their Child Turns 5

The early years of parenting are filled with unforgettable milestones—and a mountain of unexpected expenses. It’s easy to get swept up in the moment and spend more than planned, especially when you want the best for your child. But many parents fall into costly habits before their child even enters kindergarten, leaving their budgets strained and savings off track. Knowing what to avoid can make a major difference in your family’s long-term financial health. Here are six common financial traps parents fall into before their child turns 5—and how to steer clear of them.

1. Overspending on Baby Gear

New parents often feel like they need every gadget, brand-name stroller, and nursery accessory under the sun. From wipe warmers to baby food makers, the baby product market is full of items designed to make you think they’re essential. But most of these purchases end up collecting dust or being used for just a few months. Instead of buying everything at once, focus on the true must-haves and see what you can borrow, buy secondhand, or do without. Avoiding this financial trap gives you more breathing room in your budget and reduces waste.

2. Forgetting to Budget for Childcare

Childcare costs can be shocking, especially if you didn’t factor them into your budget early on. Whether it’s daycare, a nanny, or part-time help, these expenses often rival a second mortgage. Many parents underestimate the ongoing nature of these costs or delay planning until parental leave ends, leading to financial panic. Research local options well in advance and consider building childcare into your financial plan while you’re still expecting. This financial trap can be avoided with smart early planning and realistic expectations.

3. Neglecting Long-Term Savings

When diapers, daycare, and doctor visits dominate your spending, saving for the future can fall to the bottom of the list. But the earlier you start saving—whether for college, a home upgrade, or your own retirement—the better off your family will be. Many parents mistakenly assume they can “catch up later,” only to find that life’s expenses keep piling on. Automating a small monthly contribution to a savings or 529 account is a simple way to stay consistent. Skipping long-term savings is a financial trap that can leave your family playing catch-up for years.

4. Buying a Bigger House Too Soon

It’s natural to want more space when a baby arrives, but upgrading your home prematurely can stretch your finances thin. Larger homes come with higher mortgages, taxes, insurance, and maintenance costs. If you’re not truly ready financially, this move can create long-term strain that outweighs the benefits of extra square footage. Consider whether a more modest home—or staying put a little longer—can meet your family’s needs while keeping your finances stable. This is one of the most common financial traps that feels smart in the moment but adds pressure over time.

5. Ignoring the True Cost of “Free” Activities

Playdates, birthday parties, and mommy-and-me classes often seem inexpensive or even free at first glance. But they can come with hidden costs like gas, gifts, parking, snacks, or pressure to keep up with other families. These frequent small expenses add up quickly and can quietly drain your monthly budget. Be mindful about how often you’re saying yes to optional events or activities and don’t feel guilty for declining. Financial traps don’t always come in the form of big purchases—sometimes they sneak in through small, frequent spending.

6. Going Overboard on Milestone Celebrations

That first birthday party? It’s more for the parents than the baby, but it can still cost hundreds—or even thousands—if you’re not careful. While it’s natural to want to celebrate your child’s big moments, it’s easy to fall into the trap of Pinterest-worthy parties and over-the-top gifts. These events should be meaningful, not budget-breaking. Keeping things simple doesn’t mean you love your child any less—it just means you’re protecting your financial future. Avoiding this trap can free up funds for the things that matter most, like family time or future goals.

Smart Spending Starts Early

The early parenting years are full of joy, but they can also be a financial minefield if you’re not paying attention. Being aware of common financial traps helps you make better decisions without sacrificing your child’s happiness or comfort. It’s not about being stingy—it’s about being strategic so your money works for you in the long run. With a little planning and some perspective, you can enjoy these early years without sinking your budget. Your future self—and your growing child—will thank you for it.

Which financial trap do you wish you had avoided in your early parenting years? Share your experiences in the comments!

Read More:

7 Signs Your Kids Are Copying Your Worst Financial Habits

The Financial Trap of Parenting: What No One Tells You

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Personal Finance Tagged With: budgeting with kids, early childhood costs, financial traps, money-saving tips for parents, new parent finances, parenting expenses, smart parenting

Raising Kids Without a Village? You’re Probably Paying for It

May 19, 2025 | Leave a Comment

Raising Kids Without a Village Youre Probably Paying for It

The old saying “it takes a village to raise a child” used to reflect a very real truth. Grandparents lived nearby, neighbors helped each other, and friends dropped off casseroles just because. But for today’s parents, the “village” often feels like a ghost town. Whether it’s due to distance, busy schedules, or simply not having close relationships to lean on, parenting without support usually means doing everything solo—and it’s costing more than most people realize. In modern parenting, the absence of a village doesn’t just create emotional exhaustion—it has a very real financial impact, too.

From babysitting to burnout, the price of parenting without support adds up fast. If you’ve ever thought, “I shouldn’t have to pay for this if I had help,” you’re not imagining things. Here are some of the unexpected ways going it alone can drain your bank account, energy, and peace of mind.

1. You’re Paying for Childcare You Might Otherwise Get for Free

In generations past, it was common for grandparents or trusted relatives to pitch in with childcare. These days, without nearby family or willing helpers, parents often have to pay for every hour they need away from their kids—even if it’s just to run errands or go to the dentist. With daycare, after-school programs, and babysitters charging by the hour, costs can snowball quickly. Parenting without support often means spending thousands more per year just for coverage others receive as part of their community. In modern parenting, time truly is money.

2. Every Sick Day Becomes a Financial Juggle

When there’s no one to call in a pinch, sick days become more than a health concern—they become a logistical and financial crisis. Parents may have to miss work, burn through vacation time, or hire last-minute help to cover a sick child at home. The unpredictability adds stress and often lost income, especially for hourly workers or those without paid time off. Parenting without support turns routine illness into a major disruption.

3. Emotional Labor Turns Into Burnout

Being the only one juggling meals, school emails, appointments, tantrums, and bedtime routines eventually catches up. The cost of this emotional labor isn’t just physical—it often leads to burnout that affects your health, productivity, and even your relationships. Some parents end up seeking therapy, hiring life coaches, or investing in wellness programs just to stay afloat. Parenting without support often turns into self-funded survival.

4. You Outsource Out of Necessity, Not Luxury

Without trusted people to call on, outsourcing becomes less of a convenience and more of a lifeline. This includes hiring house cleaners, food delivery, tutors, or subscription services just to stay caught up. What used to be handled through shared community effort is now purchased through monthly fees and one-click orders. While these tools are helpful, they come at a cost many wouldn’t face if they weren’t parenting without support.

5. Social Isolation Adds Up Emotionally and Financially

When you’re doing it all alone, loneliness can creep in—even if you’re surrounded by your children. Many parents without a support system find themselves investing in therapy, parenting courses, or online communities just to feel seen and heard. Others overcompensate by spending more on outings, gifts, or experiences for their kids, trying to fill the emotional gap. Parenting without support brings both emotional and financial side effects that families must navigate daily.

6. The Cost of Missed Career Opportunities Is Real

When there’s no one to help with pickups, sick days, or after-school events, many parents turn down promotions, switch to part-time work, or leave the workforce entirely. Over time, this results in lost income, smaller retirement savings, and stalled career growth. It’s a long-term cost that doesn’t show up on your monthly budget—but one that affects your future security. A strong support network often enables parents to pursue their goals; parenting without support can limit those possibilities.

7. You Carry All the Decision Fatigue—and It Shows

From choosing meals to managing schedules, parents without backup carry all the mental load alone. Over time, this constant decision-making wears down your ability to plan, budget, or make smart choices—especially when you’re running on empty. That can lead to impulsive spending, forgotten bills, or missed opportunities. Parenting without support increases the daily strain, leading to emotional and financial missteps.

It’s Not Just Loneliness—It’s a Hidden Cost of Modern Parenting

If you’re parenting without a village and feel like you’re always one step behind financially or emotionally, it’s not just in your head. The gap left by missing support often shows up in your bank account, your stress levels, and your ability to recharge. Parenting without support may be common, but that doesn’t mean families are meant to do it alone. Building even a small circle of support—whether it’s a neighbor, a parent friend, or a paid professional you trust—can ease the burden and protect your well-being in the long run.

Have you felt the cost of raising kids without a support system? What do you do to make it work? Share your thoughts in the comments.

Read More:

Where to Find Financial Support for Single Dads?

How ‘Mom Guilt’ Is Destroying Family Budgets Nationwide

Catherine Reed
Catherine Reed

Catherine is a tech-savvy writer who has focused on the personal finance space for more than eight years. She has a Bachelor’s in Information Technology and enjoys showcasing how tech can simplify everyday personal finance tasks like budgeting, spending tracking, and planning for the future. Additionally, she’s explored the ins and outs of the world of side hustles and loves to share what she’s learned along the way. When she’s not working, you can find her relaxing at home in the Pacific Northwest with her two cats or enjoying a cup of coffee at her neighborhood cafe.

Filed Under: Parenting Tagged With: childcare costs, emotional labor, financial stress, modern parenting, parenting expenses, parenting without support, solo parenting

Next Page »
  • Facebook
  • Pinterest
  • RSS
  • Twitter

Basic Principles Of Good Parenting

Here some basic principles for good parenting:

  1. What You Do Matters: Your kids are watching you. So, be purposeful about what you want to accomplish.
  2. You Can’t be Too Loving: Don’t replace love with material possessions, lowered expectations or leniency.
  3. Be Involved Your Kids Life: Arrange your priorities to focus on what your kid’s needs. Be there mentally and physically.
  4. Adapt Your Parenting: Children grow quickly, so keep pace with your child’s development.
  5. Establish and Set Rules: The rules you set for children will establish the rules they set for themselves later.  Avoid harsh discipline and be consistent.
  6. Explain Your Decisions: What is obvious to you may not be evident to your child. They don’t have the experience you do.
  7. Be Respectful To Your Child: How you treat your child is how they will treat others.  Be polite, respectful and make an effort to pay attention.
Best Parenting Blogs

Most Popular

Baby

9 Unusual Baby Names That Sound Like They Belong to Future CEOs

Evan Morgan
Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Target Store

Choking Incident Prompts Recall of 49,000 Target Gigglescape “Under the Sea” Popping Toys

Evan Morgan
Frustrated Girl

Why Some Students on the Spectrum Are Labeled With ODD

Evan Morgan
Coke Bottles

12 Things Kids Took to School in the ’70s That Would Never Be Allowed Today

Evan Morgan

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette