• Home
  • About Us
  • Toolkit
  • Archives
  • Advertise
  • Privacy Policy

Kids Ain't Cheap

But They Sure Are Worth It

  • Parenting
    • Baby Stuff
    • Books and Reading
      • Aesops Fables
      • Comic Books
    • Education
    • Family Time
    • Green Living
    • Growing Up
    • Healthy Living & Eating
    • Holidays
    • Parenting
    • Random Musings
    • Shopping
    • Stuff to Do
  • Money
  • Product Reviews
    • Books and Magazines
    • Discount Sites
    • Furniture
    • House Keeping
    • Reviews News
    • Toys and Games
  • Contact Us
  • Our Editorial Commitment
  • Search

How To Afford Out-of-State Tuition

December 14, 2019 | Leave a Comment

how to make out of state tuition affordable

Every parent dreams of a full-ride scholarship for their child. I, personally, have high hopes on an Ivy League education. But full-ride scholarships aren’t always realistic. And what if your child wants to attend an out-of-state college?  

Out-of-state tuition can increase your education costs by over 100%. However, some options may make out-of-state tuition more affordable. 

Here are nine options to consider to make out-of-state tuition more affordable.

Flat Rate Tuition

Look for colleges that are on a flat-rate tuition policy. Flat rate tuition does not discriminate based on where you live; the cost is the same regardless of your residency.

An example of a university that charges the same tuition for in-state and out-of-state residents is Mississippi Valley University.

Student Exchange

Similar to studying abroad for a year, some schools allow an exchange to another university, for the same cost as your home school. Generally, these are available for one-year increments. Check out the National Student Exchange for more information.

Good Neighbor Policy

Neighboring states or counties may offer reduced tuition. It’s often not advertised, so it’s worth giving the financial aid office a call to ask what kind of assistance they can offer.

Low Out-of-State Tuition

Some colleges are cheaper than others, or the gap between in-state and out-of-state tuition is more narrow. West Texas A&M University in Canyon, Texas, is an example where the difference between in-state and out-of-state is less than $1,000 per year.

Waivers

Top performing students may be eligible for a non-resident tuition waiver. There may be certain restrictions, as every state has different regulations. For example, the student may need to be studying in a particular area. East Tennessee University has waiver options if you major in History. 

Reciprocity Agreements

Similar to good neighbor schools, some states hold agreements with other states to allow residents to swap states for the sake of saving on college tuition. The Western Undergraduate Exchange is an exchange of approximately 16 states on the West Coast that allow for reduced out-of-state tuition if you attend a school in one of the participating states. Deadlines are a big deal here – so make sure you apply early.

Legacy Scholarships

Legacy scholarships may be available for alumni of many colleges.

Tuition-Free Schools

In exchange for service, many schools offer free tuition. Alice Lloyd College in Kentucky is an example. Through a student work program, students may be eligible for free tuition. More schools are listed here.

Relocate

While not the most realistic of the options, it’s worth mentioning. Massive action produces massive results. If your child has their heart set on a specific school, and you have the flexibility to move – perhaps you work remote – this may be an option. It’s crucial to review residency requirements in each state as they often have loopholes that will hinder short term moves for the sake of paying in-state tuition.


Do you think out-of-state tuition is out of your reach? Share your concerns in the comments below.

Read more:

Are Parents Legally Obligated To Pay For College

Best Ways To Save On College Needs

7 Key Ways to Save for Your Kids’ College Education

Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.
Filed Under: Education, Money and Finances Tagged With: college education, college savings, in state tuition, out of state tuition

What To Do When You Are Overspending at Christmas

December 10, 2019 | Leave a Comment

Overspending at Christmas

I have a confession.

I overspent my Christmas budget.

(And I’m not done shopping.)

Overspending At Christmas

I did everything right. I made a list of who I was shopping for and created an overall budget. All was going well until I deviated from my plan.

Typically I plan a vacation for Christmas. I prefer to gift experiences to my family over wrapped presents. Last year, we went to Disney World. The year before, we went to Great Wolf Lodge.

However, this year, my daughter wanted a saddle, and my son had been asking for some 1000+ piece Lego sets. These were items I’d buy for my kids outside of Christmas, so I thought let’s go ahead and have Santa buy them. We’ll stay home this year and spend our budget on Christmas presents.

I also expected this would create a more relaxed Christmas. I wouldn’t have to coordinate the logistics of travel, and I wasn’t planning to buy much for Christmas. After all, the presents I was going to buy weren’t extra for the sake of Christmas.

I was wrong.

It’s not more relaxed and I’m buying more presents than what was on my list.

Creating A Budget Buffer

Something I always do is that I plan to go over budget ahead of time. I do this by creating a budget buffer – usually 5 to 10% of my overall budget. Because overspending at Christmas is not an unrealistic scenario.

Since we’re home this year, I’ve been more inclined to accept invitations to Christmas parties. Also, because we are home, we’re going to my in-laws Christmas morning. This added additional people to shop for that were not on my original list.

But good plans are fluid, so I adjusted the budget per person to accommodate the extras.

Another thing that surprised me is my kids wanted to buy presents for other people. I appreciate this, and it was a simple budget obstacle to overcome.

They pitched ideas on what they would do in exchange for extra money. I was able to secure some “maid” service for the next few weeks in exchange for some small gifts. The amounts were small enough that it didn’t set me over budget because I had built in a buffer for unexpected purchases.

Plan For Budget Obstacles

What I didn’t expect was nostalgia to travel over Christmas. Impulsively, I booked a 3-day trip to Legoland. I paid the full price for the hotel room and park tickets. I was able to use miles for two of our plane tickets and paid for the other two. This was the primary reason that led to my overspending at Christmas.

So what am I going to do now that I’m WAY over budget?

Good plans should be fluid and be able to accommodate roadblocks.

I have to sacrifice in other areas of my budget. I reduced the amount my husband is allowed to spend on me and I pulled from our travel savings account to cover the hotel and tickets.

To pay for the plane tickets, I pulled from January’s budget by cutting expenses. Food was cut back, clothing was eliminated, and I cut the flash cash budget in half.

What I Learned

Through this process, I have been reminded of how grateful I am that:

1) I have set my budget up to accommodate impulse decisions – knowing this is standard behavior for me,
2) I have diversified my income so that I know I can generate some back-up income when I needed, and
3) I am committed to remaining debt-free. A few years ago, I would’ve slapped the trip on a credit card and not thought twice about taking two years to pay for it.


Have you gone over budget this Christmas? How do you handle impulse purchases? Is your budget set up to accommodate your personality? Let us know in the comments.

Read more:

5 Ways to Buy Cheap Christmas Gifts for Kids

Three Things You Can Do to Make Money for Christmas

Favorite Family Christmas Traditions, Modernized!


Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.
Filed Under: Holidays, holidays, Money and Finances, Parenting Tagged With: buying gifts, Christmas budget, Holidays

4 Bad Habits that Are Costing Your Family Money

December 4, 2019 | Leave a Comment

Bad habits that cost family moneyFamilies, like individuals, can develop good and bad habits. And like people, most families have a few bad habits that they should try and break. What’s worse is that some behaviors aren’t just unhealthy or unproductive –– they’re actively bad for your financial well-being. Indeed, certain habits can cost families hundreds –– if not thousands –– of dollars every year. Here, we’ll list four bad habits that cost family money and explain what you and your kin can do to break them once and for all.

[Read more…]

Filed Under: KACURP, Money and Finances

Are Parents Legally Obligated To Pay For College

December 2, 2019 | Leave a Comment

Are Parents Legally Obligated To Pay For College

In August 2013, a New Jersey girl sued her parents for the cost of her college tuition. Caitlyn Ricci won that case in 2014, and the decision was upheld in court later that year. The details of the lawsuit is worthy of soap opera. Amongst which is that Ms. Ricci is estranged from her parents for failure to follow the rules laid out by her parents. While we leave the legal merits of the case up to the judges, it begs the question, are parents are legally obligated to pay for college.

This topic is particularly personal for me. We save money for our children’s college. However, I don’t necessarily plan on spending that money on college. My parents didn’t pay for my college. The education I gained from that alone was worth as much as the cost of my degree.

There is No Hard and Fast Answer

While there is no black and white answer, there are some signs that point to yes, parents are expected to contribute financially to their children’s higher education. This may not always come in the form of payment for a child’s tuition; it can be through other means of financial support, such as providing housing or transportation.

The State You Live In Matters

The case referenced above was filed in the state of New Jersey, which is a progressive state in terms of state laws that have been established which define parental requirements in terms of financial contribution towards a college education.

Each state sets its own laws, and some states such as California are on the other end of the spectrum and limit parental obligations. Overall, there is no specific requirement for parents to pay for their children’s college education in most states. However, if a parent is divorced, this may be a game-changer.

It Will Depend On The Parents Marital Status

The obligation is more strict when the parents are divorced.

When a marriage ends in divorce, and parents and children get involved, the parent with custodial rights generally receives some sort of financial contribution from the other parent. This is agreed upon as part of the divorce settlement, and higher education costs are typically included in the agreement.

Again, each state will differ – here is a breakdown of requirements by state.

The Child Must Participate In The Cost

There is an expectation that the child should make a reasonable attempt to contribute to their college education. In the case referenced above, Ms. Ricci’s parents appealed on the grounds that she did not apply for all applicable scholarships and loans. The claim was ultimately rejected in favor of the parents due to the fact Ms. Ricci was emancipated from her parents. Thus she showed intent to be independent of her parents. The court applied that independence to financial support, as well.


Do you think parents should be legally obligated to pay for college? Are you planning to pay for yours? Share your opinion in the comments below.

Read more:

Best Ways To Save On College Needs

7 Key Ways to Save for Your Kids’ College Education

5 Ways to Prepare Kids for College

Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.

Filed Under: Education, Growing Up, Money and Finances, Parenting Tagged With: college education, College Fund, parental obligations

How I Use Bank Accounts To Organize Our Finances

November 23, 2019 | Leave a Comment

bank accounts to organize finances

I recently went out on my own and started a financial consulting and bookkeeping practice. As the primary (and sometimes only) breadwinner for my family, this has thrown a bit of a wrench in our personal finances. Not only am I not getting a regular paycheck every two weeks, but I lost my employer-subsidized insurance and a 401k match.

Getting Financially Organized

I’ve spent the past few months researching our options for health insurance and identifying the best options for our retirement savings. I’ve also set up a process to make sure I save the appropriate amount for federal and state income tax because I don’t have an employer withdrawing it from my paycheck for me.

These changes were all things I was expecting. What I hadn’t realized the importance of was organizing our cash so it wasn’t all sitting in one big pile. To solve this, I set up multiple bank accounts to organize finances.

Given that my self-employment income is variable, and that my largest client pays me once a month, having separate bank accounts to disseminate my cash to is critical. If I keep it all in one account, including my tax estimate, I will be tempted to spend it. I know myself too well.

I’ve re-organized the flow of our family’s cash into five bank accounts. Each account has a designated purpose that allows us to optimally manage our money. The five bank accounts we now have are a family checking account, an emergency savings account, a family savings account, a medical expense savings account, and a flash cash account.  Separately, I have a business checking account and a tax account.

Family Checking Account

This is the primary bank account. All money comes and goes through this account. I transfer cash from my business checking account once a month to the family checking account. My husband’s paychecks are also deposited here. All bill payments are drafted from this account. Money is transferred to our other bank accounts from here, all via automatic draft.

Emergency Savings Account

We have an emergency fund in place to cover unplanned events such as home or car repairs, but mostly I’m always worried about an emergency trip to the veterinarian. We have a mischievous Great Dane, along with a few other critters. I don’t want to find myself in a position of saying no to a life-saving surgery because we don’t have the funds.

Family Savings Account

I funnel funds for everything we want to do that requires some savings over time. Things such as the next family vacation to Walt Disney World or Myrtle Beach, season passes to the museum or a new SUV.

It’s also our rainy day account.

Health Savings Account

While not a traditional bank account, we set up a health savings account.  A Health Savings Account (HSA) is an account specifically for health-related expenses. It’s tax-free and typically has a debit card assigned directly for payments from the account. The benefits of an HSA include the contributions and any earnings are tax-free and it can be rolled over into the next year.

Monthly, we are transferring cash to the HSA to cover future medical expenses.

Flash Cash Account

Otherwise known as a slush fund or fun fund. All our money left over after bills goes here. This money is used for date night, my Chai Tea Latte addiction, and money for all the fun things.

Sadly, it’s also used for not so fun things like the toilet seat cover we bought last night.

P.s I just heard about this great new fintech app called Astra.finance.  Basically Astra is a smartphone app that lets you automatically move around between your accounts.  This kind of thing is great if you have a steady income.  You can pretty much set up some rules and forget about moving your money.  It works for both checking and savings accounts.

Does your family use multiple bank accounts to organize finances? Let us know in the comments below.

Read more:

Five Ways Your Bank Can Help You Save for College

Child Savings – More Than Money in the Bank

Why We’re Opening a Bank Account For Our 3-Year-Old

Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.
Filed Under: Medical, Money and Finances Tagged With: bank accounts, finance organization, personal finance

Being a Parent Requires a Budget, Iban Wallet helps you to get there

November 20, 2019 | Leave a Comment

The capacity of a family to fulfill basic needs is a vital measure of its economic well being and stability. The family’s budget secures an acceptable living standard in their immediate community. Responsibilities become manifold when you become a parent. [Read more…]

Filed Under: KACURP, Money and Finances Tagged With: Budget, Iban Wallet

A Guide for Building A Child Trust Fund

November 15, 2019 | Leave a Comment

Child Trust Fund Guide

A child trust fund isn’t just for the Rockefellers and the Rothschilds of the world. They’re also for normal moms like you and me who want to leave a legacy for our children and our grandchildren, but you also need a child trust fund guide.

What Is A Child Trust Fund

Trust funds are a financial tool associated with estate planning. They represent a separate legal entity that holds assets such as cash and property for the future benefit of a child.  

Three terms that are helpful to understand are:

  • Trustee – the beneficiary of the trust, or the child
  • Grantor – the person who set up the trust
  • Trustee – the person or company that manages the assets of the trust

Why Do You Need One And How Does It Differ From A Will

The primary benefits of a trust include tax savings for the grantor and asset protection for the beneficiary.

A trust allows for the distribution of funds over time for a specific event, for example, monthly distributions to pay for a grandchild’s college expenses. With a trust, this is possible before the grantor’s death. A will does not go into effect until a person dies.

With a trust, the specific conditions set by the grantor are met. Where this is different than a will, is the property passed on through a will must enter probate, which can get messy, can cause delays, and can cost extra money. A trust is done outside of the court system so that you can avoid probate.

Types of Child Trust Funds

The most popular type of Child Trust fund falls under the term, Irrevocable Trust Funds (ITF). There are two major types of ITFs – Section 2503 (b) and Section 2503 (c).

Section 2503 (b) Minor Trust Fund – Qualifies for the annual gift tax exclusion based on current limitations. Distributions of the trust income to the child or a custodial bank account must be made on a yearly basis or more frequent basis. Access to the principal at the age of 21 is not required.

Section 2503 (c) Minor Trust Fund – Qualifies for the annual gift tax exclusion. All the money (both principal and income) in the trust must be transferred to the child at the age of 21.

How To Set One Up

There is a lot to consider when setting up a trust fund for your children. Not only are there legal and tax issues to consider, but you’ll also have an emotional impact to think about. For example, you’ll need to consider the individual personalities of your children. Do you believe they will be mature enough to receive a significant distribution of assets at the age of 21? If the answer is no, you’ll want to avoid the Section 2503 (c) fund.

Seek out the counsel of a qualified estate attorney during the process of setting up your trust. Their experience with the federal and state laws will ensure you, your children, and your assets are adequately protected.  

Do you have any experience setting up a trust fund for your kids? Tell us about it in the comments below.

Read more:

How to Prepare a Living Trust & Will for a Single Parent

7 Key Ways to Save for Your Kids’ College Education

Child Savings – More Than Money in the Bank

Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.
Filed Under: Education, Household, Money and Finances, Parenting Tagged With: child trust fund, Child Trust Fund Guide, education costs

Four Money Habits You Need To Teach Your Children

November 9, 2019 | Leave a Comment

money habits for kids

If you want your child to grow up as a financially independent adult, start teaching them money habits young. Today, I’m talking about four money habits you need to teach your kids if you don’t want them living at home until they’re in their thirties.

1. Delayed Gratification

As technology has changed throughout the years, we’ve adapted to receiving instant gratification. Think about how irritated you become when it takes longer than two days to receive a shipment. Thanks, Amazon Prime! When you don’t know an answer, it takes less than 60 seconds to search for the answer. Thanks, Google!

While these are amazing benefits of living in our modern world, having instant access to whatever we desire can lead to bad habits. Force your children to wait for something they want, even if it’s just a few minutes. For example, increase their allowance by 10% if they wait for payment on Saturday, instead of Friday. Small changes in your day-to-day living that delay access can lead to increased resistance to instant gratification for your child.

2. Compound Interest

Go beyond teaching your children the value of saving. Teach them the benefits of saving early, specifically how compound interest can grow their money over time.

You’ll want to keep the concept simple and age-appropriate. You can pay compound interest on their allowance while encouraging them to save up for something specific (say the latest video game). If you’re struggling with coming up with a way to teach them, consider this marshmallow game.

3. Live Below Your Means

I know with my kids, the minute I hand over their allowance, they’re already figuring out how many Pokemon cards they can buy. I have to remind them to split their money up into giving, spending, and saving categories. We even have these special piggy banks to make it fun.

While using this 3x concept, they’re learning to save and give, which is amazing. However, I’m more interested in teaching them to live below their means. When they get ready to buy their first home, I want them to laugh at what the bank is offering them for a mortgage. They’ll instinctively know that they don’t want to spend as much as they can afford. Instead, they’ll understand the value in living below their means, so they have additional money to fund their emergency fund and to put in the church plate, and to help a friend out in need without requiring them to repay the loan.

4. Creating A Positive Money Story

As we grow into adults, we create our own money story, and that money story is directly attributable to how we spend and save our money. Help your children the best money story for themselves, one that will provide them with a strong sense of balance between saving and spending.

While her program is not kid-related, Natalie Bacon’s course, Money Mindset for Her, is where I learned how my money story was leading to poor money habits, specifically to overspending. She taught me to change that story, and it continues to have a positive impact on my life a year later. If you’re not clear on your money story, consider giving her course a try. Then teach the principles to your kiddos. And even better, teach by example.

Lastly, it is important you make sure that you are making the lessons you teach your children relatable and memorable in some way. You may consider getting toys that teach kids about money, like these. You may also have good luck finding some money games to play with them as well. The most important this is you are passing down your knowledge of finance.

Do you have any additional money tips for kids? Let us know in the comments below.

Read More:

Year-round Money Saving and Fun Activities for Parents and Kids

The Average Grocery Bill for a Family of Four (and How to Save on Yours)

3 Unexpected Options for Stay At Home Moms to Make Extra Money

Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.
Filed Under: Money and Finances, Parenting Tagged With: kids and money, money habits for kids, money mindset

These Retailers Are Hiring For the Holiday Season

November 1, 2019 | Leave a Comment

Hiring for the holiday season

If you’re working your way through a mountain of debt, the best strategy is to prioritize income growth over cutting expenses. Ideally, you’ll do a mixture of both, but focusing on growth has a long term benefit.

You can increase your cash flow through a side gig, a promotion, selling clutter around your house, or from a second job. If you’re looking at the latter, you picked a good time. The holiday season is now, and retailers are looking to supplement their staffing schedules with able bodies.

Moreso, 2019 has a shortened holiday season due to a late Thanksgiving. In an attempt to lengthen the shopping season, retailers are rolling out sales and promotions early this year, so the hiring has already started.

Seven Retailers that Are Hiring for the Holiday Season

1. American Eagle Outfitters
2. Dollar Tree
3. Dick’s Sporting Goods
4. The Gap
5. Michael’s
6. Kohl’s
7. Target

According to Retail Dive, a publication dedicated to the retail industry, each of the above retailers is hiring at least 8,000 employees (Dick’s) and up to 130,000 (Target) employees during the holiday season.

Delivery Drivers Are Hiring

UPS, Fed Ex, and the US Postal Service are hiring, too! All those Amazon packages need to be delivered. As internet sales continue to rise, the demand for drivers has increased accordingly. Particularly, since Amazon now offers same and next day in many locations.

Money Making Apps

Do you have the entrepreneurial spirit? Hoping a seasonal gig might blossom into something robust enough to replace your day job? The sharing economy makes it possible to start small, dip your toes in the water, and try it out. The holiday season is the perfect time to experiment.

Become a driver for Uber or Lyft. Grocery shop for a frazzled working mom relying on Instacar or Shipt to deliver groceries while she cooks an amazing Thanksgiving dinner for her extended family of 40. If you’re skilled in a particular area, pick up jobs on TaskRabbit or BlueCrew.

Tips to Getting Hired This Holiday Season

Start now

The holiday hiring season starts early. The sooner you get your application in the door, the better. But also, don’t assume it’s too late.  Retailers may hold back their hiring early in the season, only to increase their numbers if the shopping demand comes to fruition.

Attend an Open House or Job Fair

Many retailers will hold an open house for the purpose of mass hiring. Check their website for the next available date. If you can’t find anything on their website, visit the store locally and ask to speak with the manager.

Tell Everyone You Know

Tell your mom, your brother, your neighbor. Let them know you’re looking for some additional work for the holiday season to boost your savings account. You’ll be surprised who has a cousin that works at Target or an uncle looking for someone to help clean out his garage.
Networking doesn’t have to be attending an event and handing out a business card. The best networking comes through genuine conversations.

Have you taken a second job specifically during the holidays? Let us know in the comments below.

Read more:

How to Pay for Vacations and Holidays Without Debt
Staying Organized During the Holidays
7 of the Best Ways to Make Money on the Side With a Full Time Job
Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.
Filed Under: Holidays, Money and Finances Tagged With: holidays without debt, how to get hired, part time job, side gig, side hustle

Are Grocery Delivery Services Worth It?

October 25, 2019 | Leave a Comment

grocery delivery service
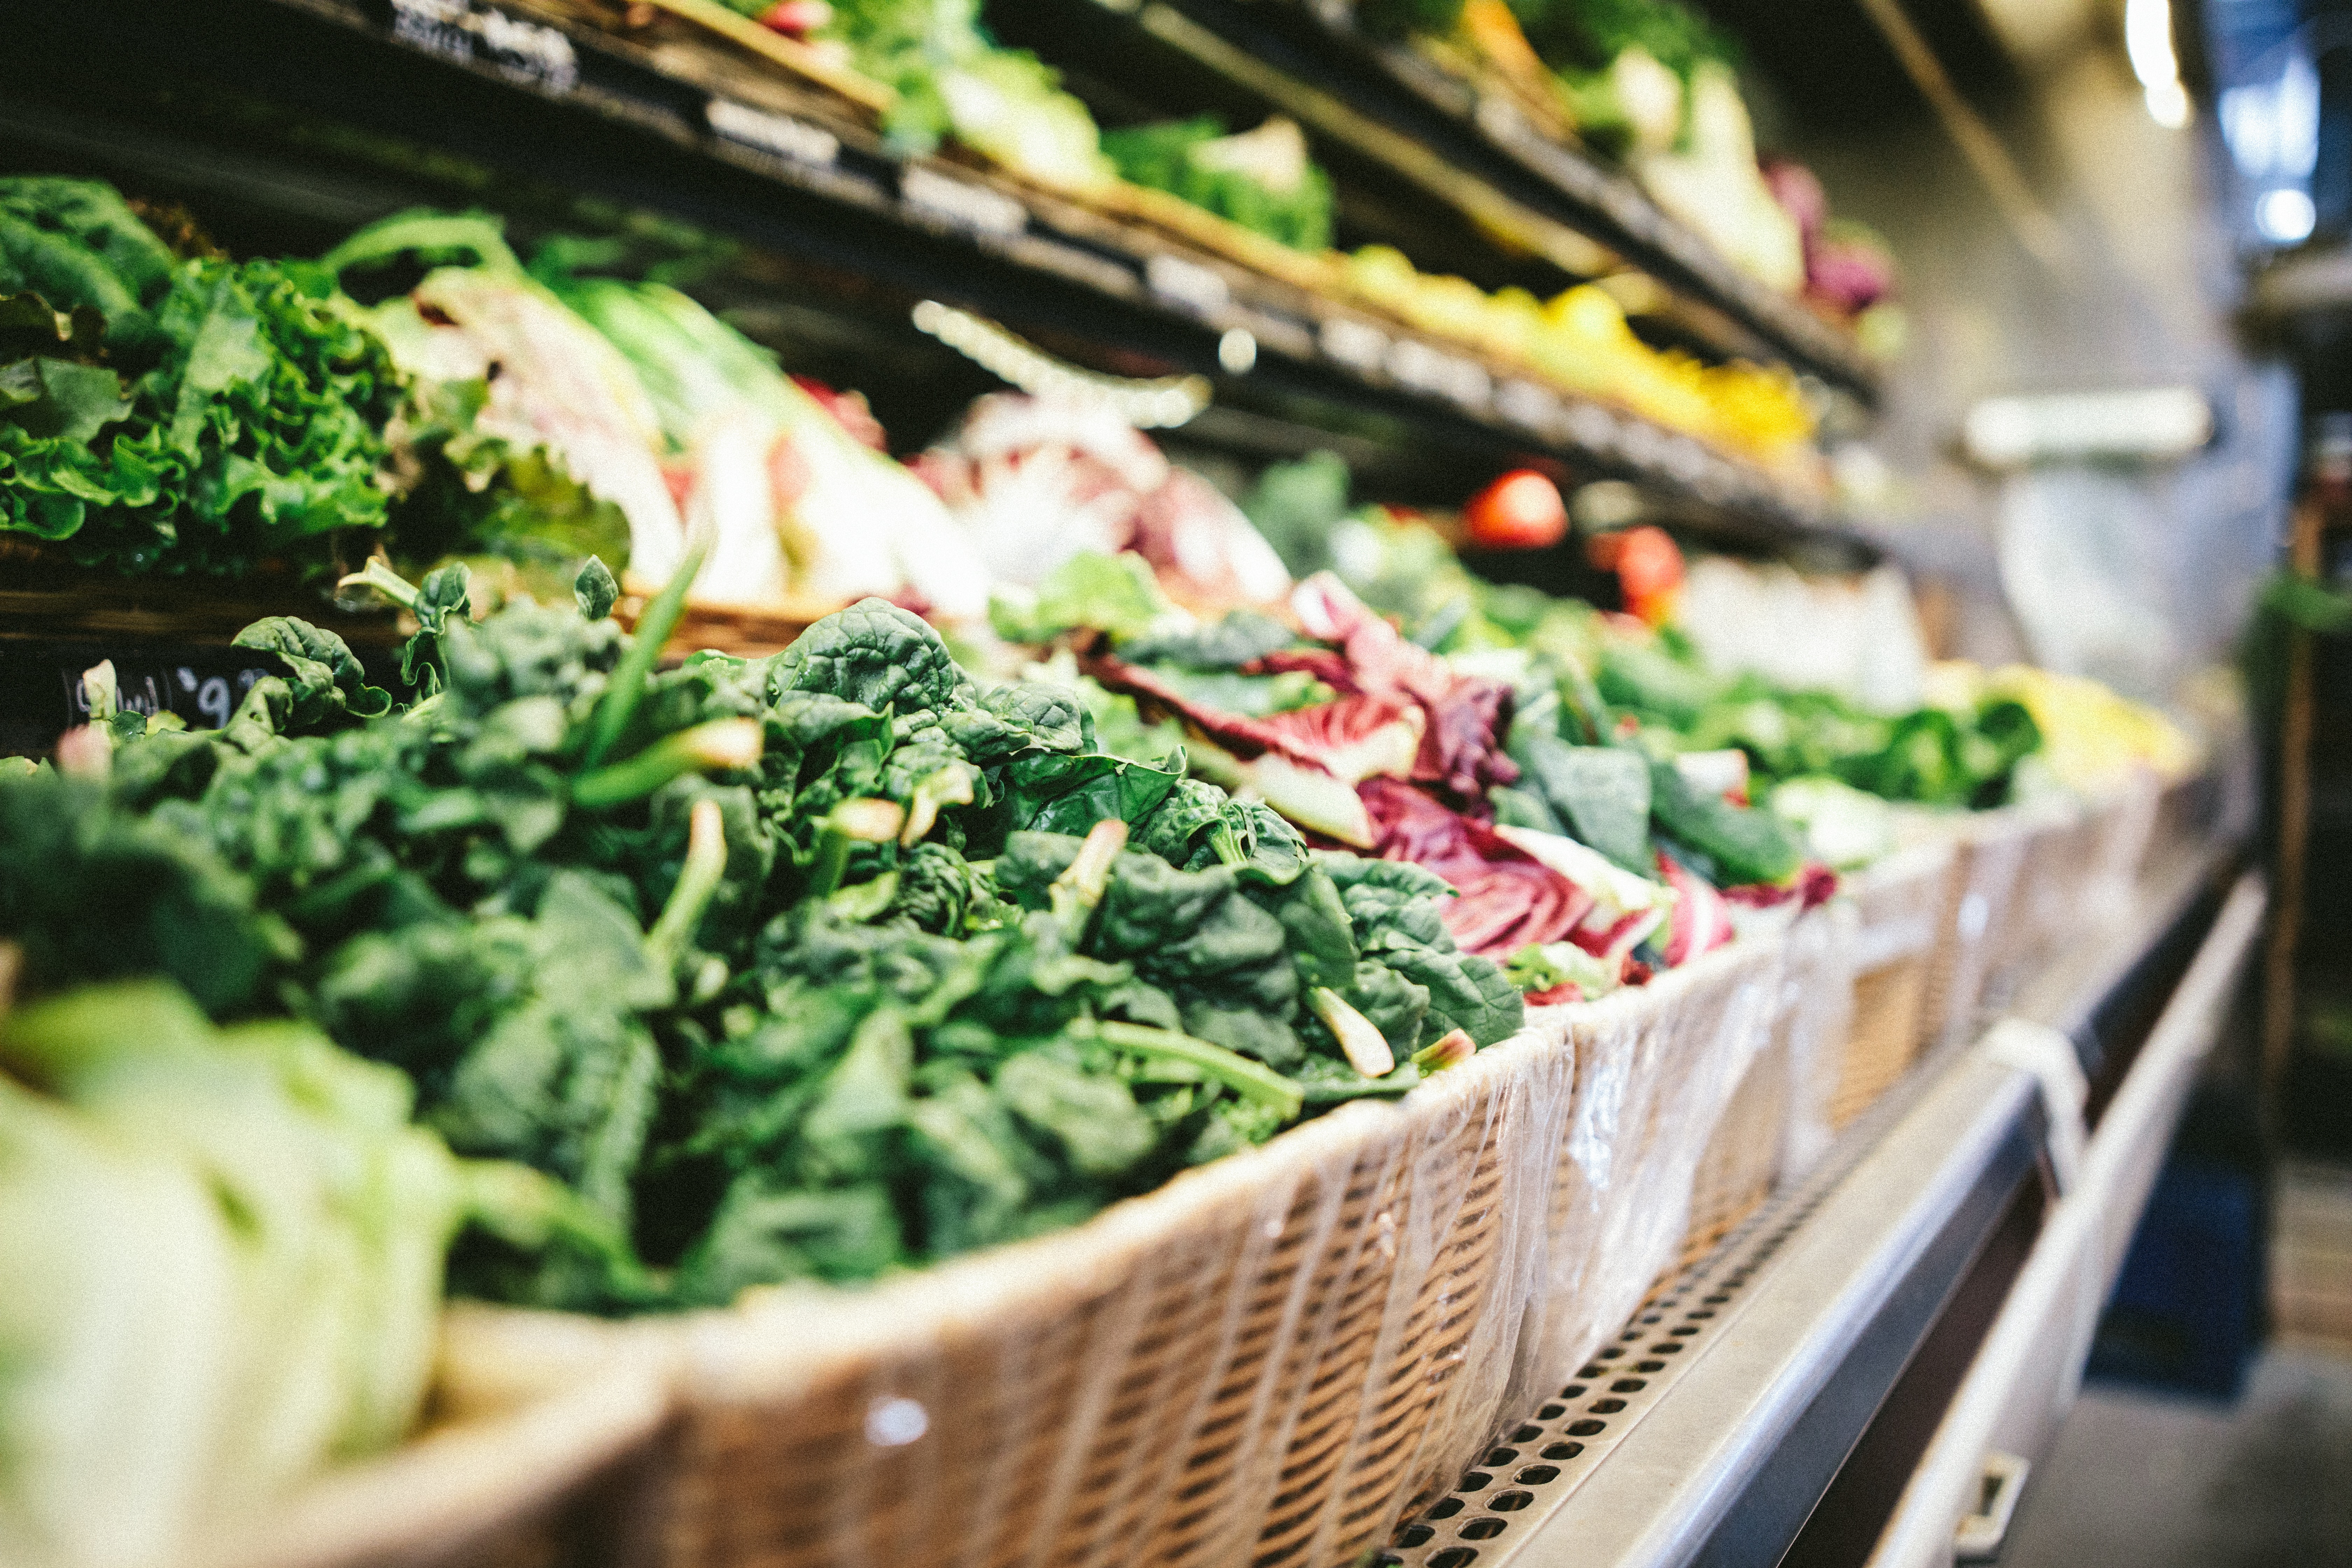
As the gig economy continues to grow, more and more services are being offered to provide you with the opportunity to never leave your house. One of the delivery services that continues to grow and is being provided by more and more companies is grocery delivery. Some of the top companies are Instacart, Shipt, and Walmart.  Thrive Market is a great organic option.

But the big question on our minds is – is it worth it?

Does Grocery Delivery Service Save Time?

Yes, it does.

Consider the time it takes to drive to the grocery store, plus park, grab a shopping cart, and walk up and down the aisles. Depending on the time you visit the store, you may have to stand in line, then walk back to the car, load up your groceries, and drive home.

With grocery delivery service, you need to spend a few minutes with your computer, selecting your items and putting them in your virtual cart. Thus, the time doesn’t decrease from 60 minutes to 0, but the savings are tremendous.

Does it Save Money?

The short answer is it depends. Considering it saves time, then yes, because time is money.

Yes, if you’re an impulse shopper. Having your groceries delivered can bring savings to your budget. Consider how often you’re going down the aisle and toss a few things in your cart. Each time you deviate from your list of groceries, you hike up the total cost — usually resulting in exceeding your food budget.

Where I believe a grocery delivery service does not save money is if you are NOT an impulse buyer and are good at spotting deals, shopping from the discount aisle (especially meat). Or, if you’ve got the time and the desire to shop multiple stores.

Also, any fees you pay for the service and any tips you give to your shopper will eat into your savings and possibly cost you more. In this case, it will be your decision whether the time savings, avoidance of crowds, and convenience factors make it worth it. At this point, it becomes a personal preference.

Because personal finance is personal.

An Alternative to Grocery Delivery Services:

If you love the convenience of grocery delivery services, but don’t want to pay the fee, or the tip, consider something similar – grocery pick-up services. Walmart, Target, and Harris Teeter all offer grocery pick-up service. Walmart and Target are free; Harris Teeter charges a nominal fee.

It follows the same concept as a delivery service – you order your items online and schedule a time for pick-up.

Pick-up is my personal preference as I’m an impulse shopper. Ordering online allows me to avoid purchasing things I don’t need, yet I still save time. I pick up my groceries while I’m in the area. Often there is a longer wait than I prefer, but I use that time to read a book or get some work done.

Do you use a grocery delivery service? Let us know in the comments below.

Read More:

The Average Grocery Bill for a Family of Four (and How to Save on Yours)

Meal Planning For A Family On A Budget

How to Become a Couponer: A Beginner’s Guide to Help Get Started

Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.
Filed Under: Money and Finances, Shopping Tagged With: budgeting, Grocery Shopping, saving time

The Average Grocery Bill for a Family of Four (and How to Save on Yours)

October 18, 2019 | Leave a Comment

average grocery bill

Do you ever read those outrageous headlines that read, “How I Feed My Family of Seven on $75 a Month” or something similar? They always manage to make me feel like I’m missing something. The grocery bill for my family (of four) would never come close to being that small for one month. Therefore, it got me thinking.

What is the average grocery bill for a family of four?  

The Food and Nutrition Service of the US Department of Agriculture provides guidelines based on “a nutritious diet where all meals and snacks are prepared at home.” The guidelines are based on four levels of spending: thrifty, low-cost, moderate, and liberal. Furthermore, they are divided by age and gender.

According to the FNS, a four-person family made of one female age 35, one male age 37, one boy aged five, and one girl aged eight would have an average monthly grocery bill between $612 and $1,707. By comparison, the break-down between plans is $612 on the thrifty plan, $792 for the low-cost plan, $989 under the moderate plan, and $1,207 under the liberal plan.  

Admittedly, $1,000 on a moderate budget for a family of four eating solely at home seems high to me.

However, if you factor in organic food and the cost of living in highly populated cities such as San Francisco, Los Angeles, and NYC, this seems more reasonable.

Three tips to decrease your grocery bill

Each year, the cost of food rises. Typically with the cost of inflation, but often more due to the state of the economy and other factors such as natural disasters and other weather-related incidents. However, when trying to cut expenses in our budgets, groceries are one of the first places we look.

If you find yourself on the high end of the averages listed, here are three tips to help offset some of the rising costs and/or bring down your grocery bill.

1. Meal Plan

Meal planning is one of the best things you can do to eliminate food waste and to spend your grocery dollars with intention. Try planning one week at a time, including multiple meals with the same type of protein, which allows you to buy the most expensive item on your meal plan in bulk.


2. Use Money Saving Apps

Couponing has gone digital. Specifically, Ibotta, Fetch Rewards, and Checkout51 are a few of my favorite money-saving apps. Sit down with the meal plan you created above and add any items on your list directly through the app. Scan your receipt after you shop and instantly save. After you’ve accumulated so much in savings, you can transfer it in the form of PayPal or gift cards. It takes some time to get used to, but I’ve found them to be worthwhile.

3. Shop Your Pantry

Before you sit down to meal plan, take a look around your refrigerator, your freezer, and your pantry. I guarantee you have enough for one meal. You may have to get creative and hodgepodge a few items together, but you’ll be surprised how much you already have on hand. Not only is it a great way to reduce your grocery bill, but also be a good steward of the environment.


How much is your average grocery bill in your family? Let us know in the comments below.

Read more:

Meal Planning For A Family On A Budget

How to Become a Couponer: A Beginner’s Guide to Help Get Started

Experts Say That These Are the Most Unique Ways to Save Money in 2020

What Is a Speakeasy? 5 Common Questions and Answers

Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.

Filed Under: Money and Finances Tagged With: Budget, Grocery Shopping, Meal Planning

Four Legitimate Work From Home Jobs For Moms

October 11, 2019 | Leave a Comment

Work From Home Jobs For Moms

Last week I talked about three ways moms can make extra money. Today I want to continue the discussion with additional jobs to make money, specifically work-from-home jobs.

Four Legitimate Work-From-Home Jobs For Moms

1. Court Transcript Proofreader

They’re, their, there – if you know the difference between these three words and have an eye for detail, proofreading court transcripts may be just the thing for you. Court testimony is often transcribed word-for-word for future reference. A court reporter captures the live conversation with a stenotype. Because the reporter is simultaneously typing and listening, there is room for error. That’s where a proofreader adds value to the process.

Your primary tool will be an iPad and your eagle eye for grammatical errors. English teachers are great candidates for this side gig, as are you if you’re the kind that scours social media comments looking for the wrong use of the word “affect”.

If this is something that interests you, check out Proofread Anywhere. Caitlyn Pyle s a former court transcript proofreader who created a course to teach you to do the same. Included in the course is how to find clients. There is a free quiz to see if it’s something you have an aptitude for and might enjoy.

If court transcription proofreading doesn’t thrill you, you can also provide proofreading services to blogs, books, and website copy. These avenues are often less technical than court transcription proofreading.

As a mom, you can do this job from anywhere – your couch, the car while your son is at soccer practice, or on the plane to Disney World.

2. Life Coach

Do your friends and family come to you for advice? Do you like to serve and help people? Are you big on self-improvement? If you answer yes to each of these questions, you may want to consider becoming a life coach. A life coach is someone who helps others with struggles in their life and/or provides guidance and direction to lead them towards their personal goals. 

A life coach may be a generalist or may specialize in weight, business, or even organization. It’s different from therapy but can serve as a partner to a mental health professional. Life coaching is an up and coming profession. Brooke Castillo likens it to the rise of the gym. In the 70s, no one had gym memberships. As health and personal care started to rise in the 80s and 90s, a gym membership became the norm. Think of life coaching as the present-day equivalent of a gym membership. In a decade or so, everyone will have a life coach.

There are many avenues available to become a life coach. Tony Robbins has a program, as does Martha Beck. Brooke Castillo has one of the best programs, and I’m a big fan of her podcast. A great example of a successful life coach who makes seven figures working from home three days a week on her business, while a full-time mom of four is Jody Moore. She is a student of Brooke’s and is evidence a life coach is an excellent work-from-home option for moms.

3. Pinterest Virtual Assistant

Do you love social media? Do you spend your free time scrolling Pinterest for your next recipe? You can earn an income off your love of Pinterest. Along with the rise of internet businesses and blogs, social media has taken in growth as a marketing tool. Pinterest continues to rise and is a popular search engine alternative to Google. 

Online entrepreneurs recognize the value of Pinterest to their bottom line, but don’t want to spend the time building their Pinterest presence. As a result, you can capitalize on this need by creating Pinterest graphics. You don’t need a graphic design degree. You can create professional-looking graphics using free tools such as PicMonkey, Canva or Instasize.

As a Pinterest VA, you’ll create and upload pins for blog articles or merchandise for sale. You’ll create pin descriptions using appropriate keywords and possibly optimize your client’s Pinterest profile.  A VA can work from anywhere and anytime, so makes a perfect option for moms to generate extra money. 

Interested in learning more? Gina Horkey and Kristin Larsen have a great class called Pinterest VA. Furthermore, as a VA you can offer virtual assistant services for just about any social media platform, such as Instagram, Facebook, or YouTube.  

4. Capitalize on your 9-to-5 skills

Do you have a college degree? Did you work a traditional job before becoming a SAHM? You likely have a set of marketable skills that can be done from home. You probably also have a built-in client base and network you aren’t even aware of.

Let’s say you were a journalist in your working days. You can reach out to your former boss and request some freelance writing work. Perhaps you were an accountant and know your former employer needs some part-time help during tax season. Put a proposal together to offer your services as an independent contractor. In your proposal, note you already have a working space (because your dining table counts) and high-speed internet that would allow you to work from home.

You can also market your skills to the general public. If you were a chef pre-kids, and want to share your love of vegetarian cooking, create a blog and sell an online course for a stream of passive income.  Market to other moms who are trying to teach their picky children the value of a vegetarian diet.

The opportunities are endless with your current skillset. Brainstorm your skill sets and find one that you can offer from home, then market it. You may have to think outside the box, but the rewards are worth it.


Do you work from home as a mom? Share what you do and how you got started in the comments below.

Read more:

6 Must-Haves for Working Moms Who Breastfeed

3 Unexpected Options for Stay At Home Moms to Make Extra Money

Get Some Extra Cash: 9 of the Best Ways to Make Money From Home


Kate Fox

Kate Fox is a former CPA, with twenty years of experience in public accounting and corporate finance. Born and raised in Alaska, Kate is currently based out of southeastern North Carolina.  She loves coaching others on personal finance and spends her free time traveling with her family or relaxing by the pool with a good book, probably about money.
Filed Under: Money and Finances Tagged With: extra income, extra money, side hustle, work from home, Working Mom

« Previous Page
Next Page »
  • Facebook
  • Pinterest
  • RSS
  • Twitter
Best Parenting Blogs

Most Popular

Baby

10 Baby Names That Were Once Considered “Grandparent Names” but Feel Cool Again

Evan Morgan
Baby

9 Baby Names Inspired by Fall Without Naming Your Child Autumn

Evan Morgan
Baby

9 Baby Names That Sound Expensive Even Though Naming Your Baby Is Still Free

Evan Morgan
Baby names

Teachers Admit: These 6 Baby Names Create Instant Bias in the Classroom

Latrice Perez
6 Baby Names That Sound Cute Now but Cause Problems Later

6 Baby Names That Sound Cute Now but Cause Problems Later

Brandon Marcus

All content on Kids Ain’t Cheap is for entertainment purposes only. By reading this blog, you agree that Kids Ain’t Cheap is not responsible for any actions taken after reading this blog. For the full disclaimer, see our privacy policy.

Please note that Kids Ain’t Cheap has financial relationships with some of the merchants mentioned here. Kids Ain’t Cheap is funded by banner advertising, commission sales and search optimization consulting.

Copyright © 2006–2026 | District Media | All Rights Reserved | Privacy Policy

Copyright © 2026 Runway Pro Theme by Viva la Violette